A$40 million IPO funds OWL development and 2,500-unit capacity target

4 min read
4:50pm on Friday 18th of September, 2026 AEST ~4pm, 18th Sept, 26
Innovaero Technologies is seeking A$40 million through a proposed ASX listing to advance its OWL loitering munition program and expand manufacturing capacity. The replacement prospectus also makes clear that the company remains loss-making and heavily dependent on the Department of Defence converting development work into production orders.
- A$40 million IPO at A$0.50 per share
- 58.2% of proceeds earmarked for product and platform development
- Department of Defence accounted for 71.2% of CY25 revenue
- A$14.4 million revenue forecast for the six months to 31 December 2026
- Proposed ASX code INN, subject to listing conditions
Innovaero Technologies Limited (ASX:INN) is asking investors to fund the difficult part of the defence technology story: turning prototypes and development contracts into repeatable production. The Perth-based aerospace group has lodged a replacement prospectus for an initial public offering of 80 million shares at A$0.50 each, targeting A$40 million before costs and an indicative market capitalisation of A$158.3 million on admission.
IPO proceeds target OWL development and production capacity
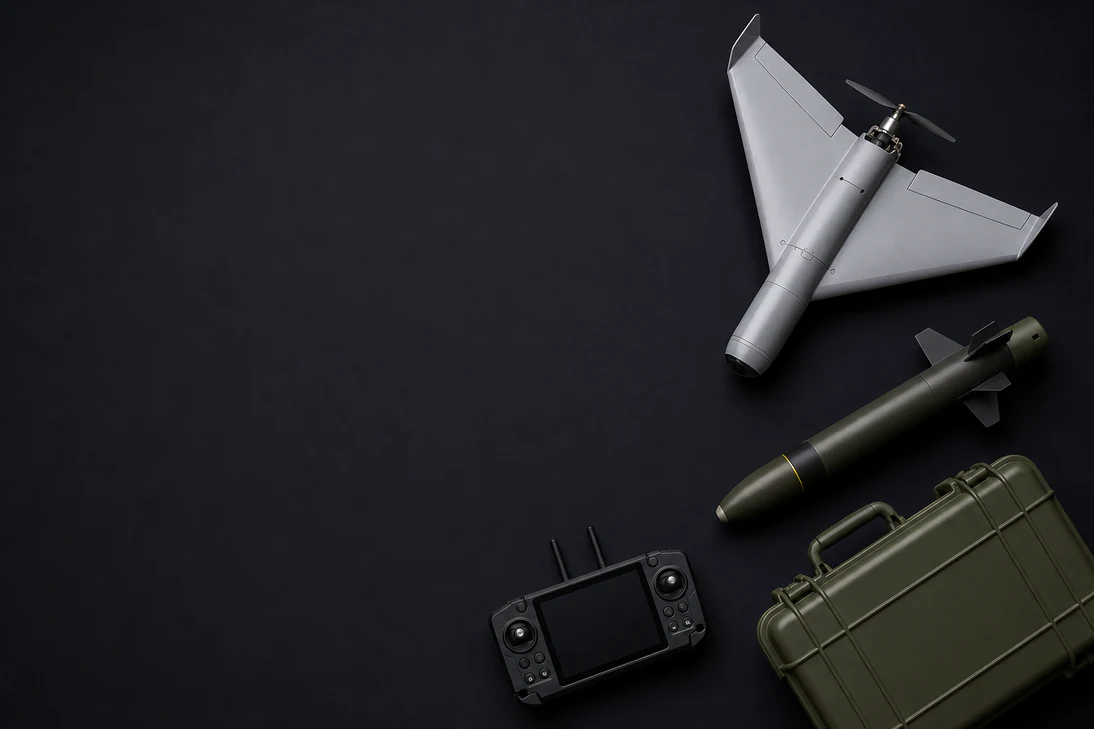
Nearly three-fifths of the raise, or A$23.3 million, is earmarked for developing the OWL family of uncrewed systems, including the OWL-B loitering munition and the OWL-X interceptor. A further A$9.5 million is allocated to facilities and production infrastructure, including a planned research, development and low-rate manufacturing facility at Jandakot in Western Australia. Innovaero says its current capacity is about 250 units a year and is targeting up to 2,500 units on a one-shift basis, although it stresses that this is a capacity target rather than a production forecast.
The company’s most important commercial bridge is the Mission Talon-Strike contract with the Commonwealth, awarded through the Advanced Strategic Capabilities Accelerator. The contract, for the development and testing of OWL-B, was valued at approximately A$24.2 million excluding GST after a variation. Innovaero says it has met all deliverables required to date, but the contract runs only to 15 April 2027 and can be terminated or reduced in scope by the Commonwealth. A production and manufacturing contract has not yet been awarded.
Revenue forecast rests on milestones and one major customer
Directors forecast A$14.4 million of consolidated revenue for the six months ending 31 December 2026. Of that amount, A$12.4 million is attributed to contracts or purchase orders, including A$10.1 million from Mission Talon-Strike and A$2.3 million from Eagleview Technologies; the remaining A$2 million is uncontracted revenue based on known opportunities and historical levels. Recognition of the contracted amount remains conditional on meeting milestones covering OWL-B hardware, performance demonstrations and supporting documentation.
The concentration risk is substantial. The Department of Defence represented 71.2% of Innovaero Holdings’ revenue in CY25, while the group’s historical revenue fell from A$14.8 million in CY23 to A$12.05 million in CY25 before the current development program gathered pace. Innovaero recorded a collated FY26 loss after tax of A$5.9 million and EBITDA of negative A$4.9 million; those full-year figures are a summation of reviewed half-year periods rather than a separate full-year audit or review. The prospectus describes the company as cash-flow positive but loss-making and says it does not expect to pay dividends in the foreseeable future.
Listing structure leaves execution and liquidity questions
If the minimum subscription is raised and ASX conditions are met, the new shares would represent about 25.3% of the enlarged issued capital. Pre-IPO convertible notes are expected to convert into approximately 66.8 million shares, while up to 177.6 million shares, or about 56.1% of the post-listing total, may be subject to ASX-imposed or voluntary escrow arrangements. The offer is not underwritten, making the A$40 million minimum subscription and ASX admission conditions central to the proposed transaction.
The prospectus identifies further pressure points beyond customer concentration: the need to obtain or maintain CASA approvals and upgrade Defence Industry Security Program membership, reliance on specialised suppliers, recruitment of scarce aerospace personnel, protection of largely unpatented OWL intellectual property and the cost and timing of new facilities. Those risks matter because the IPO’s central promise depends on several hand-offs occurring in sequence: qualification, customer acceptance, production contracting and manufacturing scale-up. The first market test is whether the raise completes; the more consequential one is whether OWL-B becomes a product the Defence Department buys in volume.
Bottom Line?
The IPO provides Innovaero with capital to pursue production, but the investment case remains tied to converting Mission Talon-Strike development work into a contract that has not yet been awarded.
Questions in the middle?
- Will the A$24.2 million Mission Talon-Strike program transition into a production contract before development funding ends in April 2027?
- Can Innovaero expand manufacturing capacity without disrupting its existing CASA approvals, delivery schedules or cash position?
- How quickly can the company reduce its dependence on the Department of Defence and convert overseas distribution arrangements into revenue?