Pinnacle Finds a New US Tungsten Opening in Utah

Pinnacle Minerals has agreed to acquire an option over five early-stage Utah tungsten projects and plans to raise up to A$1.3 million to fund the move. The deal would reshape the company’s US exposure, board and capital structure, but remains subject to shareholder approval and several title, access and funding conditions.
- Five Utah projects covering 199 claims and approximately 4,000 acres
- Up to A$1.3 million placement at 4.5 cents a share with attaching options
- 33.3 million shares plus 33.3 million performance shares for APT Tungsten
- Hero selected as the priority project for exploration from January 2027
- No Mineral Resource or Ore Reserve; sampling results are selective and non-representative
 Add us as a preferred source on Google
Pinnacle Re-enters US Critical Minerals With Utah Tungsten Deal
Pinnacle Minerals Limited (ASX:PIM) is making a sharp return to US critical minerals, agreeing to acquire 100% of APT Tungsten Limited and its exclusive option over five Utah tungsten projects. The portfolio covers 199 unpatented mining claims across roughly 4,000 acres in Box Elder, Millard and Juab counties, with exploration targeted to begin in January 2027 if shareholders approve the transaction.
The move reverses the company’s earlier retreat from US ventures, after Pinnacle had exited eight US projects while retaining Australian and Canadian assets. This time, the attraction is tungsten, which Pinnacle describes as a US critical mineral with applications in defence, aerospace and advanced manufacturing, alongside tighter US defence sourcing rules scheduled to apply from 1 January 2027.
A$1.3 Million Placement Underwrites the Transaction
Pinnacle will pay for APT entirely in securities, issuing 33.3 million ordinary shares valued at 4.5 cents each and 33.3 million performance shares. Each performance share would convert into one Pinnacle share if the company’s 20-day volume-weighted average price reaches at least 9 cents within three years; otherwise, it lapses.
Alongside the acquisition, Pinnacle intends to raise up to A$1.3 million at 4.5 cents a share, with one free attaching PIMOB option for every two shares subscribed. American Tungsten & Antimony (ASX:AT4) has committed A$412,066, which would give it an expected 5.01% stake and substantial-holder status after completion. The deal requires the placement to raise at least A$1.2 million.
On the company’s maximum-case calculations, shares on issue would rise from 117.2 million to 182.8 million at completion, before any options or performance securities convert. The fully diluted figure would be approximately 348.9 million securities, assuming shareholder approval for the proposed adviser, director and employee incentives.
Hero Leads an Exploration Portfolio Without a Resource
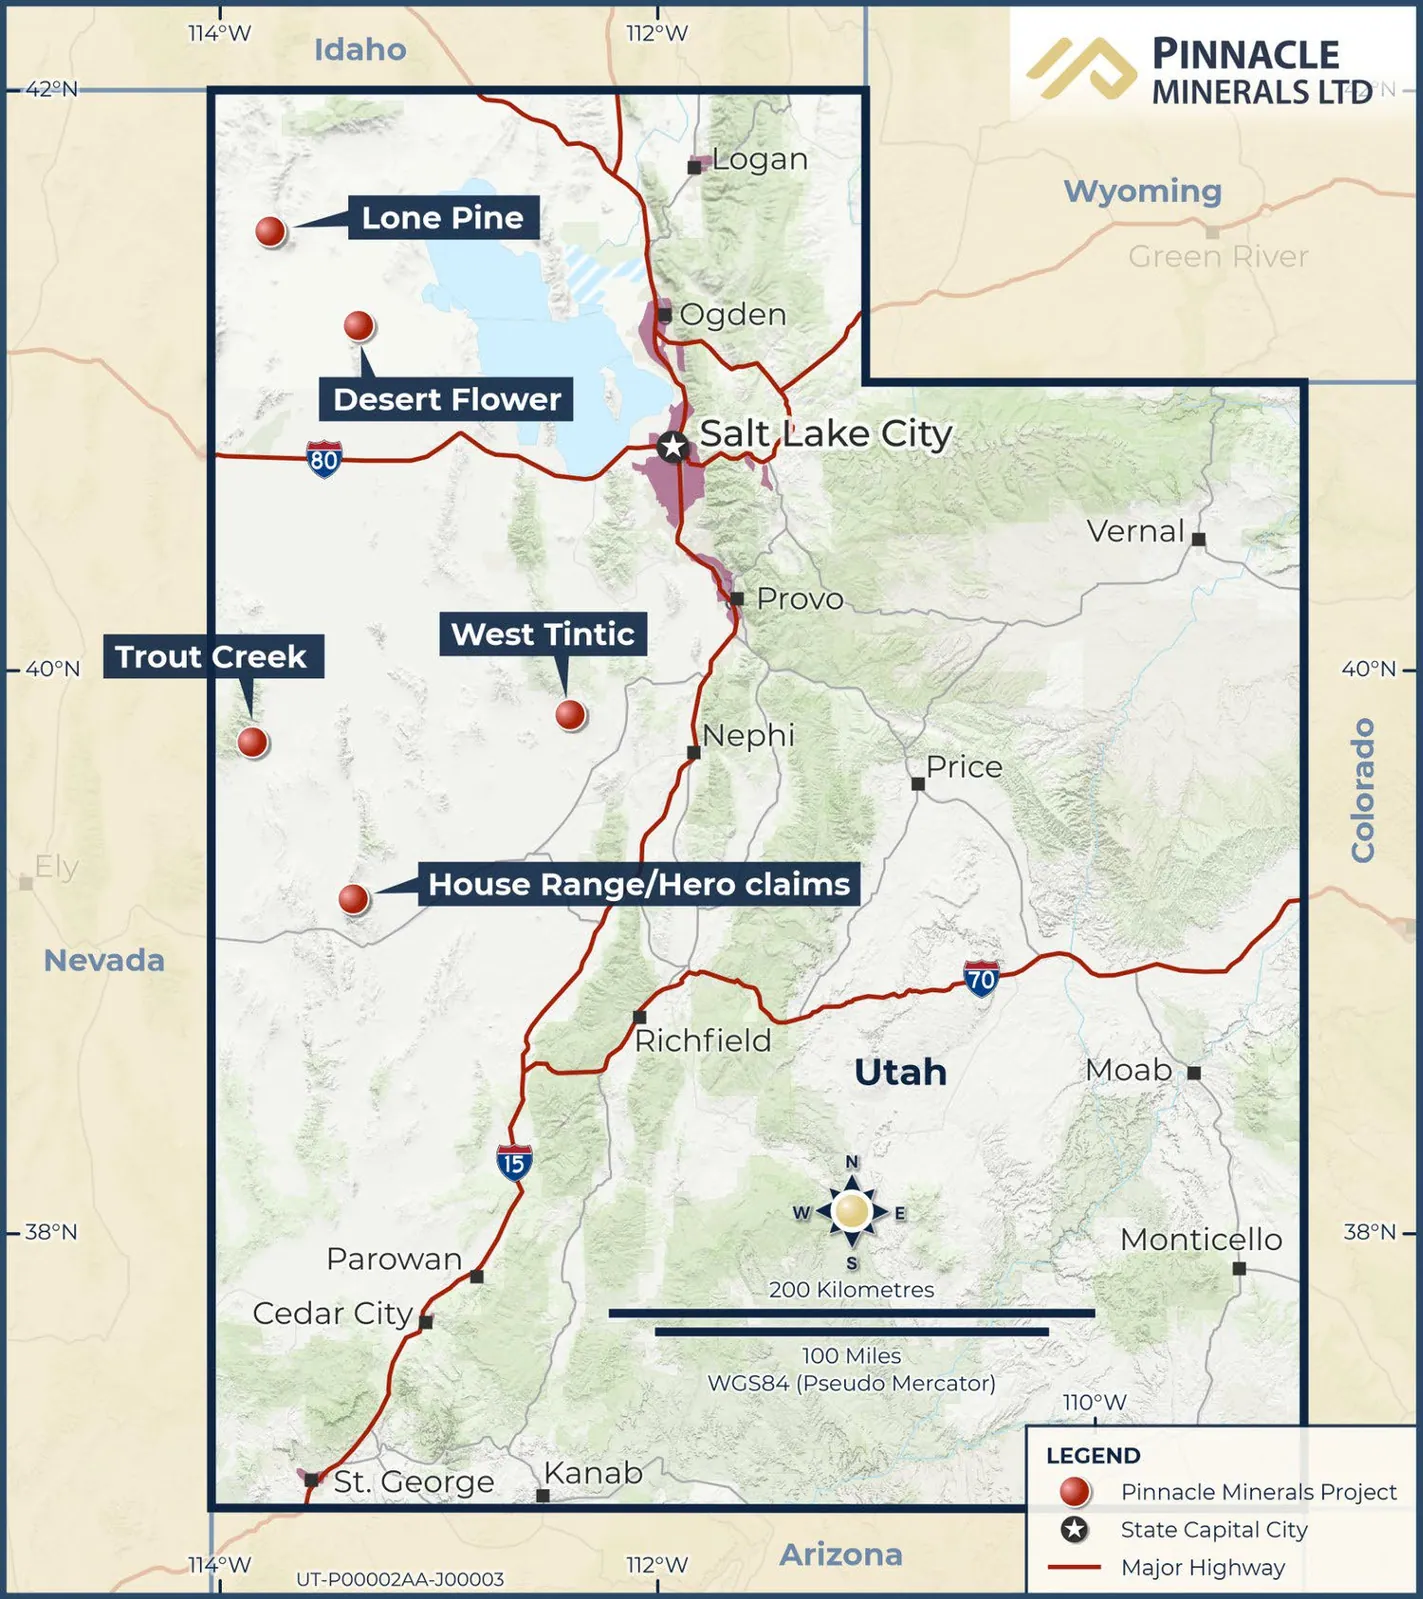
Hero, also known as the House Range project, is Pinnacle’s first priority. A September site visit identified extensive outcropping skarn, historical workings and mining equipment around the Notch Peak intrusive complex. The company plans geological mapping, validation sampling, scheelite surveys, portable XRF traverses and metallurgical testwork before attempting to define drill-ready targets.
Historical workings also underpin the Lone Pine, Desert Flower and Super W projects, where records report past tungsten production. But those figures are historical only: Pinnacle has not estimated a Mineral Resource or Ore Reserve for any project, and the company has not independently verified the production records.
May rock-chip sampling produced eye-catching results, including up to 12.25% tungsten, equivalent to 15.45% WO₃, at Lone Pine. Yet the company says the 25 samples were selective, several targeting visible scheelite-bearing veins and skarn, and cannot be used to infer grade, width or continuity. Two Trout Creek samples remain pending.
Title, Access and Processing Risks Remain Open
The Utah option carries obligations beyond the initial transaction. Keeping all five projects would require anniversary payments of up to US$2.912 million over three years, while APT must spend US$1 million on exploration within three years and bear claim maintenance costs. A 2% net smelter return royalty applies to each project acquired, with a buyback price of US$2 million for each 1%.
There are also project-level uncertainties. Lone Pine’s surface rights are privately owned and may require an access agreement before ground-disturbing work. Some Super W claims may rank behind third-party claims, prompting a title and claim-priority review before material expenditure. Pinnacle must also satisfy the remaining conditions under the Western Cobalt agreement and obtain the necessary regulatory and third-party approvals.
A non-binding memorandum with Nexus Metals contemplates potential toll treatment or offtake through the Del Sol facility in Nevada, as well as metallurgical work. It gives Pinnacle no right to use the facility, however, and any commercial arrangement depends on Nexus securing its own facility rights, technical results, approvals and definitive agreements. It is not a condition of the acquisition.
Board Transition Awaits Shareholder Approval
If the deal completes, Matthew O’Kane will become managing director and Blake Steele will join as a non-executive director. William Witham will step down as managing director and chief executive to become technical director, while Stephen Ross and Aharon Zaetz remain on the board. The APT vendors would collectively hold approximately 18.24% of Pinnacle’s shares after completion.
Shareholders are due to vote on 30 November, with completion targeted by 31 December 2026 and field exploration planned for January. The critical question is whether Pinnacle can convert an attractive tungsten narrative and a set of historical workings into verified, accessible and economically meaningful targets before the next round of funding obligations arrives.
Bottom Line?
The transaction gives Pinnacle a clear US tungsten platform, but shareholder approval, claim security, access rights and independent exploration results must arrive before the story moves beyond historical evidence.
Questions in the middle?
- Will shareholders approve the acquisition, placement and substantial package of performance securities at the 30 November AGM?
- Can Hero and the other Utah projects demonstrate continuous, drill-ready tungsten mineralisation beyond selective historical workings?
- How will Pinnacle fund the Western Cobalt anniversary payments and minimum exploration commitment if all five projects are retained?
Sources
1-
Pinnacle acquires rights to five Utah tungsten projects USA (opens in a new tab)Verified company source. Pinnacle Minerals Limited · 26 Oct 2026 · pinnacleminerals.com.au