Alara's Oman mine sets a copper sales record as funding question emerges

Alara Resources delivered its strongest quarterly copper sales since commercial operations began, while production remained above nameplate capacity at its Oman mine. Yet the company says the parent may need to raise about A$6 million in FY27 to cover a projected cash shortfall.
- 2,952 tonnes of contained copper sold in FY27 Q1
- 11,028 wet metric tonnes of concentrate produced
- A$134.4 million FY26 revenue and A$19.7 million net profit
- A$3.85 million entitlement offer completed without underwriting
- A$6 million FY27 equity raising anticipated
 Add us as a preferred source on Google
Record Copper Sales Meet Shipping Disruptions
Alara Resources Limited (ASX:AUQ) sold approximately 2,952 tonnes of contained copper in the September quarter, its strongest quarterly sales performance since the Al Wash-hi Majaza mine in Oman began commercial operations. The result was 42% above the previous quarterly record of 2,077 tonnes set in the June quarter.
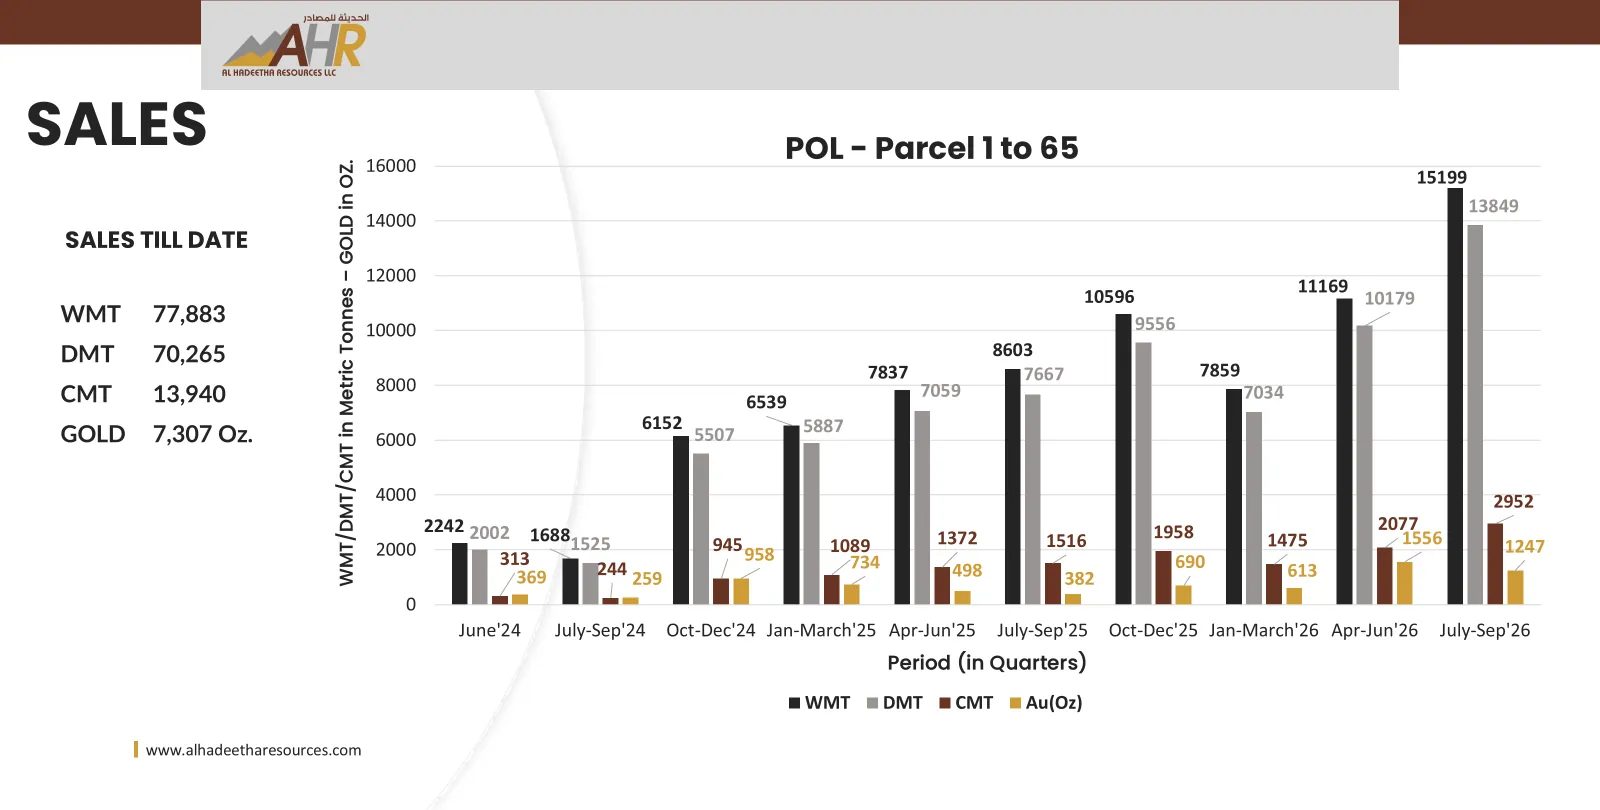
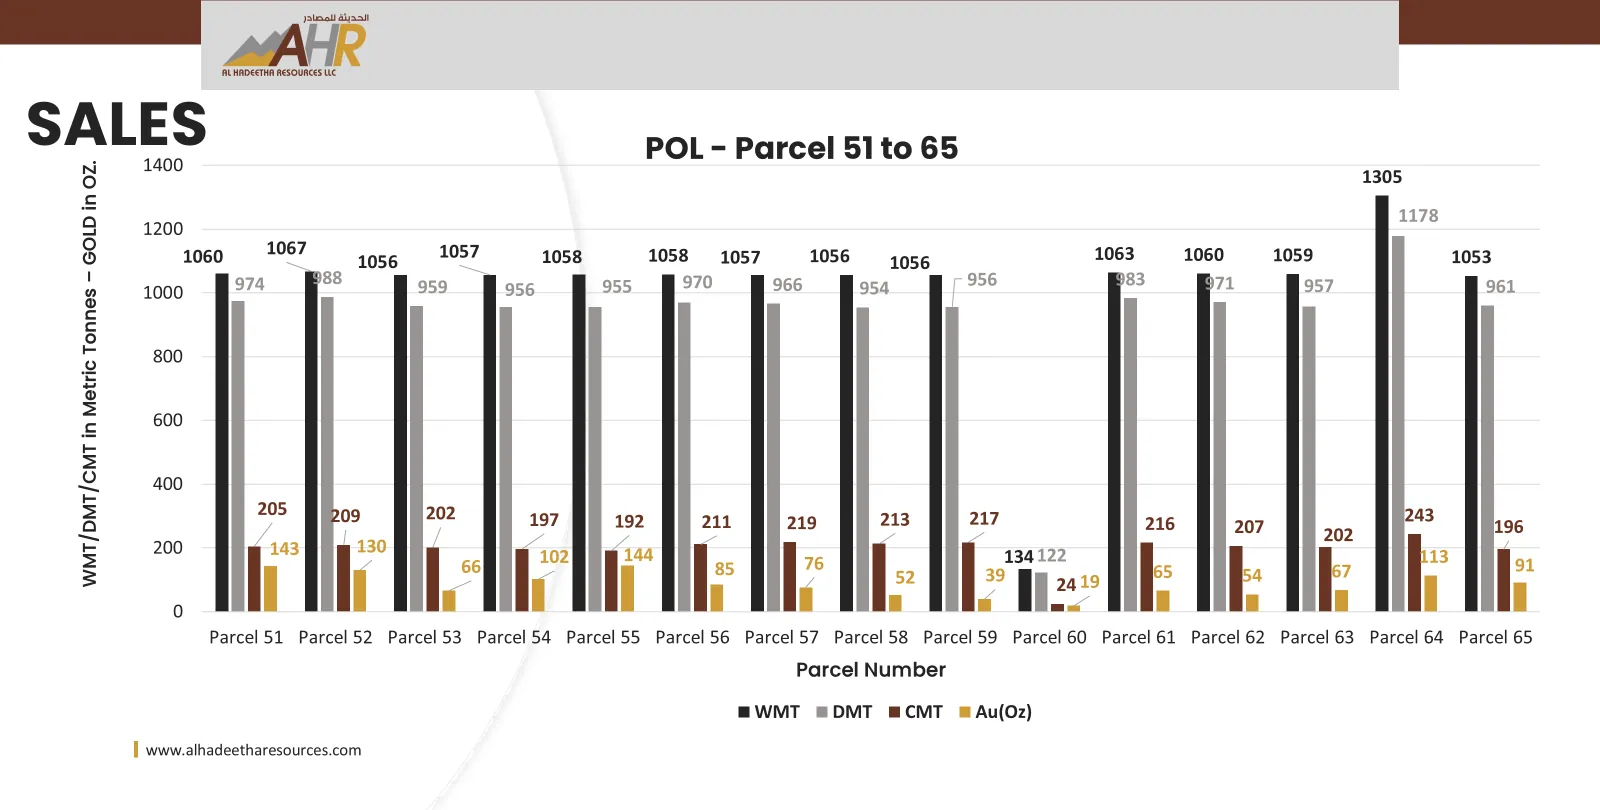
The mine produced 333,647 tonnes of run-of-mine ore and 11,028 wet metric tonnes of concentrate during FY27 Q1. Mill feed reached 285,141 tonnes, or 114% of the 249,000 tonne quarterly target. Fifteen concentrate parcels were dispatched from Sohar Port, containing approximately 2,952 tonnes of copper and 1,247 ounces of gold. The quarter's shipping performance was covered in the record copper quarter, which reported the 65th parcel leaving port at the end of September.
Operations were not frictionless. Regional geopolitical tensions, container shortages and disruption to port connections delayed shipments and marginally extended the timing of concentrate revenue inflows. Congestion at Sohar in August also delayed vessel loading, although production, storage and dispatch readiness remained stable. A scheduled processing plant shutdown for maintenance is planned for the next quarter.
Profitability Has Arrived, Funding Still Matters
Alara's FY26 annual report showed revenue of A$134.4 million, up from A$55.1 million, and net profit of A$19.7 million compared with a A$19.0 million loss the previous year. The filing describes this as a profitability inflection, following the Oman operation's transition into a more substantial production and sales phase. The FY26 profit turnaround had already highlighted the sharp improvement, but the quarterly filing places it alongside the mine's latest operating performance.
The more complicated balance-sheet detail sits below the headline numbers. Alara finished the quarter with consolidated cash of A$42.3 million and generated A$24.7 million in net operating cash flow. However, most of the consolidated cash flows through the 51%-owned Al Hadeetha Resources vehicle and is not freely available to Alara as a standalone parent. Directors' cash-flow forecasts point to a parent-company shortfall of about A$2.8 million over the next 12 months, with an equity raising of approximately A$6 million anticipated in FY27.
The company completed a separate entitlement offer during the quarter, issuing 120.46 million shares at A$0.032 each and raising approximately A$3.85 million before costs. Applications of roughly A$4.95 million exceeded the offer size, but the disclosed future funding requirement means the successful raising is not necessarily the last capital event investors will need to consider.
Block 22B Exploration Moves From Surveying to Target Selection
Alara completed a 6,132 line-kilometre HeliTEM airborne electromagnetic and magnetic survey over the 1,448 square kilometre Block 22B concession in Oman. Remote sensing, mapping and rock-chip sampling identified 12 prospect areas, with field work across five priority zones recording hydrothermal alteration, veining and surface copper indicators.
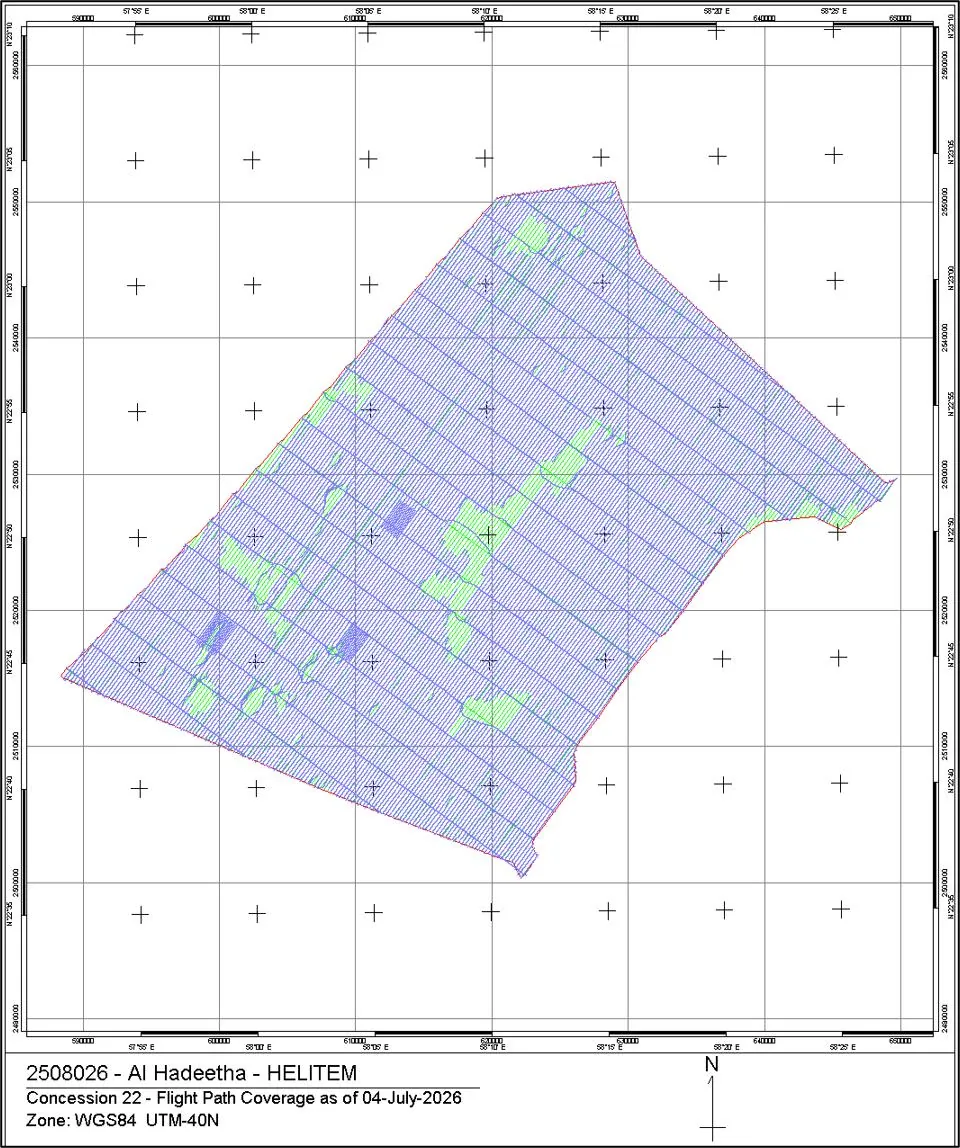
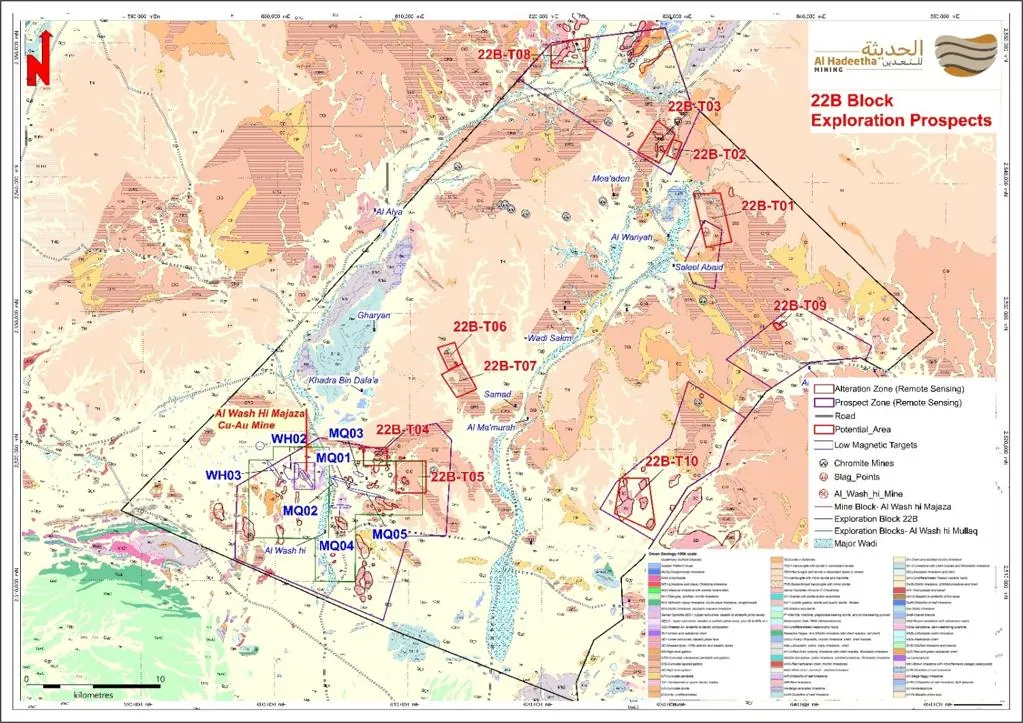
Those observations remain early-stage exploration evidence, not a resource or economic assessment. Laboratory assays are pending, and the company explicitly cautions that visual malachite, sulphides, gossans and alteration cannot substitute for laboratory analysis. Interpretation of the airborne data is expected in FY27 Q2 and is intended to rank anomalies for further geological, geochemical and geophysical work.
Appeal and Mine Expansion Remain Key Watchpoints
An appeal by residents against permits, approvals and licences associated with Al Wash-hi Majaza is scheduled for hearing in November 2026. The first instance court dismissed the substantive claims and awarded costs against the plaintiffs, but Alara says it cannot predict the outcome or timing of the appeal. The project continues to operate under its existing approvals.
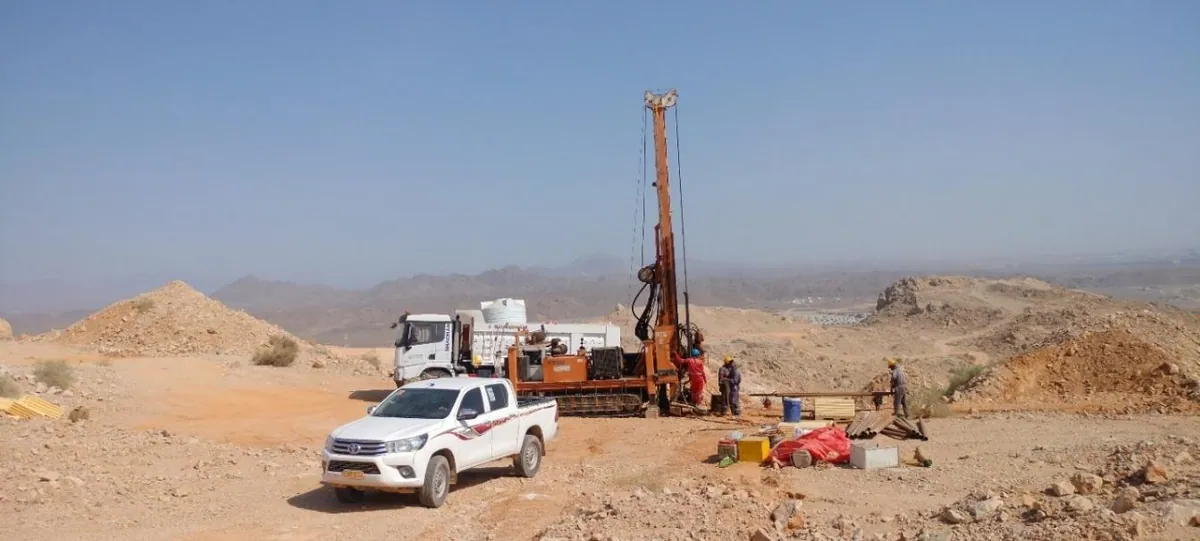
Meanwhile, 680.5 metres of extension drilling was completed across three holes near the mine, with assays still being processed. The drilling sits outside the pit shell underpinning the current Mineral Resource and Ore Reserve estimates and is not expected to materially affect those estimates. The next quarter therefore combines a strong operational test, new exploration interpretation, a legal hearing and a likely funding decision. The central question is whether cash generated inside the operating joint venture can support Alara's wider exploration ambitions without repeatedly returning the parent to equity markets.
Bottom Line?
Alara has demonstrated operating momentum, but the next test is whether mine cash can fund growth while the parent addresses its projected A$2.8 million shortfall and expected A$6 million capital requirement.
Questions in the middle?
- How much of the anticipated A$6 million raising will be required, and on what terms?
- Will Sohar Port disruption or the scheduled plant shutdown affect FY27 Q2 shipments and cash receipts?
- Can Block 22B's pending assays and HeliTEM interpretation produce drill targets with economic significance?
Sources
1-
Quarterly Activities/Appendix 5B Cash Flow Report (opens in a new tab)Verified company source. Alara Resources Limited · 27 Oct 2026 · alararesources.com