IVE’s margin gains turn a softer FY26 into a higher dividend

5 min read
9:38am on Tuesday 27th of October, 2026 AEDT ~9am, 27th Oct, 26
IVE Group’s FY26 revenue slipped 1.8%, but stronger margins lifted underlying pre-AASB 16 NPAT by 3.0% to A$52.5 million and supported a higher final dividend. The marketing and communications group expects underlying pre-AASB 16 profit to be broadly stable in FY27 as new capacity and acquisitions begin to contribute.
- Underlying pre-AASB 16 NPAT rose 3.0% to A$52.5 million
- Revenue fell 1.8% to A$937.4 million while EBITDA margin reached 15.6%
- Fully franked final dividend increased to 9.0 cents per share
- Net debt rose to A$173.2 million after acquisitions and site investment
- FY27 underlying pre-AASB 16 NPAT expected to be broadly stable
 Add us as a preferred source on Google
Margin expansion offsets softer revenue
IVE Group Limited (ASX:IGL) finished FY26 with a familiar tension: less revenue, but more profit underneath. Revenue fell 1.8% to A$937.4 million, while underlying EBITDA increased 6.6% to A$145.8 million as the material gross profit margin widened by 2.1 percentage points to 51.4%.
On the company’s preferred pre-AASB 16 basis, underlying NPAT rose 3.0% to A$52.5 million and earnings per share increased 3.7% to 34.2 cents. The comparison is not an audited or reviewed IFRS measure, and excludes certain non-operating items, so it should not be confused with statutory profit. IFRS NPAT fell 19.8% to A$37.4 million after A$14.7 million of restructuring costs, largely linked to the Dandenong South and Kemps Creek relocations.
The result broadly matches the earnings picture outlined in IVE’s FY26 margin gains, where catalogue softness was offset by stronger operating performance in areas including CX and Data, merchandising and third-party logistics.
Dividend rises as cash funds expansion
The board declared a fully franked final dividend of 9.0 cents per share, taking the full-year payout to 18.5 cents, up from 18.0 cents in FY25. The pre-AASB 16 payout ratio was 53.8%, around the lower end of the 55% to 65% range the company intends to use for FY27.
IVE generated A$136.4 million of underlying operating cash flow, equivalent to 93.6% of underlying EBITDA. Yet investment and acquisitions pushed net debt to A$173.2 million from A$114.4 million a year earlier, placing leverage at 1.54 times pre-AASB 16 EBITDA. Management said the balance sheet remains within its internal benchmark, with A$109.0 million of undrawn debt capacity at year-end.
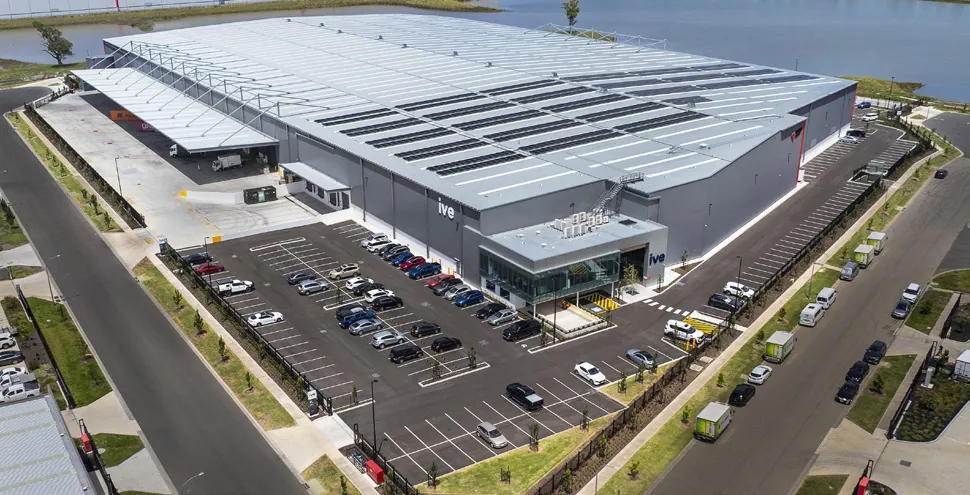
The capital was directed towards three acquisitions, a new packaging plant, the Kemps Creek supersite and the Dandenong South logistics facility. The company also cancelled 2.3 million shares during the year through its on-market buyback, taking total cancellations since March 2025 to 3.02 million shares.
New sites and acquisitions set the FY27 workload
IVE completed the acquisitions of Budget Mail Services, Impressu and Daily Press for total consideration of up to A$49.5 million. Together, the businesses are expected to contribute around A$58 million of annual revenue and A$12 million of EBITDA including synergies, although the timing and delivery of those benefits remain execution matters rather than accounting certainties.
The Daily Press deal, previously announced as a digital and creative expansion, is now being integrated into IVE’s Creative, Content and Integrated Solutions division. The acquisition added social, performance marketing and technology capabilities, while Impressu came with a six-year plus two-year marketing services agreement with Domino’s Pizza Enterprises.
Logistics capacity has also expanded materially. The Dandenong South facility lifted national 3PL capacity and was already at 85% capacity by year-end, helped by new business after the collapse of competitor Packcentre. At Kemps Creek, a 42,000-square-metre supersite consolidated five business units and added a dedicated NSW packaging plant, with management expecting operating efficiencies and additional earnings capacity in FY27.
Lasoo growth remains ahead of profitability
Lasoo continued to grow rapidly but remained loss-making. Gross transaction value rose 42% to A$25 million, unique users increased to more than 5.2 million and repeat customer GTV rose 76%. The platform also moved from Marketplacer to IVE’s proprietary Lasoo Connect technology during the year.
Lasoo recorded an after-tax loss of A$4.6 million in FY26. IVE expects that loss to improve to around A$3.5 million in FY27 and maintains its target for break-even in FY28. The company’s longer-term ambition is for Lasoo to reach around A$150 million of GTV by FY30, which would imply EBITDA of A$4.5 million and NPAT of A$3 million.
Stable FY27 guidance brings execution into focus
IVE expects underlying pre-AASB 16 NPAT to be broadly stable in FY27, subject to economic conditions and any strategic initiatives. Post-AASB 16 underlying NPAT is expected to decline because of an estimated A$6 million adverse non-cash lease impact from the new Kemps Creek and Dandenong South facilities, while IFRS NPAT is expected to increase materially as non-operating costs fall.
Capital expenditure is forecast to fall to about A$26 million after the major site and packaging investments. Management also expects net debt to be below 1.5 times pre-AASB 16 EBITDA at 30 June 2027. The immediate test is whether the newer assets and acquisitions can turn margin resilience into genuine revenue growth, rather than merely cushioning continued weakness in traditional catalogue volumes.
Bottom Line?
IVE has bought capacity, capability and a higher dividend, but FY27’s broadly stable profit guidance leaves limited room for execution missteps as leverage rises and new sites ramp up.
Questions in the middle?
- Can the Kemps Creek packaging plant and Dandenong South 3PL facility convert capacity into sustained revenue growth in FY27?
- Will the Daily Press, Impressu and Budget Mail Services acquisitions deliver the targeted earnings contribution and synergies?
- Can Lasoo reduce its operating loss on schedule while continuing to grow GTV and user engagement?
Sources
1-
2026 Annual Report (opens in a new tab)Verified company source. Ive Group Limited · 27 Oct 2026 · investors.ivegroup.com.au