A$315.8 million EBITDA puts Kelsian on firmer FY27 footing

Kelsian Group has entered FY27 after a record financial year, the $149.9 million sale of its Tourism Portfolio and a sharp reduction in leverage. But the transport operator is also awaiting an independent review into a fatal June bus incident as it pursues fresh international growth.
- FY26 revenue rose 8.8% to A$2.403 billion
- Underlying EBITDA increased 10.8% to A$315.8 million
- Tourism Portfolio sale delivered A$149.9 million in gross cash proceeds
- FY27 underlying EBITDA guidance reiterated at A$295 million to A$310 million
- Independent review underway after a passenger died following a June bus incident
 Add us as a preferred source on Google
Record earnings meet a more focused portfolio
Kelsian Group Limited (ASX:KLS) has put a record FY26 behind it with a simpler balance sheet and a narrower strategic brief: build a global commuter and contracted transport operator, rather than remain as exposed to discretionary tourism. Revenue rose 8.8% to A$2.403 billion, while underlying EBITDA increased 10.8% to A$315.8 million.
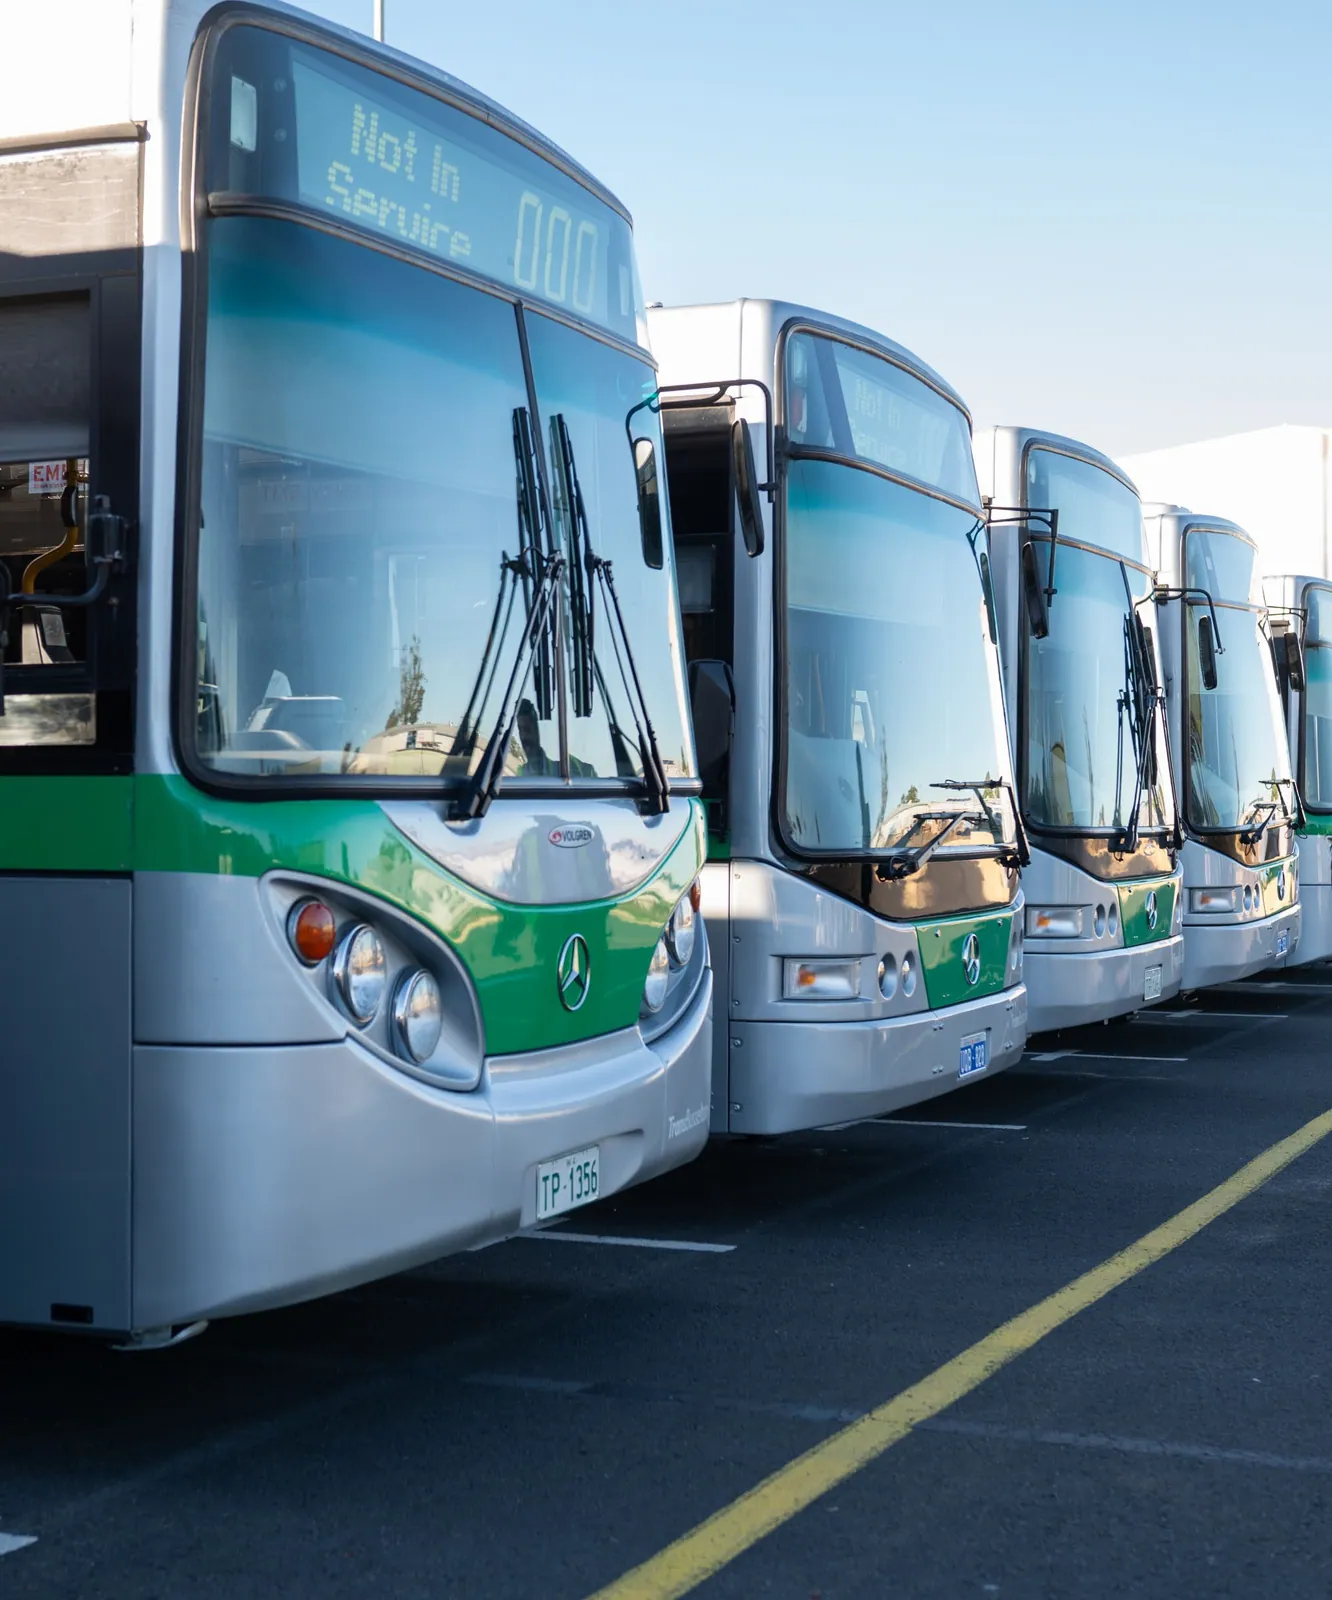
Underlying EBIT climbed 14.5% to A$155.7 million and underlying net profit after tax before amortisation rose 17.2% to A$111.1 million. Net operating cash flow reached A$220.1 million, up 7.3%, while leverage fell to 2.46 times at 30 June, within the company’s target range of two to 2.5 times. Statutory net profit after tax increased 16.6% to A$63.5 million, after one-off costs tied to acquisitions, the portfolio sale and a new finance system.
Tourism sale leaves Kelsian with more financial room
The portfolio reshaping is now complete. Kelsian received gross cash proceeds of A$149.9 million from the sale of its Tourism Portfolio to Journey Beyond on 30 September, a transaction covered in the completed Tourism Portfolio sale earlier this month. The Rottnest Island ferry operation was retained, while the remaining business is being positioned around bus, motorcoach and contracted marine services.
Management said the divestment had reduced average annual net sustaining capital expenditure from about A$85 million to A$73 million and left pro forma leverage at approximately 2.0 times as at 30 September. That gives Kelsian more flexibility, although the company’s capital framework puts conditions around its use: growth investments must be earnings-per-share accretive and deliver returns above its pre-tax cost of capital within three years.
FY27 guidance holds as new contracts come online
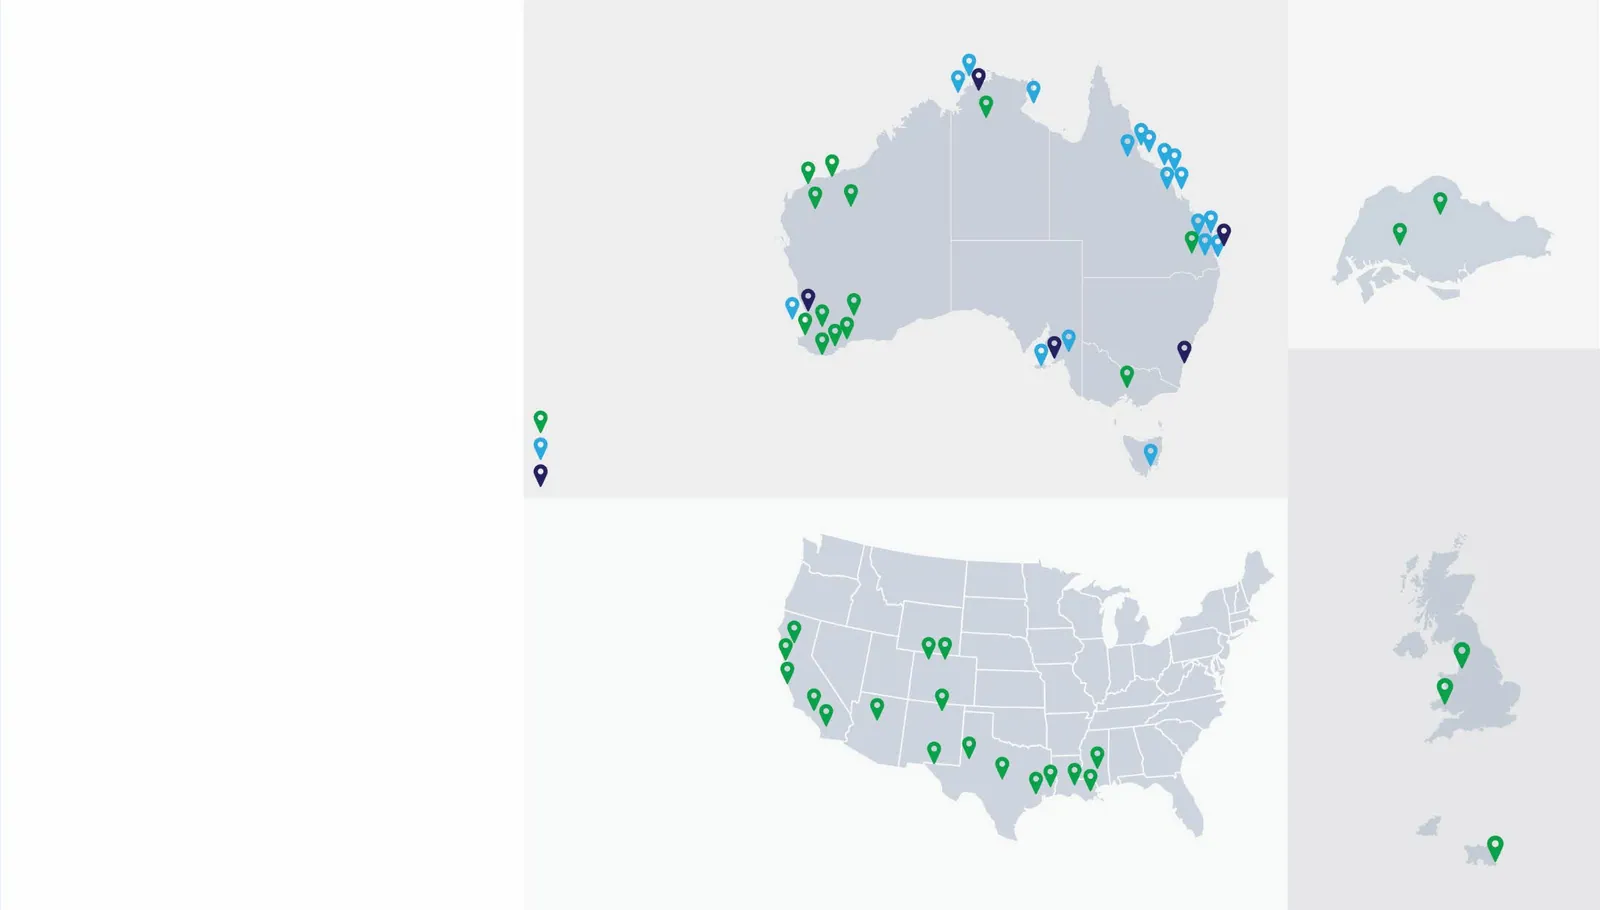
First-quarter trading was described as in line with expectations, prompting Kelsian to reiterate underlying EBITDA guidance of A$295 million to A$310 million for FY27, assuming no significant deterioration in the operating environment. The range excludes the Tourism Portfolio for the full year and includes approximately A$3 million of stranded costs.
The growth pipeline spans several markets. Liverpool bus contracts are being mobilised, Kelsian has been nominated preferred bidder for contracts in West Yorkshire, and the company expects its Auckland ferry contracts to begin in July 2027. The planned Belaire Ferries acquisition would establish Kelsian’s first operating platform in New Zealand, following the Auckland ferry contracts announced in July. In the United States, the company reported continued momentum in industrial employee transport, including a new data-centre contract in Texas.
Kangaroo Island vessels begin phased service
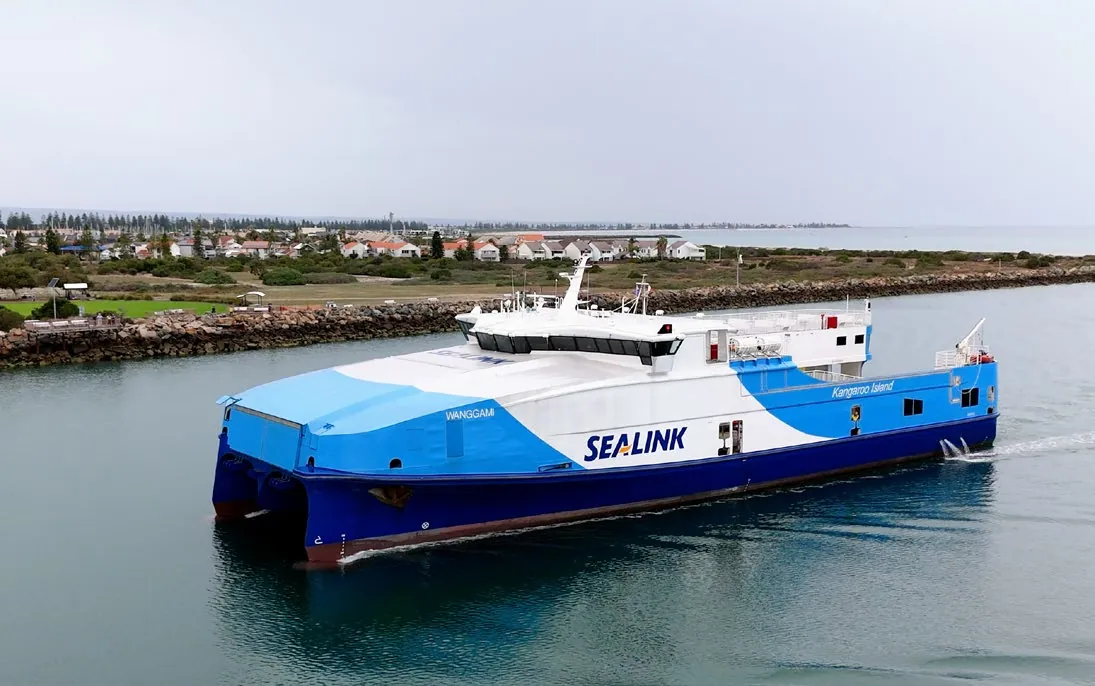
Kelsian also reached a long-delayed operational milestone on Kangaroo Island. The first new vessel, Wanggami, commenced full passenger services at the AGM, while its identical sister vessel, Ruwi, is expected to arrive in Australia by mid-November before preparations and approvals for entry into service.
The vessels are 10 metres longer and two metres wider than those they replace, providing about 65% more vehicle lane length per sailing. Kelsian said upgraded shore infrastructure should support faster turnarounds and more daily sailings, but the immediate task remains completing the transition safely and reliably after construction and delivery delays.
Safety review remains an unresolved shareholder issue
The upbeat financial narrative is tempered by a serious safety matter. A passenger died in June following an incident involving Kelsian’s Australian bus operations, and an independent review is underway. The Board has withheld the safety component of short-term incentive awards pending the review’s outcome.
Chair Fiona Hele said the company had improved its lost-time and total recordable injury frequency measures during FY26, while acknowledging that transport and marine operations remain inherently high-risk. CEO Graeme Legh has joined the Board, adding his operational experience after 19 months leading the group through the record result and Tourism Portfolio divestment. The review’s findings, and whether they prompt changes beyond remuneration, now sit alongside earnings delivery as a material test for the new financial year.
Bottom Line?
Kelsian has created financial room for growth, but the FY27 story will depend on converting its contract pipeline while resolving the outstanding safety review.
Questions in the middle?
- Can Kelsian deliver the A$295 million to A$310 million FY27 EBITDA target after absorbing stranded costs and new mobilisation demands?
- How will management deploy the Tourism Portfolio proceeds while meeting its return-on-invested-capital hurdles?
- Will the independent review into the June bus fatality lead to operational or executive accountability changes?
Sources
1-
2026 AGM Chair and CEO Address (opens in a new tab)Official market announcement. Kelsian Group Limited · 27 Oct 2026 · kelsian.com