NRW’s Fredon bet begins paying off as four divisions deliver record earnings

5 min read
11:12am on Tuesday 27th of October, 2026 AEDT ~11am, 27th Oct, 26
NRW Holdings delivered record FY26 revenue and earnings after folding Fredon into a new EMIT division, while debt-funded expansion lifted leverage. The company enters FY27 with A$7.5 billion of secured work, a larger banking facility and a sharper test of whether diversification can keep converting into cash.
- Revenue rose 31.4% to A$4.293 billion
- Underlying EBITA increased 38.8% to A$288.6 million
- Fredon contributed A$684.3 million in nine months
- Net debt increased to A$265.8 million after the acquisition
- Final fully franked dividend lifted to 14.5 cents per share
 Add us as a preferred source on Google
Record earnings give NRW’s Fredon strategy an early scorecard
NRW Holdings Limited (ASX:NWH) has turned its Fredon acquisition into a fourth operating segment and a sizeable new source of revenue, reporting a 31.4% jump in FY26 revenue to A$4.293 billion. Underlying EBITA rose 38.8% to A$288.6 million, underlying NPAT increased 43.6% to A$182.7 million and the group’s margin improved to 6.7% from 6.4%.
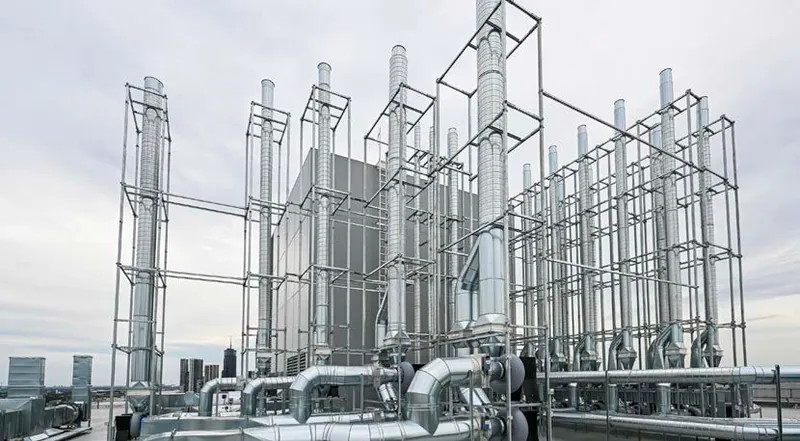
Fredon contributed A$684.3 million of revenue and A$36.1 million of underlying EBITA during its first nine months inside NRW. The new EMIT division, covering electrical, mechanical, infrastructure, technology and maintenance services, gives the group exposure to data centres, health, defence, airports and energy infrastructure alongside its established civil, mining and minerals businesses.
EMIT adds data centre and infrastructure momentum
The annual report points to four data centre contracts awarded in December 2025 with a combined value of about A$150 million, alongside further awards across data centre, healthcare, education and student accommodation projects. Fredon’s Stack data centre package was reported separately as an approximately A$115 million first-stage Melbourne award, with a broader package still subject to preferred-contractor status.
EMIT also secured an electrical works package on a major Commonwealth infrastructure project in Northern Australia valued at about A$110 million, with completion planned for mid-2028. Its secured work in hand stood at A$1.4 billion, while the broader group reported A$7.5 billion of work in hand, A$11.1 billion of active tenders and a pipeline of A$29.1 billion expected to come to market within 12 months.
Mining and MET remain the profit centre
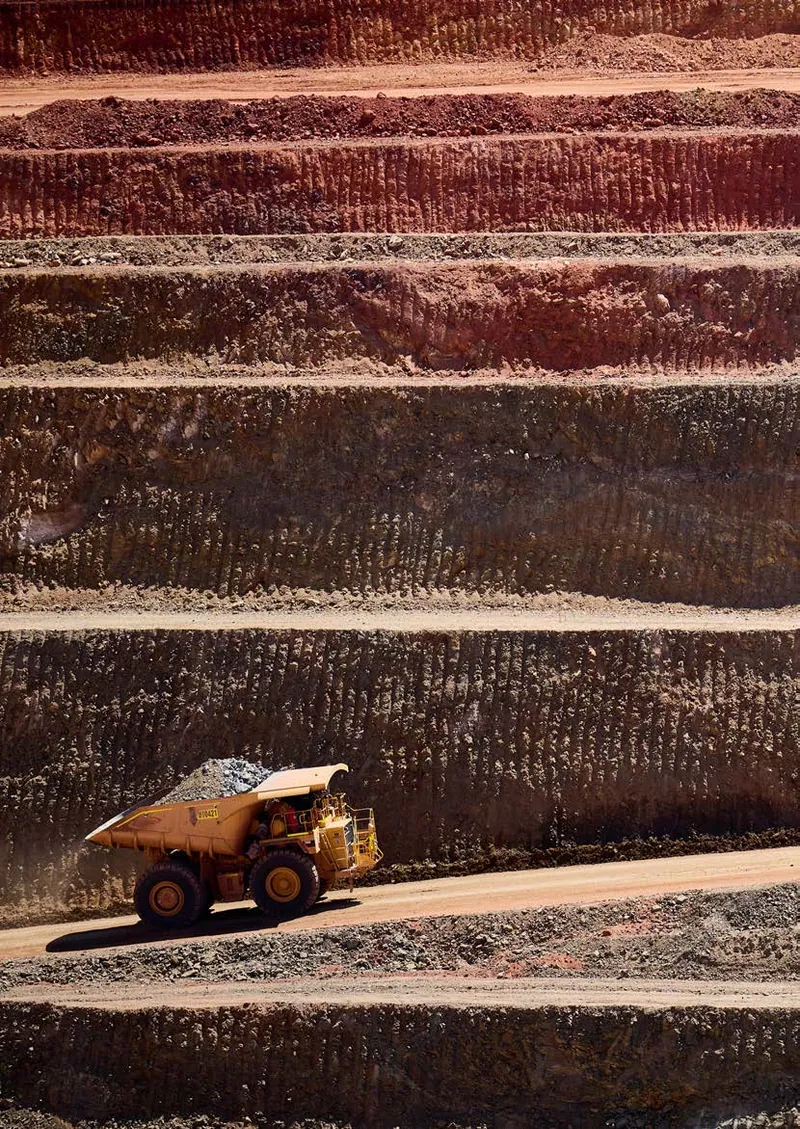
Mining generated A$1.539 billion of revenue and A$139.9 million of underlying EBITA, up 15.6%, helped by higher fleet utilisation and production volumes. The portfolio includes the Stanwell Meandu mining services agreement, valued at about A$750 million over five and a half years, and the Southern Middle Back Ranges equipment hire contract worth about A$150 million over three years.
NRW’s Karara operation also remains part of the mining base, following the Karara contract extension reported in August as a five-year, approximately A$960 million extension. MET was the other major earnings contributor, with revenue up 35.1% to A$1.259 billion and underlying EBITA up 40.5% to A$96 million, driven by Primero, DIAB, RCR and work on Northern Star’s KCGM Fimiston Growth Project.
Cash is stronger, but Fredon was funded with debt
NRW finished FY26 with A$319.7 million of cash and operating cash conversion of 93.8%. That strength sits alongside a materially heavier balance sheet: financial debt rose to A$499.6 million, net debt increased to A$265.8 million from A$145.4 million, and leverage excluding leases rose to 0.37 times from 0.25 times after the Fredon purchase was funded through revolving credit facilities.
On 31 July, after year end, NRW expanded committed banking facilities from A$400 million to A$700 million and bank guarantee facilities from A$90 million to A$125 million. The refinancing provides additional liquidity, but it also leaves the group with variable-rate debt and a larger funding base to manage as it pursues further growth.
FY27 starts with a full order book and execution risk
The board declared a fully franked final dividend of 14.5 cents per share, taking FY26 dividends to 23 cents per share. Safety performance improved, with TRIFR falling to 4.12 from 6.05, while the workforce expanded to more than 14,000 people in July 2026.
NRW’s own risk disclosures point to the less photogenic side of the expansion: project delivery, labour availability, counterparty exposure, tender accuracy, customer concentration and the possibility that costs cannot be passed through under contract terms. The FY27 remuneration report references board-approved underlying EBITA guidance of A$320 million to A$330 million, making delivery across the enlarged group the next practical test of the strategy. The question is no longer whether Fredon can add scale; it is whether that scale can maintain margins while debt, workforce demands and project complexity all rise together.
Bottom Line?
NRW has entered FY27 with stronger earnings visibility and broader capabilities, but the next year must show that Fredon’s revenue contribution can translate into durable margins and cash generation without allowing leverage to drift higher.
Questions in the middle?
- Can EMIT sustain the 5.3% underlying EBITA margin as Fredon contributes a full year of earnings?
- How much of the A$7.5 billion order book will convert into cash at acceptable project margins?
- Will the expanded banking capacity support disciplined growth, or encourage further debt-funded acquisitions before leverage falls?
Sources
1-
Annual Report to shareholders (opens in a new tab)Official market announcement. Nrw Holdings Limited · 27 Oct 2026 · nrw.com.au