OncoSil’s regulatory wins point to a bigger commercial test

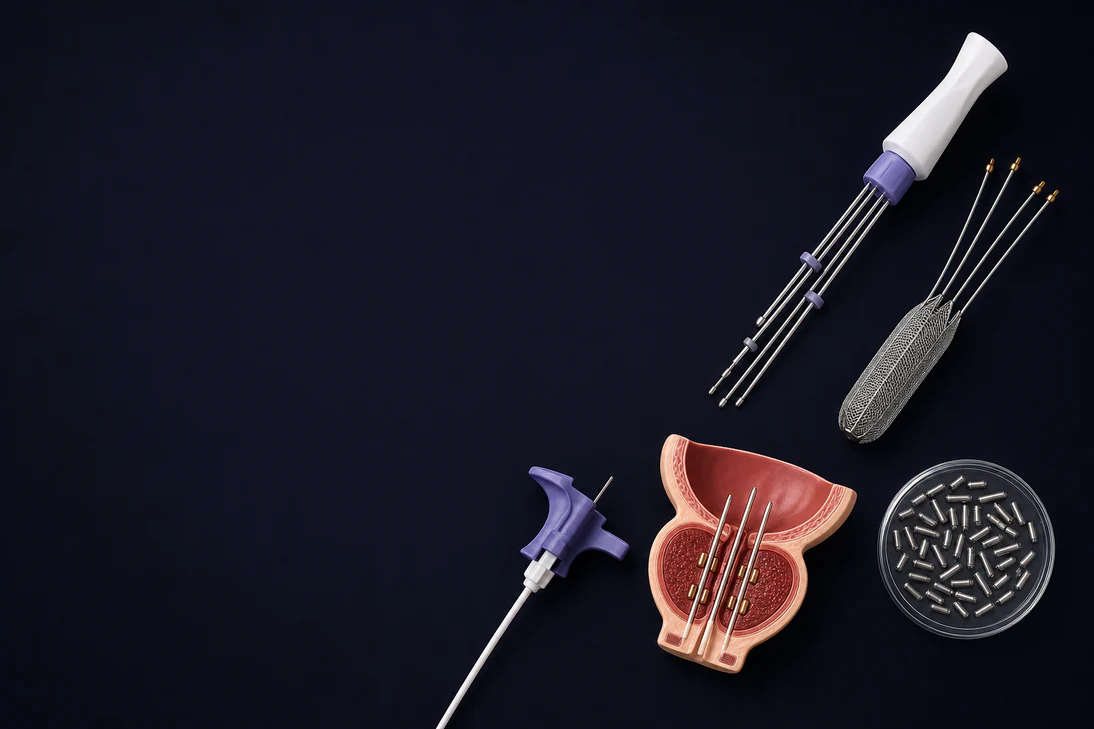
OncoSil Medical delivered sharper commercial growth and a string of regulatory milestones in FY26, but the oncology device company remains heavily loss-making and dependent on future sales or fresh capital. Revenue rose 44% to $1.68 million while operating cash outflow reached $10.47 million.
- Revenue increased 44% to $1.68 million
- Net loss narrowed to $10.86 million
- Cash balance stood at $6.48 million after $13.46 million of gross equity funding
- TRIPP-FFX met both co-primary endpoints, but was not designed for formal arm-to-arm comparison
- Auditor flagged material uncertainty over going concern
 Add us as a preferred source on Google
Commercial growth improves, but funding remains central
OncoSil Medical Limited (ASX:OSL) has reached the point where its regulatory progress is beginning to show up in sales, even as its cash demands remain substantial. Revenue from the OncoSil device rose 44% to $1.685 million in FY26, unit sales increased 53% and customer receipts climbed 179% to $2.115 million.
That progress did not yet make the business self-funding. OncoSil reported a net loss of $10.86 million, compared with $15.10 million a year earlier, and used $10.47 million in operating cash. It finished June with $6.48 million in cash after raising $13.46 million before costs during the year through placements and share purchase plans. The directors and auditor said a material uncertainty exists over going concern, with the company reliant on future sales and/or additional equity funding, although the board concluded the business could continue on a going-concern basis.
The balance sheet also carries a less visible commercial milestone: OncoSil had reached US$2.9 million of cumulative sales towards a US$5 million threshold under its pSiMedica licence at year end. Reaching that threshold would trigger a potential milestone payment, although the timing and occurrence of the payment depend on future sales.
Clinical evidence supports a wider treatment label
The strongest clinical development was TRIPP-FFX, which met both co-primary endpoints in patients with unresectable locally advanced pancreatic cancer. The study reported an 82.2% local disease control rate at 16 weeks and median overall survival of 18.3 months for patients receiving OncoSil alongside FOLFIRINOX.
The qualification matters. TRIPP-FFX was randomised but non-comparative and was not powered for a formal statistical comparison between treatment arms; the control arm served primarily as a benchmark against historical outcomes. Even so, the result gives OncoSil a basis for seeking a label expansion into FOLFIRINOX, alongside its existing gemcitabine-based chemotherapy pathway. The company expects to submit a European and UK change notification in late 1H FY27.
The findings build on the company’s earlier TRIPP-FFX trial results, which reported that the study had met its co-primary endpoints and could support broader regulatory use. Separately, the OSPREY real-world registry reported median overall survival from diagnosis of 20.6 months and 22.0 months in two first-line cohorts, although enrolment and follow-up remain ongoing and the figures come from registry populations rather than a controlled comparison.
Regulatory approvals open Australia and the United States
OncoSil secured Therapeutic Goods Administration approval in May for use in unresectable locally advanced pancreatic cancer with gemcitabine-based chemotherapy, opening its home market for a planned launch in the first half of calendar 2027. The company also reported that the US Food and Drug Administration approved its Humanitarian Device Exemption for distal cholangiocarcinoma in August, after the reporting date.
The FDA decision is a separate indication from OncoSil’s pancreatic cancer program, but it establishes the company’s first US regulatory pathway for the device. The approval was the subject of FDA HDE approval coverage in August, when the device was reported as approved for the rare bile duct cancer indication. Commercial launch plans remain prospective and will be shaped by post-approval requirements and the company’s ability to build treatment-centre adoption.
In Europe, Germany remains the pivotal reimbursement test. OncoSil says its G-BA-sponsored study is expected to commence in the first half of FY27, with the proposed trial targeting about 280 patients across roughly 40 centres. The company estimates study revenue of about $5.6 million and additional commercial revenue of about $6.5 million, but those figures are opportunity estimates rather than recognised sales.
Manufacturing scale-up and the cash runway test
Manufacturing is another potential source of operating leverage. Validation activities at the Macquarie Park facility were completed in July 2026, but production of commercial doses still depends on inspection outcomes and regulatory approval. The facility is intended to improve supply control and reduce cost of goods sold as volumes increase. The company’s Sydney manufacturing facility had also cleared an ISO 13485 quality-management hurdle, although further approval remained necessary before production could begin.
Management has identified annualised cost savings of $3.4 million to $3.9 million from FY27, while research and development cash outflows are expected to decline as TRIPP-FFX and PANCOSIL move through close-out. Those savings could improve the cash profile, but they do not remove the central execution question: whether Australian and US launches, European reimbursement and new label opportunities can convert regulatory progress into sales quickly enough to reduce reliance on capital markets.
Bottom Line?
OncoSil enters FY27 with stronger evidence and more regulatory access, but the next test is converting those approvals into recurring cash receipts before the runway tightens.
Questions in the middle?
- How quickly will Australian and US launches translate into paid doses and customer receipts?
- Will the FOLFIRINOX and percutaneous-delivery submissions expand adoption without requiring another major funding round?
- Can the German G-BA study unlock reimbursement before operating cash outflows force further equity funding?
Sources
1-
Annual Report (Typeset) (opens in a new tab)Verified company source. Oncosil Medical Ltd · 27 Oct 2026 · investors.oncosil.com