West African Resources builds cash after another record gold quarter

West African Resources delivered record quarterly gold production of 127,950 ounces and generated A$458.2 million in operating cash flow, lifting cash to A$1.195 billion. The strong quarter keeps 2026 production guidance within reach, while Kiaka’s explosives constraint and a pending ownership transaction remain key execution issues.
- Record Q3 production of 127,950 ounces at US$1,570/oz AISC
- A$458.2 million operating cash flow and A$1.195 billion cash balance
- Kiaka production rose 13% while Sanbrado output fell 10% quarter-on-quarter
- A$0.20 per share special dividend paid after quarter-end
- SOPAMIB’s proposed 25% Kiaka stake acquisition remains due for completion in Q4
 Add us as a preferred source on Google
Record production strengthens WAF’s cash position
West African Resources Limited (ASX:WAF) has converted another record production quarter into a substantial cash buffer, reporting A$458.2 million of operating cash flow and A$1.195 billion in cash at 30 September 2026. The Burkina Faso-focused gold producer also held about A$217 million of unsold bullion, giving it considerable liquidity before accounting for debt and other obligations.
Group production reached 127,950 ounces at an all-in sustaining cost of US$1,570 per ounce, while 135,245 ounces were sold at an average realised price of US$4,240 per ounce. The result keeps WAF’s 2026 output of 430,000 to 490,000 ounces at an AISC below US$1,900 per ounce within reach: nine-month production stands at 360,857 ounces and year-to-date AISC is US$1,725 per ounce.
The quarter also marked a sharp improvement in the company’s notional net cash position, which rose to US$710.2 million from US$490 million at the start of the period. WAF paid A$22 million of loan principal during the quarter and said it intends to accelerate repayments to secured lenders over the next 12 months, alongside the A$229 million special dividend paid on 7 October.
Kiaka drives growth as Sanbrado eases
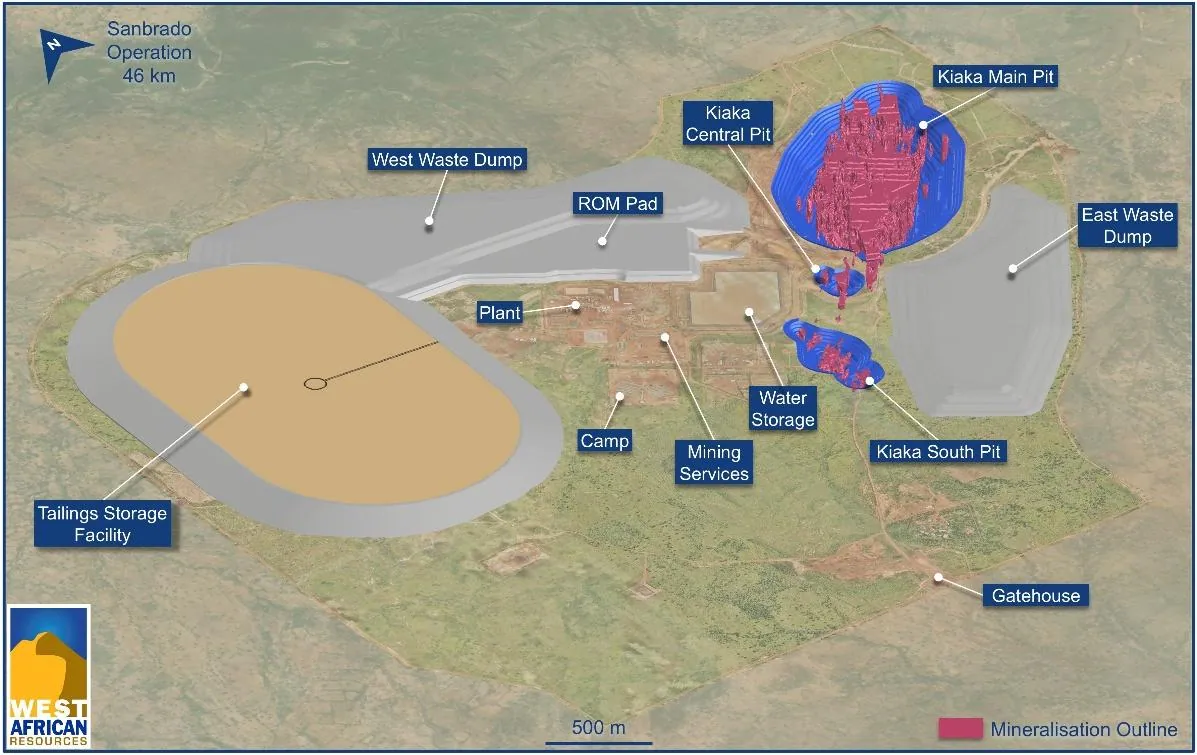
Kiaka supplied the operational momentum. Production rose 13% from the previous quarter to 76,030 ounces, supported by a 15% increase in mill throughput to 2.871 million tonnes. Site sustaining cost fell to US$1,554 per ounce, although explosives supply remains an operational bottleneck and the Government of Burkina Faso has not yet approved a permit for Kiaka’s explosives manufacturing and storage facility.
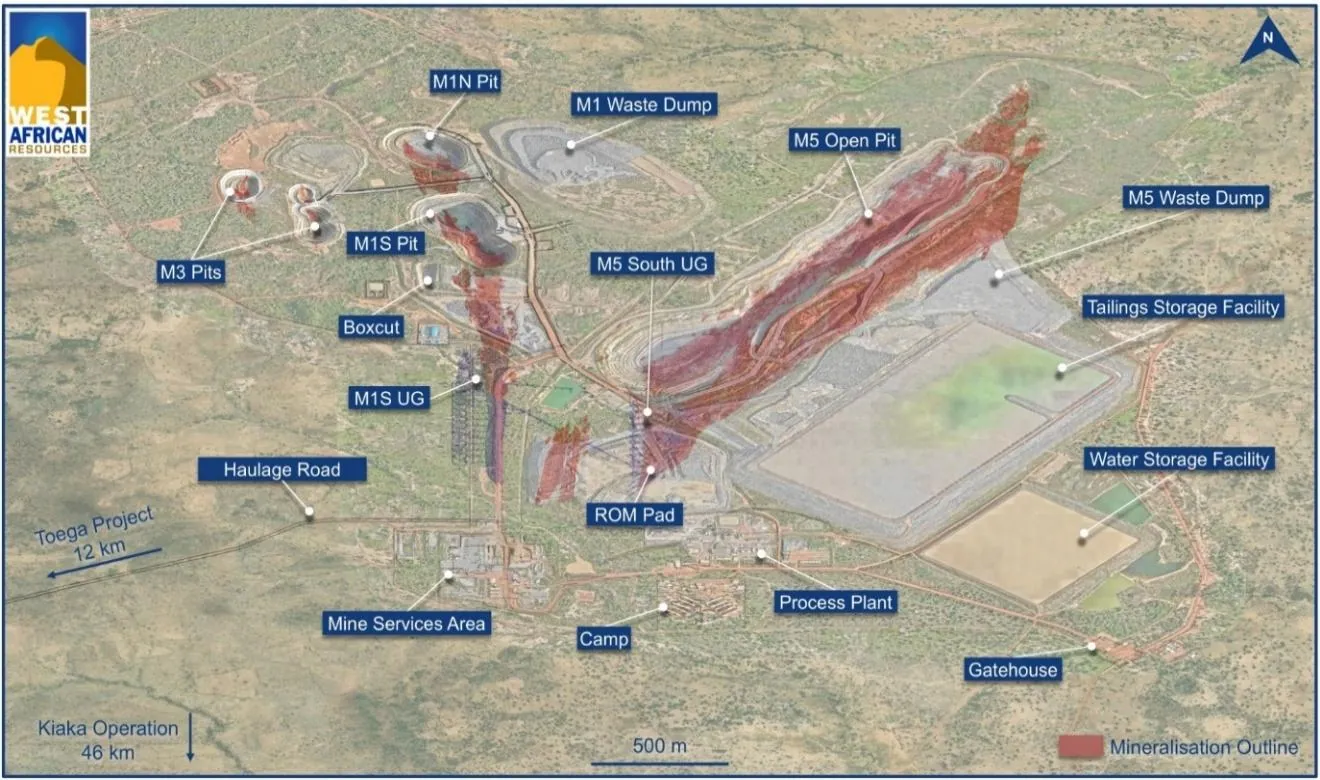
Sanbrado produced 51,920 ounces, down 10% quarter-on-quarter, as lower grades at the M1 South underground mine outweighed an increase from the M5 North open pit. A planned mill reline also reduced throughput. The operation’s site sustaining cost nevertheless improved to US$1,519 per ounce, and pre-strip work at Toega continued ahead of expected ore deliveries to the Sanbrado mill in early 2027.
The latest numbers extend the production and cash-generation run detailed in WAF’s record Q2 production, but the mix matters: Kiaka is carrying more of the current production load while Sanbrado’s underground performance and Toega’s development schedule remain important to the longer-term plan.
Kiaka stake sale and drilling set the next tests
WAF expects to finalise terms and complete SOPAMIB’s acquisition of a 25% holding in Kiaka SA during the December 2026 quarter for 70 billion CFA francs, or approximately A$174 million. WAF currently owns 85% of Kiaka SA; completion would reduce its interest to 60%, with the Burkina Faso government retaining 15%.
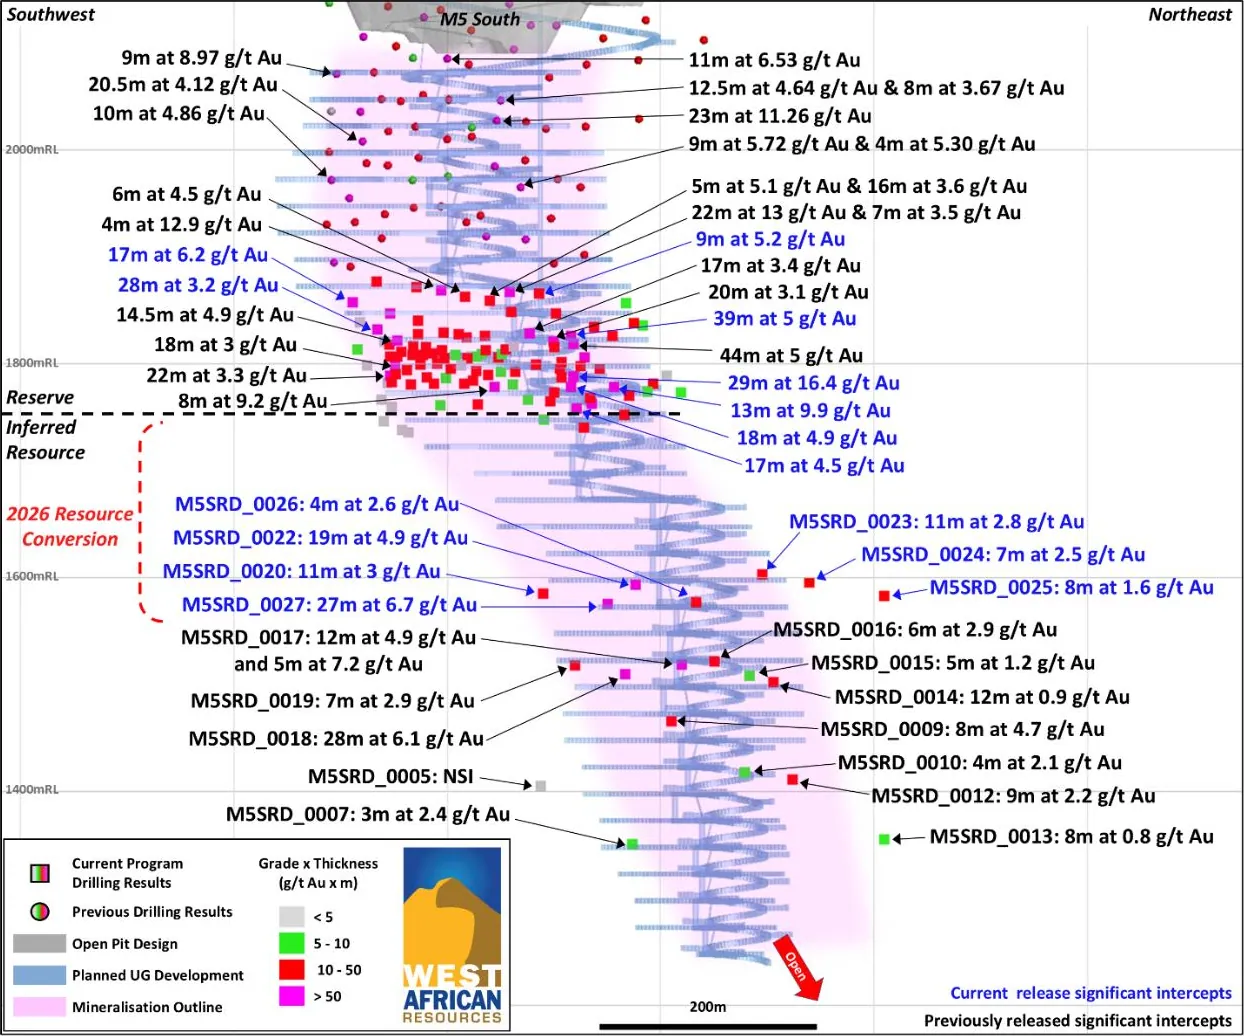
Growth spending continued at Toega, where A$26 million was directed to pre-production stripping and construction during the quarter. WAF is also running a 13,500-metre infill program on the Toega underground resource, with results expected in the December quarter. Those results will arrive alongside further drilling from M5, following the company’s earlier M5 South drilling results, which included high-grade intersections below the existing underground reserve.
The immediate question is whether strong cash generation can keep funding shareholder returns, debt reduction and expansion without being undermined by operational friction. Q4 production, the Kiaka ownership transaction, the explosives permit and Toega’s path to first ore will provide the next evidence.
Get ASX:WAF news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
WAF enters the final quarter with ample cash and guidance intact, but the next leg depends on converting Kiaka’s throughput gains and Toega spending into reliable future production.
Questions in the middle?
- Can WAF sustain production near the current run rate while Sanbrado’s underground grades recover?
- Will the SOPAMIB transaction complete on the expected terms and timing, reducing WAF’s Kiaka ownership to 60%?
- How quickly will the Kiaka explosives permit and supply constraints be resolved?
Sources
2-
Quarterly Cashflow Report (opens in a new tab)Verified source. West African Resources Limited · 28 Oct 2026
-
Quarterly Activities Report (opens in a new tab)Verified source. West African Resources Limited · 28 Oct 2026