Bannerman clears Etango funding hurdle as Namibia uranium build begins

Bannerman Energy has cleared the two gates that mattered most for Etango: funding and Final Investment Decision. The Namibia uranium project now enters full-scale construction, with first production targeted for 2028 and construction cash largely in place.
- US$320.4 million CNOL strategic investment completed
- A$124 million institutional placement settled at A$4.00 a share
- Etango JV approves FID for the 3.5 Mlbs-a-year Etango-8 design
- US$295 million held by the Etango JV and A$175 million held by Bannerman
- Bulk earthworks are 99% complete and 2028 first production remains targeted
 Add us as a preferred source on Google
Etango clears its funding and investment gates
Bannerman Energy Ltd (ASX:BMN) has moved its Etango uranium project in Namibia from a funded development story into full-scale construction. The Etango joint venture took Final Investment Decision after quarter end, following completion of China National Nuclear Corporation subsidiary CNNC Overseas Limited's US$320.4 million strategic investment and Bannerman's A$124 million institutional placement.
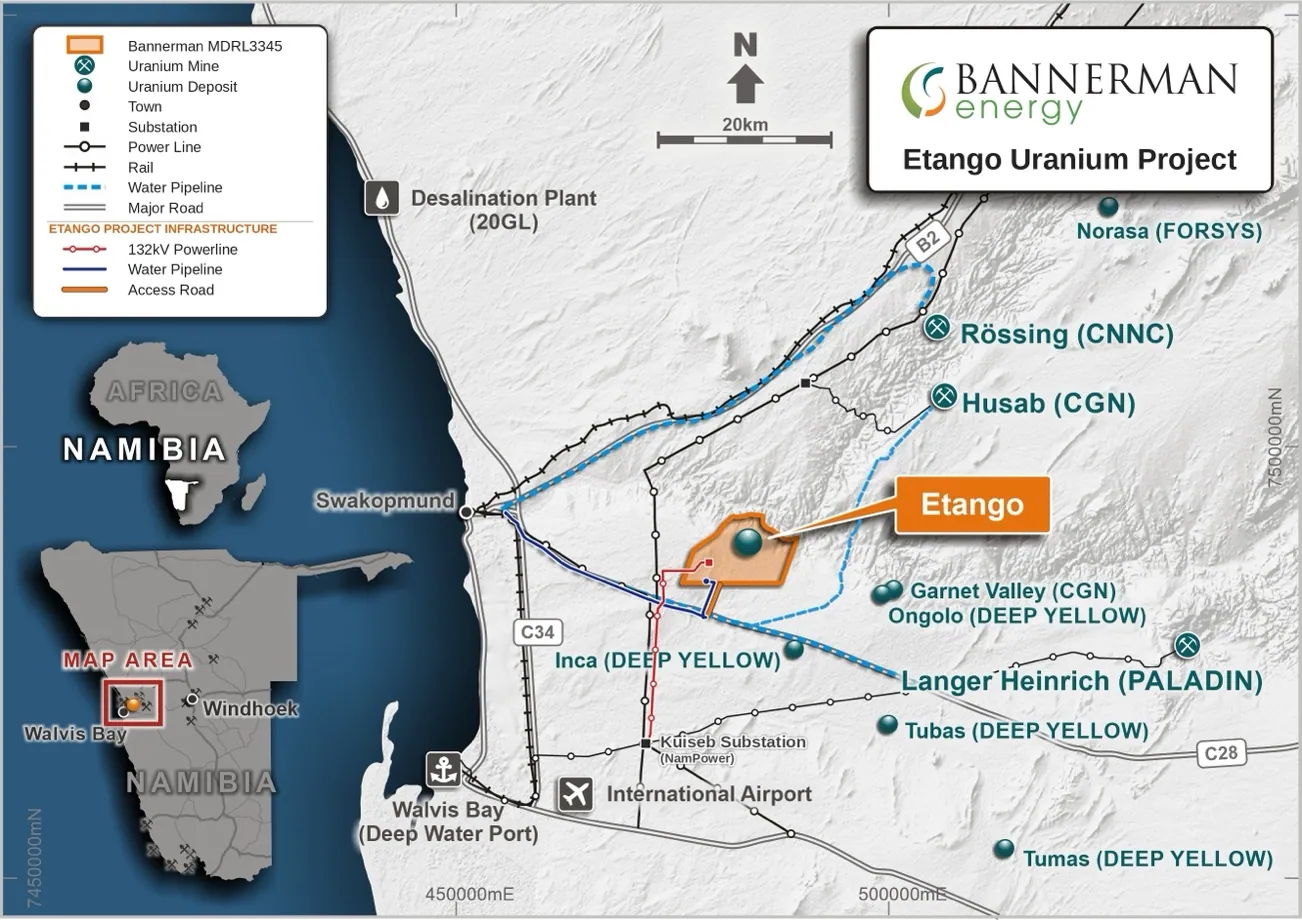
The FID applies to the Etango-8 design, which has forecast average annual production of approximately 3.5 million pounds of uranium oxide, or U3O8. First production remains targeted for 2028. The company describes the financing structure as a fully funded pathway through construction, ramp-up and into commercial production, although the capital estimates and production timetable remain forecasts rather than guarantees.
The transaction gives CNOL a 45% interest in the Etango JV, while Bannerman retains 55%. The joint venture owns 95% of the Etango project, translating to Bannerman's stated underlying economic ownership of 52.25%. CNOL will also purchase 60% of Etango's life-of-mine production under binding offtake terms based on spot and term uranium price indices at delivery, with no price floors or ceilings.
Cash balances now support the construction phase
At 30 September, the Etango JV held approximately US$295 million in cash, excluding cash in its Namibian subsidiaries. Bannerman separately held approximately A$175 million in consolidated cash, excluding the joint venture. The company says that combination covers the residual pre-production capital and Bannerman's forecast share of working capital through construction, ramp-up and targeted commercial production.
The project carries a forecast pre-production capital cost of approximately US$353 million, plus or minus 10%, with about US$64 million incurred through the end of September. The financing milestone was preceded by the US$320.4 million CNOL investment, which earlier reporting identified as the step needed to move Etango towards a Final Investment Decision.
Bannerman's institutional placement issued 31 million shares at A$4.00 each. A subsequent non-underwritten share purchase plan raised a further A$0.44 million, below the approximately A$10 million target previously described. The placement and SPP increase the company's equity base, but the filing presents them as funding support for a project that now has a substantial strategic partner and dedicated joint venture cash.
Construction advances before the main build
Etango's early works programme remains aligned with budget and schedule, according to Bannerman. Bulk earthworks are approximately 99% complete, 14,700 cubic metres of concrete has been cast across the first two concrete packages, and production of heap leach drainage aggregate has reached roughly half of the required volume.
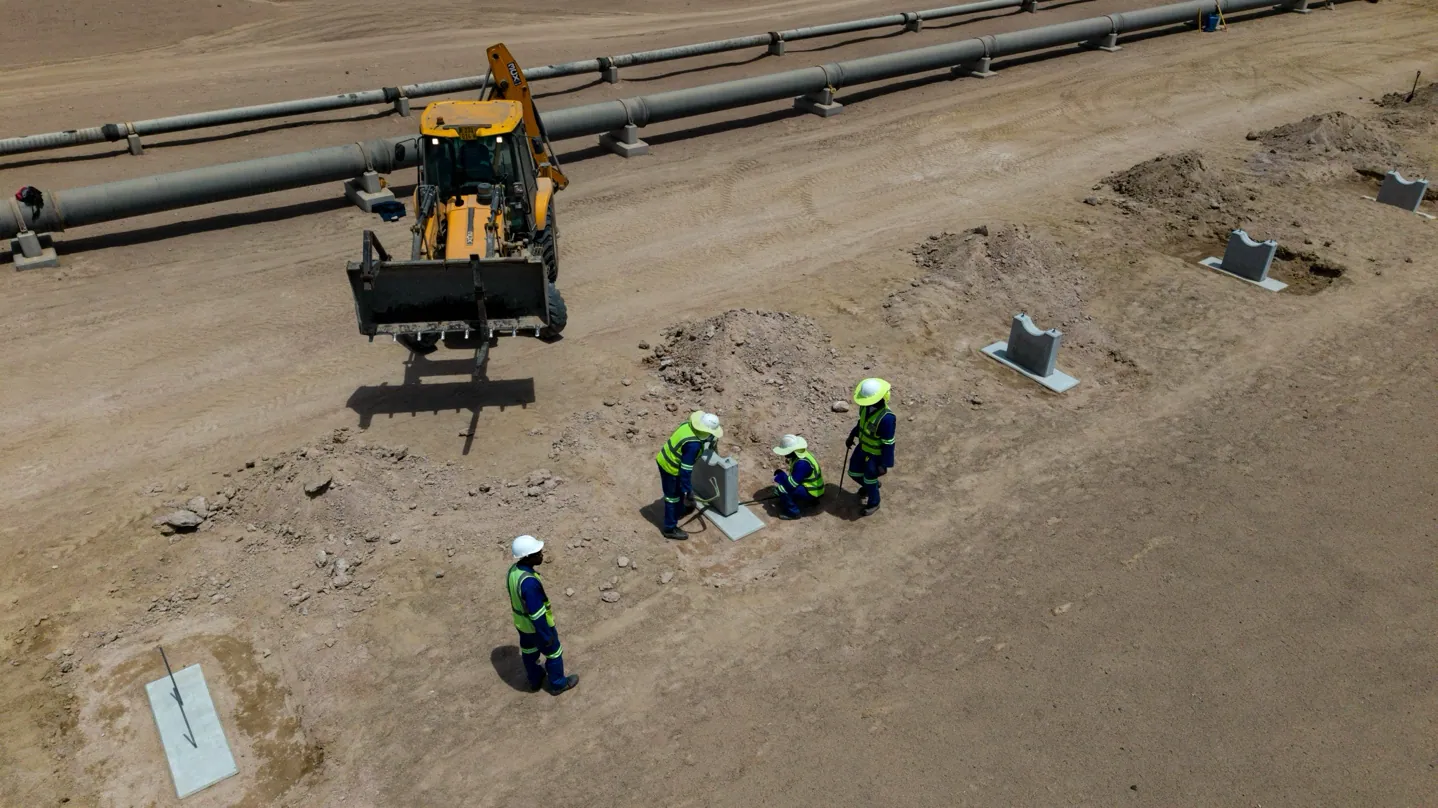
The permanent water pipeline is about 90% complete, while dry plant design is 98% complete and wet plant structural engineering is 33% complete. Power infrastructure design is progressing under the NamPower agreement, and the Walvis Bay acid storage and handling facility is 53% designed. Those figures point to a project already well advanced physically, but the shift from early works to full-scale construction brings a larger test of execution, procurement and cost control.
Execution risks become more visible
The quarter also produced a reminder that construction momentum does not remove operational risk. A contractor employee suffered the project's first lost-time injury in more than 16 years after a compactor incident caused a hairline fracture to his left foot. Bannerman said safety, quality and delivery would remain its priorities as construction expands.
Uranium market conditions provide a supportive backdrop but not a substitute for project delivery. The spot price closed the quarter at US$89.75 per pound, while the long-term price reference stood at US$97 per pound. Etango's offtake structure gives CNOL market-based pricing and leaves Bannerman responsible for marketing the remaining 40% of production, meaning future sales arrangements and construction performance will remain important markers ahead of 2028.
Get ASX:BMN news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Bannerman has removed the immediate funding and FID hurdles, leaving construction execution, capital discipline and the 2028 commissioning target as the next tests.
Questions in the middle?
- Can the full-scale construction programme remain within the approximately US$353 million pre-production capital estimate?
- How will Bannerman place the 40% of Etango production it retains for independent marketing?
- Will safety performance remain controlled as the contractor workforce and construction intensity increase?
Sources
1-
Quarterly Activities Report (opens in a new tab)Verified company source. Bannerman Energy Ltd · 29 Oct 2026 · investors.bannermanenergy.com