Hastings secures Thai processing foothold ahead of 2027 production

5 min read
11:12am on Wednesday 28th of October, 2026 AEDT ~11am, 28th Oct, 26
Hastings Technology Metals has completed its 49% acquisition of a Thai hydrometallurgical plant, with upgrades targeting 12,000 tonnes per annum of Mixed Rare Earth Chloride output. The company now faces the harder test: commissioning the facility, securing customers and converting a contracted feedstock position into sales.
- 49% Kabin Buri plant acquisition completed, with total consideration capped at US$15 million
- 23 million Hastings shares to be issued at A$0.50 each, representing about 9% of enlarged capital
- Commissioning targeted for Q1 2027 and first MREC production for Q2 2027
- Binding agreement covers 10,000 tonnes per annum of monazite concentrate feedstock
- Hastings is preparing a Thai BOI application while negotiating potential majority ownership
 Add us as a preferred source on Google
Thai plant acquisition reaches completion
Hastings Technology Metals Ltd (ASX:HAS) has moved its Thai processing strategy from transaction to execution, completing the acquisition of a 49% interest in BZNM Co Ltd, owner of the Kabin Buri hydrometallurgical plant. The facility is being upgraded to produce approximately 12,000 tonnes per annum of Mixed Rare Earth Chloride, or MREC.
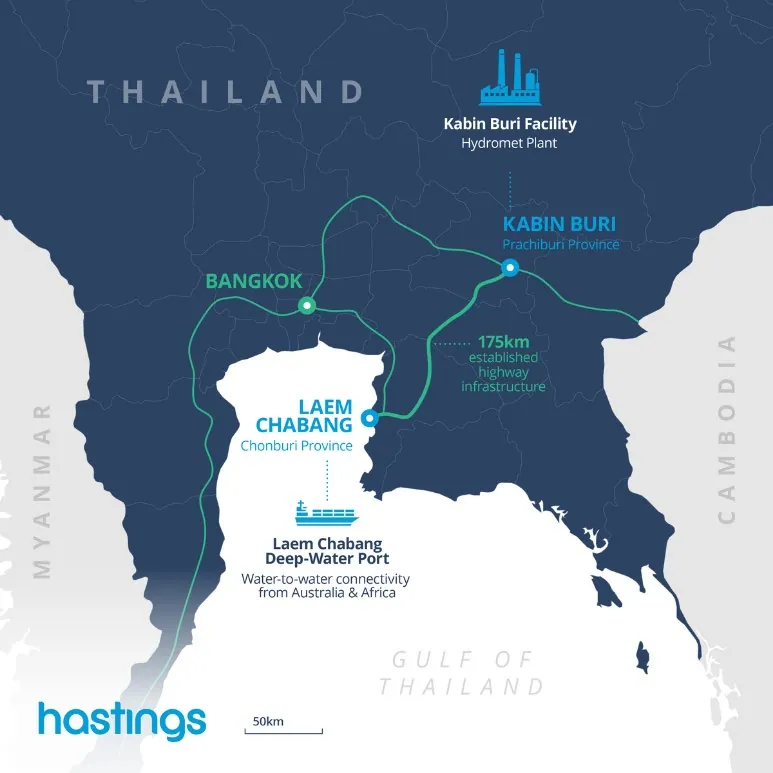
The announcement gives two completion dates: 27 October 2026 in its highlights and later in the transaction detail, while the body also says the acquisition was completed on 1 October. Hastings did not explain the discrepancy. The commercial milestone is nonetheless clear: the company now has an equity position in the plant and is progressing towards commissioning.
US$15 million consideration includes production-linked payments
Total consideration remains capped at US$15 million. It includes a US$0.5 million deposit, an equity component stated at US$8 million, a US$1 million commissioning payment and US$5.5 million in deferred cash payments. The equity component requires Hastings to issue Enuo Holdings 23 million ordinary shares at A$0.50 each, which the company expects will represent about 9% of its enlarged issued capital.
The deferred cash is not simply a scheduled obligation. It is split into US$3 million and US$2.5 million instalments, payable around the first and second anniversaries of commercial production only if the plant can produce MREC to agreed specifications, sell it to arm's-length customers under contracts or purchase orders, receive the sale proceeds and avoid unresolved material quality or operational failures. Those conditions place a portion of the acquisition price behind actual operating performance.
Commissioning schedule sets the next operational test
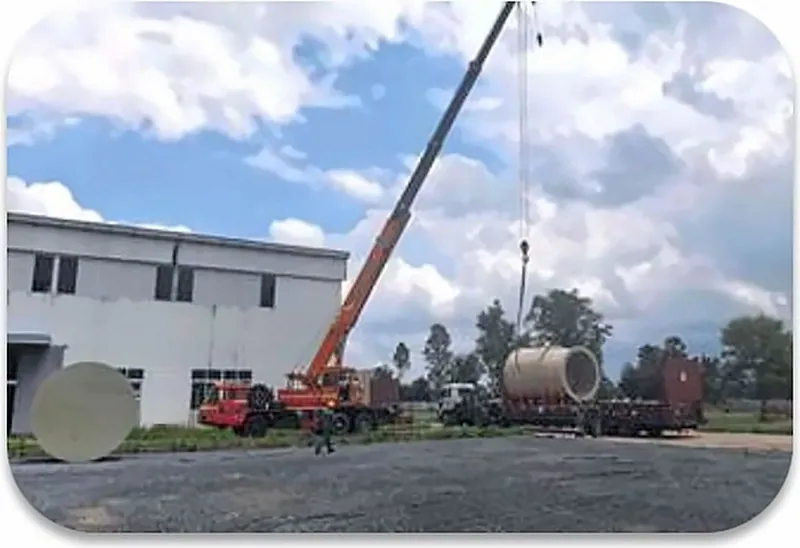
Installation and upgrade work is scheduled to run through January 2027, followed by process testing and commissioning in the first quarter. First production is targeted for the second quarter of 2027, subject to the remaining works and successful commissioning, with output expected to ramp progressively as operating performance and product quality stabilise.
The timetable is later than the Q4 2026 production target reported in Hastings' earlier Thai plant strategy, while the planned capacity has since been set at approximately 12,000 tonnes per annum rather than 6,000 tonnes. The company says initial operations do not depend on concentrate from its Yangibana joint venture, giving the Thai facility a proposed production pathway separate from the Australian project's development timetable.
Feedstock is contracted while customer arrangements remain open
Hastings has a binding framework agreement with Enuo for at least 10,000 tonnes per annum of monazite concentrate grading at least 54% total rare earth oxide on a dry basis. That agreement has an initial two-year term with a one-year renewal option and is intended to support the upgraded plant's planned capacity.
The company also says it has received enquiries from prospective feedstock suppliers and MREC customers in the United States, Europe and Asia. Those discussions are not yet binding: additional supply and sales arrangements remain subject to commercial terms, feedstock suitability and product specifications. Hastings' earlier capacity upgrade and feedstock deal established the 12,000-tonne target and supply framework; the next question is whether those inputs translate into accepted product and cash receipts.
BOI application could support a larger Hastings stake
Hastings has begun preparing an application for investment promotion with Thailand's Board of Investment. If approved, the promotion may allow BZNM to be majority or wholly foreign-owned for the promoted activity, alongside potential tax, import-duty and visa benefits. Hastings is negotiating with the other shareholders to increase its interest to 51% or more, but any such move would require agreement and relevant regulatory approvals.
That makes the BOI process more than a tax-incentive exercise: it may determine how much control Hastings can ultimately take over the processing asset. For now, the company remains a 49% owner, with commissioning, customer acceptance, additional feedstock, the BOI decision and the potential ownership increase all still ahead.
Get ASX:HAS news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The acquisition removes one transaction hurdle, but value now depends on completing the upgrade, producing saleable MREC in Q2 2027 and converting the 49% position into reliable operating cash flow.
Questions in the middle?
- Will commissioning deliver MREC that meets customer specifications on the current Q1-Q2 2027 timetable?
- How quickly can Hastings turn non-binding customer enquiries into contracted sales and cash receipts?
- Will Thailand’s BOI process enable Hastings to secure majority ownership, and on what commercial terms?
Sources
1-
HAS Completes Legal Closure 49% Interest Thai Hydromet Plant (opens in a new tab)Verified source. Hastings Technology Metals Ltd · 28 Oct 2026