Magontec’s two businesses show signs of a broader recovery

4 min read
8:56am on Thursday 29th of October, 2026 AEDT ~8am, 29th Oct, 26
Magontec’s nine-month revenue rose 28.9% to A$59.4 million as stronger electronic anode sales and a recovery in Metals lifted gross profit to A$12.8 million. The turnaround is generating cash before working-capital movements, but Chinese demand, European automotive weakness and near-term debt maturities remain live risks.
- Revenue up 28.9% to A$59.4 million for nine months
- Gross profit rises 38.1% to A$12.8 million
- Metals gross profit recovers from a A$0.4 million loss to A$2.4 million
- Underlying operating cash flow reaches A$3.4 million
- A$7.8 million German borrowing facility matures on 30 November 2026
 Add us as a preferred source on Google
Magontec’s recovery gathers pace across both divisions
Magontec Limited (ASX:MGL) has extended its operational recovery into the September quarter, with nine-month revenue climbing 28.9% to A$59.4 million and gross profit rising 38.1% to A$12.8 million. The company also moved to EBITDA of A$3.2 million excluding unrealised foreign exchange, compared with a A$1.5 million loss in the prior corresponding period.
The result builds on the company’s 1H26 gross profit surge
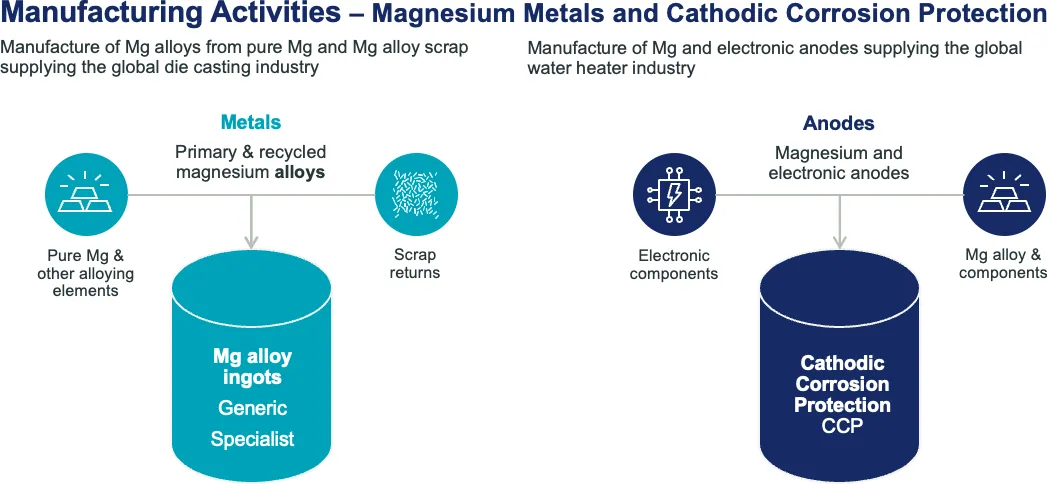
That recovery was broad rather than confined to one product line. Metals gross profit improved to A$2.4 million from a A$0.4 million loss, while Cathodic Corrosion Protection contributed A$10.4 million, up from A$9.7 million. In the CCP division, nine-month revenue rose 5%, with electronic anode sales the principal driver.
Electronic anodes lead CCP growth
Magontec said revenue from its ICAS impressed-current anode systems increased 26% in constant-currency terms over the nine months, with margins holding steady. The products are used in water-storage corrosion protection and are sold to original equipment manufacturers, plumber networks and online replacement markets.
Management attributed the demand to the continuing shift towards heat-pump water-heating technology and growing recognition of the ICAS products’ performance. A newer product suite launched in 2025 measures additional quality and purity metrics alongside corrosion protection, while the company said the aftermarket channels still have room to expand.
The European magnesium-anode business also produced higher margins, with gross profit up 24% in constant-currency terms despite a difficult housing market. China remains the weaker point: Magontec has cut less-profitable product lines and is concentrating on segments that can support sustainable margins, but expects the business to struggle for new volumes in the short term.
Metals volumes improve, but end markets remain uneven
Metals volumes sold to European and US customers rose 61% year on year, including a sharp increase in traded primary magnesium alloys sourced from China. Excluding trading, European sales volumes were 29.6% higher, although management said capacity utilisation remained below optimal levels.
Special Metals, produced in Germany and sold largely into European and US aerospace markets, made a particularly strong contribution. Magontec linked the demand to increased defence spending, while warning that the business faces difficult supply-chain conditions for the raw materials required to make the alloys. The broader Metals recovery has also been accompanied by a metals strategic review
Cash generation improves while debt commitments approach
Underlying operating cash flow reached A$3.4 million for the nine months, against an A$1.3 million outflow a year earlier. That measure excludes working-capital movements, interest and tax; after those items, net cash generated from operating activities was negative A$155,000, with receivables and inventory absorbing cash.
Net debt stood at A$1.4 million at 30 September, equivalent to 3.1% of net debt plus equity. Net assets were A$45.2 million, or 78.0 cents a share, down from 84.1 cents a share at the same point a year earlier. The company’s A$7.8 million secured Commerzbank Germany borrowing is scheduled to mature on 30 November 2026, while an undrawn RMB10 million Chinese facility is being renewed.
Fourth-quarter momentum faces contrasting tests
Management expects fourth-quarter ICAS sales to continue at a similar level to the first nine months and says European magnesium-anode volumes and margins should hold through the rest of FY26 and into the first half of FY27. It also expects productivity measures in the German and Romanian recycling operations to begin having an effect through the fourth quarter and into 2027.
Those expectations sit alongside a more mixed operating backdrop. European automotive production, a key consumer of magnesium alloys, is weakening; Chinese anode demand remains tied to a pressured housing market; and the company is still implementing separate management structures for CCP and Metals. The figures are unaudited, so the next audited report will show whether the improvement in earnings and cash conversion has proved durable.
Get ASX:MGL news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Magontec has produced a materially stronger nine-month result, but the next test is converting operational momentum into cash while refinancing its German debt and repairing the Chinese business.
Questions in the middle?
- Can ICAS growth remain at its current pace as Magontec expands OEM and aftermarket sales?
- Will productivity gains in Germany and Romania offset weaker European automotive demand?
- How will the company address the 30 November Commerzbank maturity and renew its undrawn Chinese facility?
Sources
1-
Quarterly Report to 30 September 2026 (opens in a new tab)Official market announcement. Magontec Limited · 29 Oct 2026 · magontec.com