Devon suspension leaves Matsa reliant on AngloGold proceeds and new funding

Matsa Resources has reported a $39.4 million FY2026 loss, negative net assets and a $28 million operating cash outflow after Devon operated at a loss and was suspended following a contractor dispute. A $55 million AngloGold tenement sale offers a potential liquidity reset, but the annual report says material uncertainty remains over the group's ability to continue as a going concern.
- $39.4 million FY2026 net loss, versus a $1.4 million profit in FY2025
- Devon produced 7,317 ounces sold but operated at a loss and remains suspended
- Negative net assets of $0.8 million and $28.0 million operating cash outflow
- AngloGold agreed to acquire selected Lake Carey tenements for $55 million
- Lake Carey resources totalled 904,000 ounces and reserves 80,000 ounces
 Add us as a preferred source on Google
Devon losses drive material going-concern uncertainty
Matsa Resources Limited (ASX:MAT) entered gold production during FY2026, but the financial result shows how quickly an operating mine can become a balance-sheet problem. The company reported a net loss of $39.4 million, compared with a $1.4 million profit a year earlier, while operating activities consumed $28.0 million in cash.
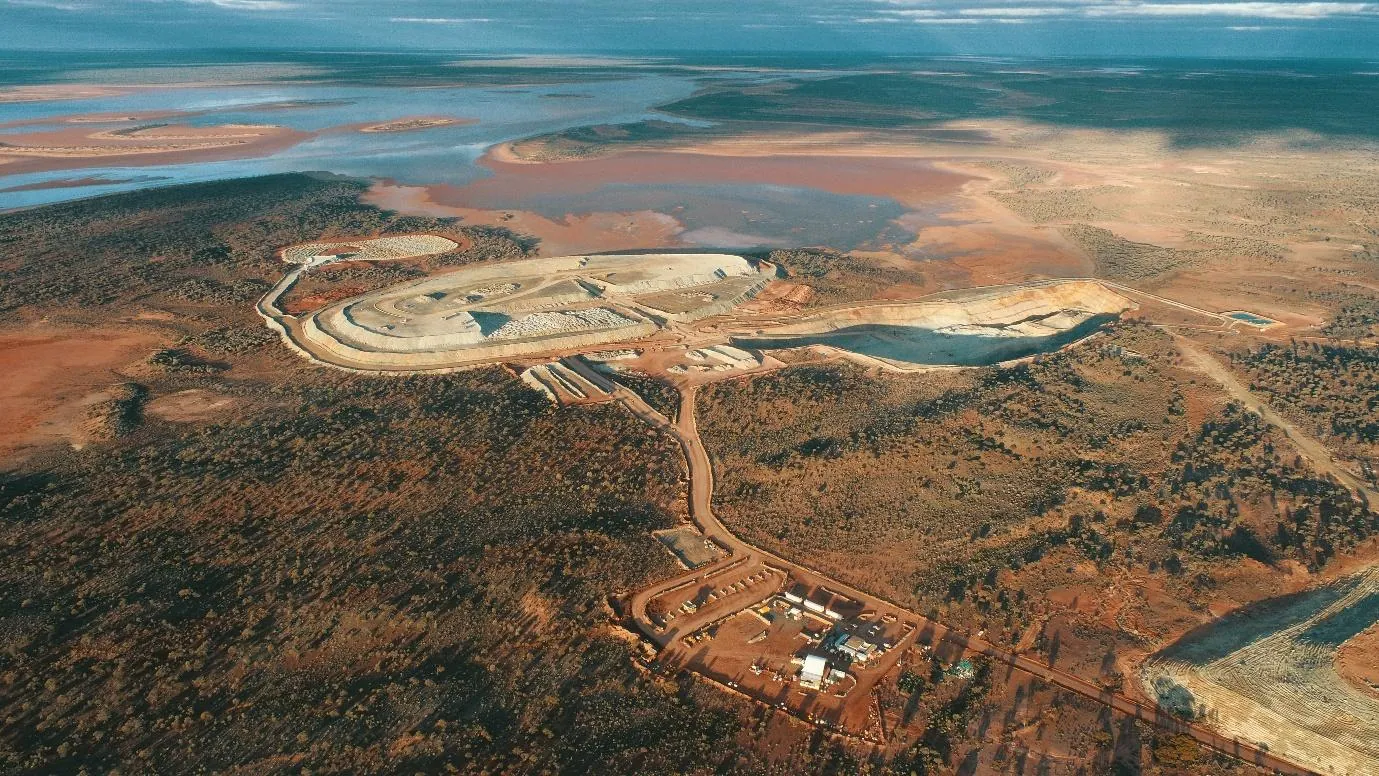
Devon delivered 141,000 tonnes at 2.06 grams per tonne of gold to the FMR processing plant during the year, with 7,317 ounces sold and about 10,100 ounces mined. But the mine operated at a loss. Historical underground voids contributed to mining dilution of about 40%, while the operation generated $81.1 million of mining costs against $48.3 million in revenue. Mining was later suspended on 9 September following a dispute with contractor Blue Cap Mining.
The annual report says Blue Cap subsequently made a further disputed claim relating to alleged future Devon profits, appointed receivers and managers over assets of two Matsa subsidiaries, and prompted those subsidiaries to appoint voluntary administrators. The directors say the claim lacks merit, but acknowledge that the dispute, the subsidiary insolvency processes and Devon's uncertain future create a material uncertainty that may cast significant doubt on the group's ability to continue as a going concern. That risk was also the focus of the earlier going-concern warning, which highlighted the same combination of operating losses, debt and the pending AngloGold transaction.
AngloGold sale provides a potential liquidity bridge
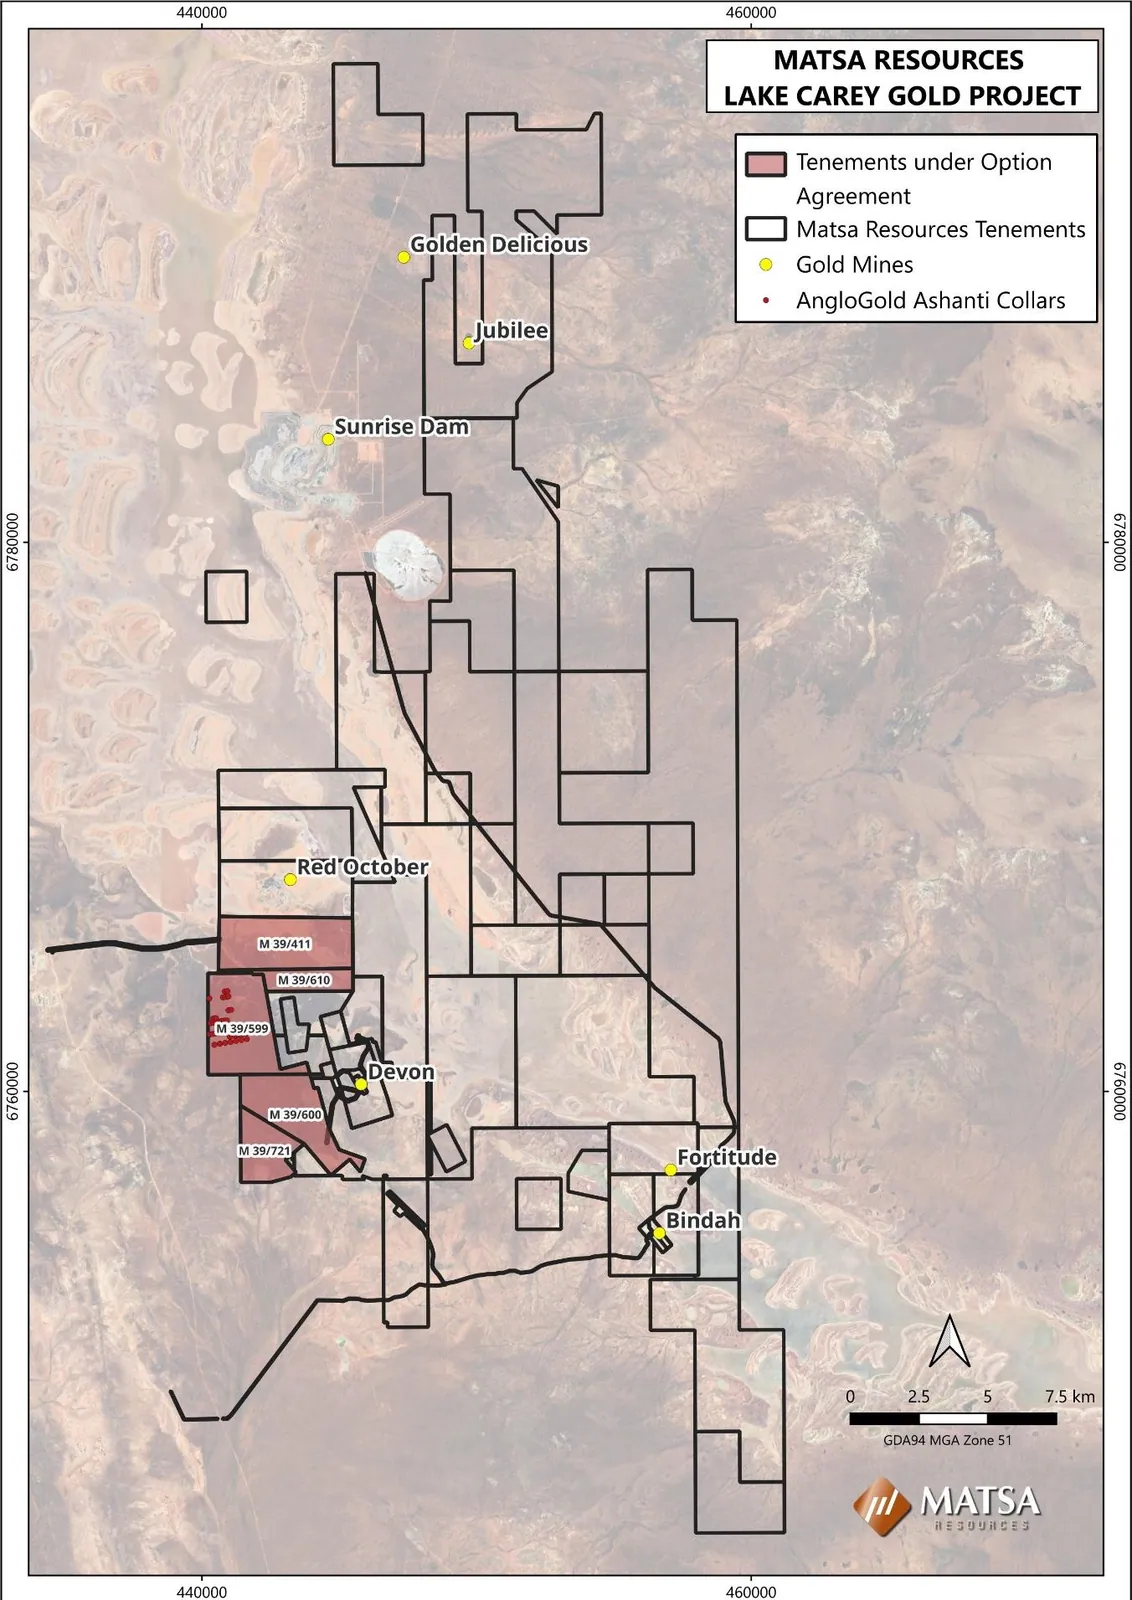
The principal counterweight is AngloGold Ashanti's agreement to exercise its Lake Carey tenement option early for a fixed $55 million. Matsa received a $10 million deposit after year-end and said the remaining $45 million was expected by 4 November once completion conditions had been satisfied. The fixed price replaces an earlier formula-based consideration of up to $101 million, making the transaction simpler but materially reducing the headline value described in the original option arrangement.
Matsa intends to allocate $30 million of the proceeds to its Deutsche Balaton debt facilities, leaving $25 million for operations under the cash-flow scenarios considered by the directors. The shareholder-backed facility was increased from $17.5 million to $37.5 million after year-end, with repayment extended to 30 June 2027, while a separate $4 million facility was used to repay other secured borrowings. The original early $55 million Lake Carey sale was reported as conditional, and the annual report still treats completion and debt repayment as central assumptions in its going-concern assessment.
Lake Carey exploration remains the strategic upside
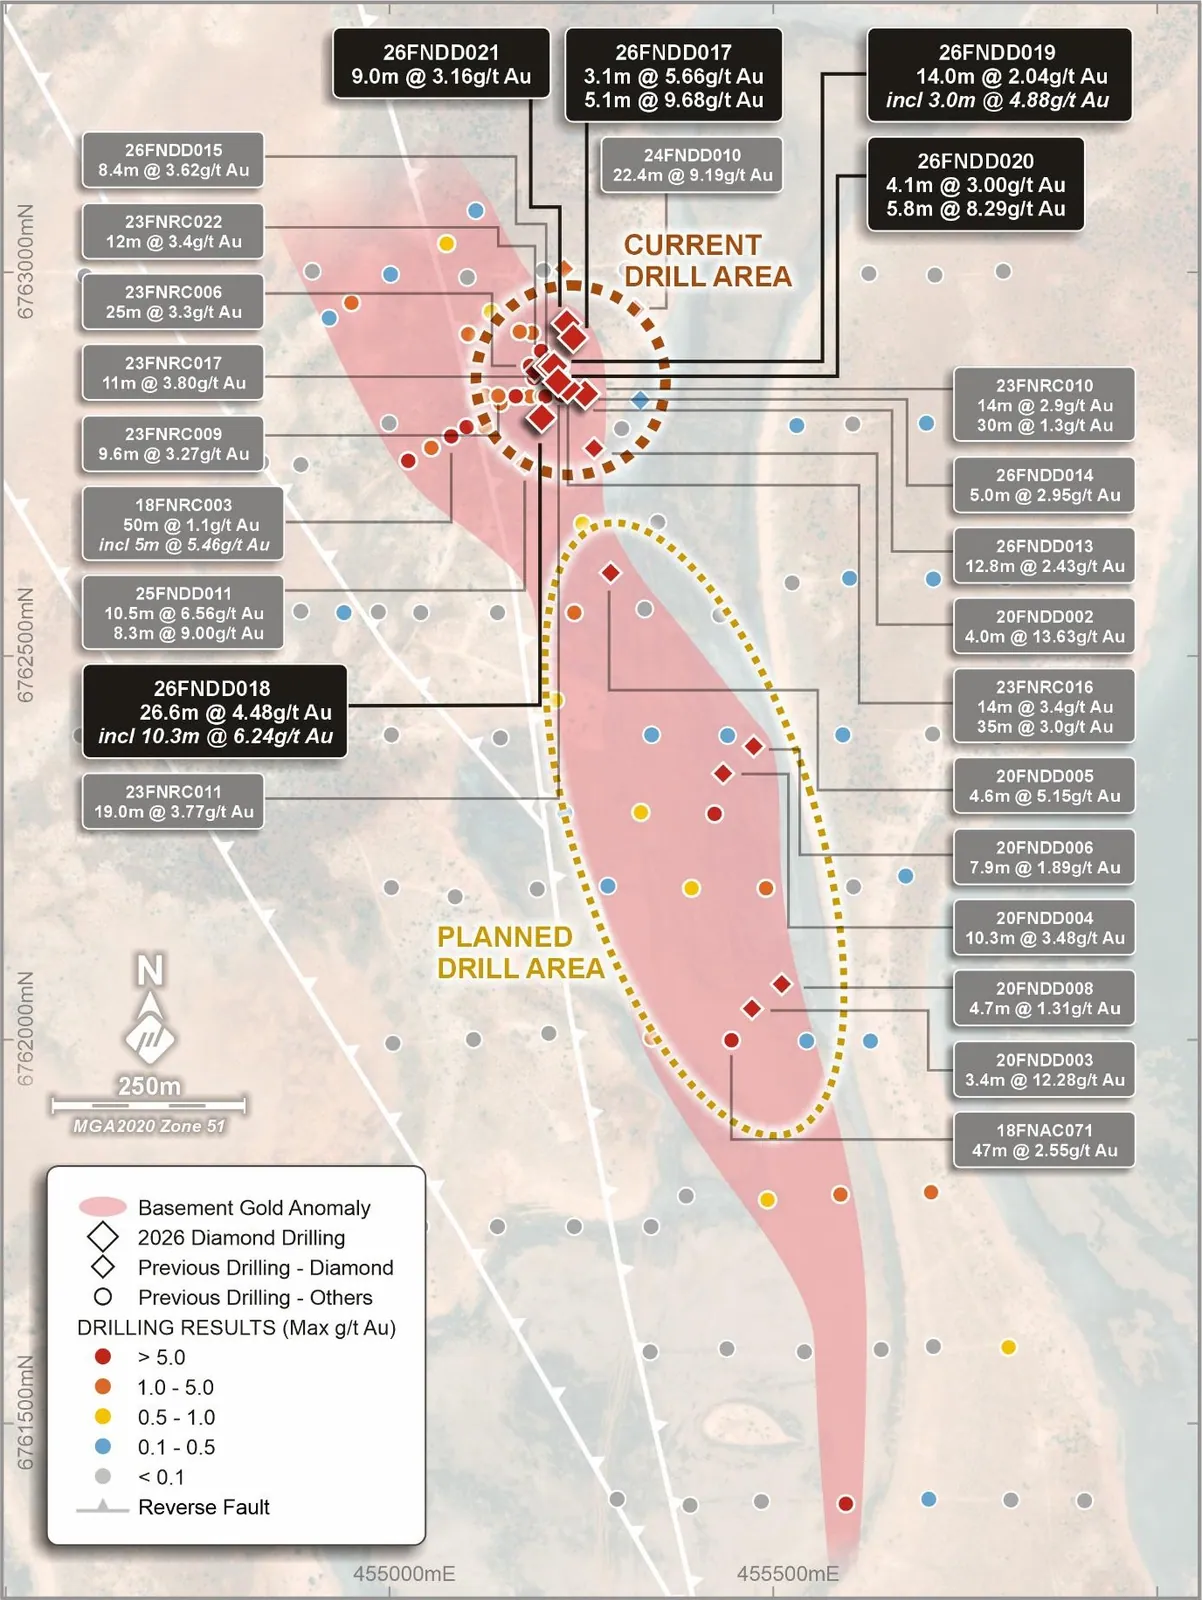
Outside the troubled Devon operation, Matsa continued drilling at Fortitude North, completing 21 diamond holes for 4,996 metres. Reported results included 26.6 metres at 4.48 grams per tonne gold, including 10.3 metres at 6.24 grams per tonne, and 5.1 metres at 9.68 grams per tonne. The company said the results support its interpretation of stacked mineralised lodes, although drilling results alone do not establish an economic mine.
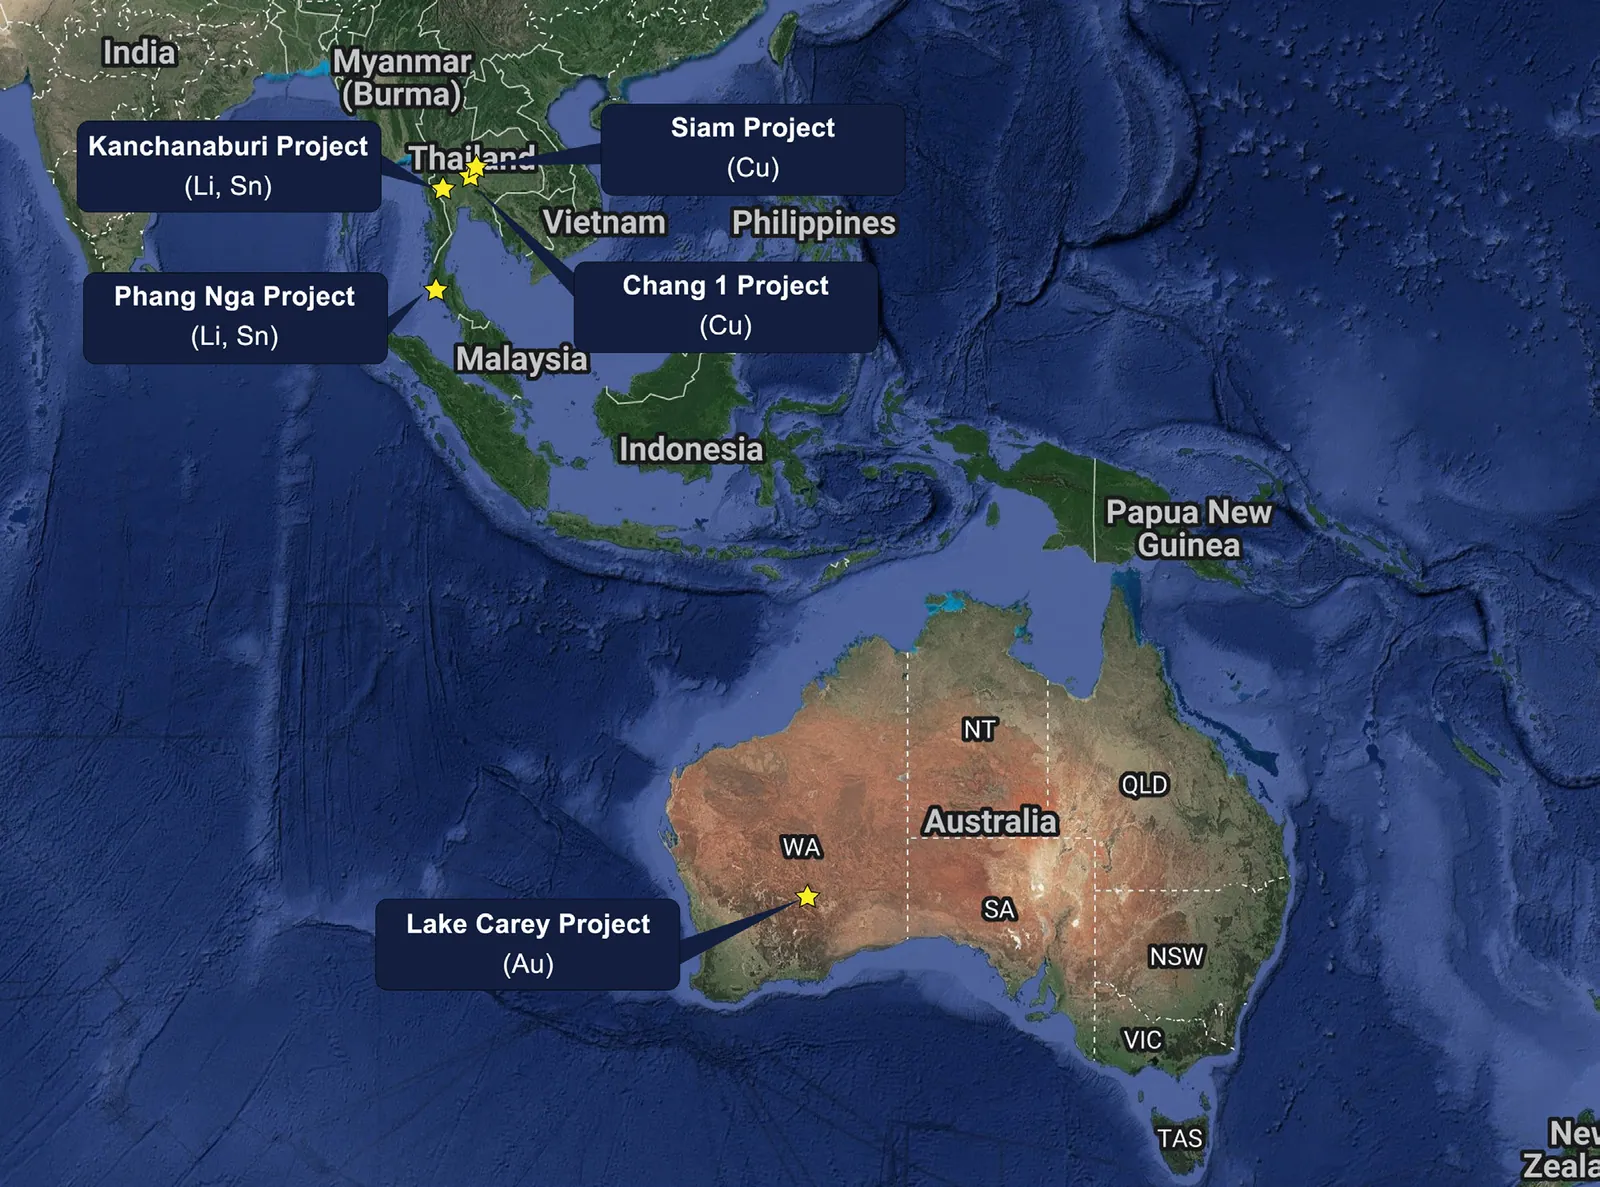
Lake Carey ended the year with 11.6 million tonnes at 2.4 grams per tonne for 904,000 ounces of resources, down from 942,000 ounces in the prior comparison after Devon depletion and remodelling. Reserves stood at 1.2 million tonnes at 2.1 grams per tonne for 80,000 ounces. Thailand's lithium, rare earths and copper exploration continued at a reduced pace while management prioritised Western Australian gold.
Debt, dilution and the next funding test
At 30 June, Matsa held $6.2 million in cash against $18.2 million of current borrowings and $15.6 million of trade and other payables. Net assets were negative $0.8 million, while shareholders' equity fell from $20.5 million to negative $0.9 million attributable to company owners. The group raised $10.0 million through a share placement and received $8.6 million from option exercises during the year, taking ordinary shares on issue to about 971.2 million.
The accounting outlook therefore depends on several events beyond the FY2026 numbers: settlement of the AngloGold consideration, the resolution of the Blue Cap dispute and administration process, and whether Devon restarts on terms that produce positive cash flow. If those assumptions fail to hold, the report says Matsa may need further capital to meet debt obligations. Fortitude North may offer geological upside, but the immediate investment question is less about ounces in the ground than how much of the AngloGold cash survives the claims, debt repayment and cost of keeping the wider group alive.
Get ASX:MAT news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The AngloGold proceeds could buy Matsa time, but the company still needs a durable answer for Devon, its disputed liabilities and debt beyond June 2027.
Questions in the middle?
- Will the Blue Cap dispute and subsidiary administration process restrict Matsa's ability to control or restart Devon?
- How much of the AngloGold consideration will remain available after debt repayment, transaction costs and disputed claims?
- Can Fortitude North convert encouraging drilling into a larger resource and an investable development plan?
Sources
1-
Annual Report to shareholders (opens in a new tab)Verified source. Matsa Resources Limited · 28 Oct 2026