PARKD faces funding risk after $1.26 million annual loss

4 min read
1:34pm on Wednesday 28th of October, 2026 AEDT ~1pm, 28th Oct, 26
PARKD’s FY26 annual report puts the company’s funding position under sharper scrutiny after a steep revenue decline, a $1.26 million loss and $367,714 in cash. Its east-coast expansion produced new facilities, partnerships and demonstrations, but the next test is converting that platform into contracted work quickly enough.
- FY26 revenue fell to $5.47 million from $11.83 million
- Net loss widened to $1.26 million and operating cash outflow reached $1.14 million
- Auditor highlighted a material uncertainty related to going concern
- Penrith facility established with stated annual capacity of 65,000 square metres
- Fielders, Azzurri and McNab relationships support east-coast commercialisation
 Add us as a preferred source on Google
Auditor highlights funding uncertainty
PARKD Limited (ASX:PKD) has ended FY26 with a much larger loss, sharply lower revenue and an explicit warning that its ability to continue as a going concern depends on future cash generation and funding. RSM Australia Partners issued an unmodified audit opinion, but highlighted a material uncertainty after the modular construction company reported a $1.26 million loss, $1.14 million in operating cash outflow and net current liabilities of $160,262.
Cash and cash equivalents fell to $367,714 at 30 June 2026, from $674,970 a year earlier. The directors said the business must generate positive cash flow through meeting revenue forecasts, reducing costs or both, while retaining the ability to raise additional capital if required. The report says management’s 15-month cash-flow forecast assumes existing and anticipated contracts will generate ongoing revenue, but also acknowledges that failure to meet those forecasts could make further equity, convertible debt or other funding necessary.
Revenue falls as Audi project winds down
Revenue from customer contracts dropped 54% to $5.47 million, compared with $11.83 million in FY25. Design and construction of car parks contributed $4.92 million, down from $11.62 million, while feasibility and design services rose to $472,991 and prefabrication modules contributed $68,424.
The Audi Centre Myaree project remained the dominant disclosed related-party revenue stream, contributing $4.87 million during FY26 to an entity related to chairman Bronte Howson, compared with $8.01 million in the prior year. PARKD said the three-storey facility became fully operational during the second half and now serves as a reference project for applying its modular structural technology beyond conventional multi-level car parks. The report states the related-party transactions were conducted on normal commercial terms and at market rates.
Gross profit fell to $220,391 from $1.51 million, while the newly established NSW facility added $95,581 in operating costs. Administrative, employee, depreciation and finance costs then pushed the company to an operating loss of $1.21 million before the final loss after tax of $1.26 million. The deterioration follows the company’s earlier disclosure of a first-half loss while the Audi project wound down and the Penrith operation was commissioned.
East-coast platform expands before contract conversion
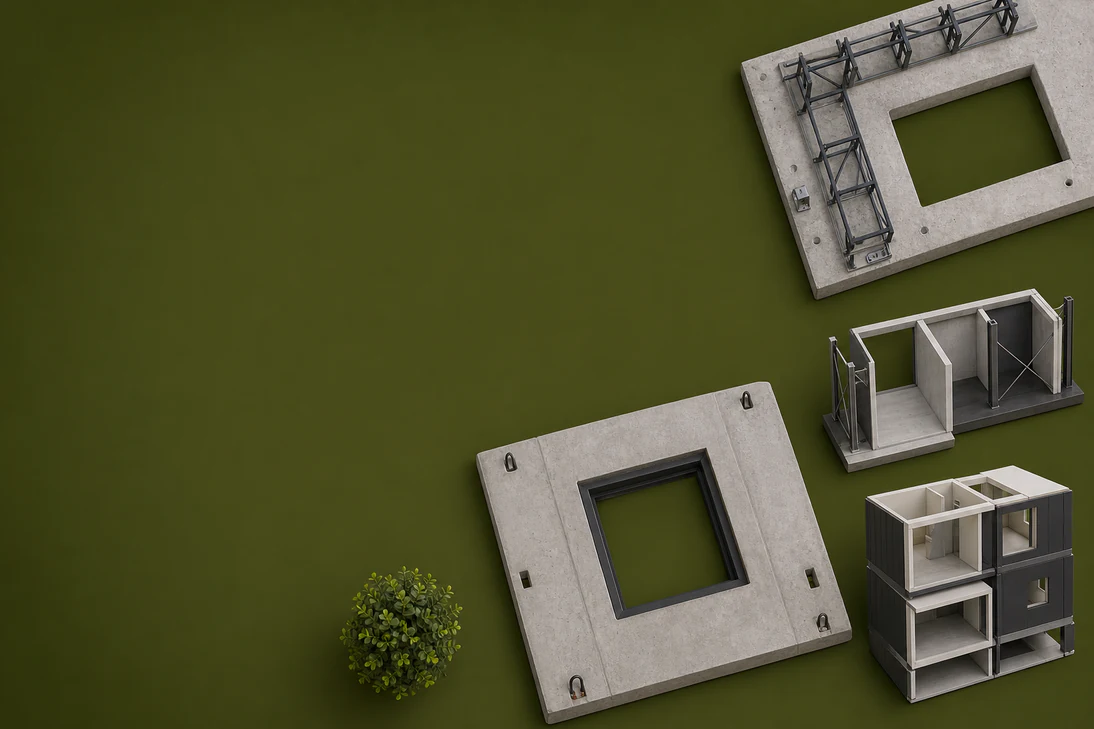
PARKD’s operational story is more constructive than its financial statements. The company commissioned a Penrith prefabrication facility during the December quarter, with stated capacity of approximately 65,000 square metres of MDSB and SlimDek210 modules annually. Its Queensland pilot with McNab Group demonstrated the transport of prefabricated components from NSW for installation elsewhere, while also marking the first external deployment of its PIEPS edge-protection system. This builds on the Penrith facility launch that previously reported the site’s commissioning, the McNab pilot and a $1 million capital raise.
The company also revised its exclusive national prefabrication agreement with Fielders, a BlueScope Steel division, covering its SlimDek210 and MDSB modular flooring systems. PARKD said the arrangement makes it the sole national provider of those prefabricated modules across Australia. Its east-coast network was further reinforced by the Azzurri strategic investment, a $220,000 investment completed in April, while Azzurri later joined Western Precast, Fielders BlueScope and Performance Cranes and Rigging in demonstrating PARKD’s data-centre system.
Data-centre demonstration remains an unpriced opportunity
During the June quarter, PARKD constructed a scale example of its PARKD-DC+ Data Centre Structural System at Jamisontown in NSW. The demonstration showcased rapid assembly of SlimDek210 module packs, integrated PIEPS edge protection and the potential to reduce work performed at height to contractors, consultants, operators and prospective customers from NSW, Victoria and South Australia.
That activity generated engagement, but the annual report does not disclose the value of any resulting contracts. At year end, PARKD said it had opportunities across data centres, car parks, retail developments and storage facilities, with structural solutions and quotations submitted nationally. The commercial question is therefore unusually plain: whether the company’s technical demonstrations and partner network can become signed projects before its cash position demands another financing.
Get ASX:PKD news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
PARKD has built a broader delivery platform, but the FY27 investment case now turns on cash discipline and evidence that its tender pipeline is converting into revenue-producing contracts.
Questions in the middle?
- How quickly can PARKD convert its data-centre, car-park, retail and storage pipeline into signed contracts and operating cash flow?
- Will the Penrith facility reach sufficient utilisation to justify its lease and operating costs?
- How much additional equity or other funding could be required if forecast contracts are delayed or margins remain weak?
Sources
1-
Annual Report to shareholders (opens in a new tab)Verified company source. Parkd Ltd · 28 Oct 2026 · parkdgroup.com