Saluda’s rising implants face a balance sheet test despite reaffirmed guidance

Saluda Medical delivered a strong operational start to FY27, with US implants up 55% and quarterly revenue rising 26% to US$23.1 million. But the medical device company ended September with US$73.6 million in cash, US$100 million of secured debt drawn and estimated funding for just 2.3 quarters at the quarter’s cash-use rate.
- US$23.1 million Q1 revenue, up 26% year on year
- US implants rise 55% to 838, with active physicians up 47%
- CAP24 paddle lead moves into full US commercial release
- US$42.7 million operating cash outflow in the September quarter
- FY27 revenue and EBITDA guidance reaffirmed
 Add us as a preferred source on Google
Strong US adoption meets a sharply weaker cash position
Saluda Medical, Inc. (ASX:SLD) has started FY27 with its strongest operating metric moving in the right direction and its balance sheet moving the other way. US patient implants jumped 55% to 838 in the September quarter, while global revenue rose 26% year on year to US$23.1 million. Yet operating cash outflow reached US$42.7 million, leaving US$73.6 million in cash at quarter-end.
Including US$25 million of undrawn debt capacity, Saluda reported total available funding of US$98.6 million, equivalent to 2.3 quarters based on the quarter’s operating cash use. That is a mechanical runway measure rather than a forecast of imminent exhaustion: the company says several large payments were concentrated in Q1 and expects cash use to fall in the remaining quarters of FY27. Its own operating plan puts existing cash resources at approximately June 2027.
The liquidity issue is not new. Annual report funding warning had already flagged that Saluda could need additional capital within 12 months, making the latest cash-flow report a more immediate test of whether commercial growth can begin to reduce funding pressure.
US implants outpace revenue as sales network matures
US revenue increased 34% to US$17.4 million, but grew more slowly than implants. Saluda attributed the gap to customers using inventory bought in earlier quarters and to a larger share of higher-volume ambulatory surgical centre accounts, where volume-based pricing lowers average selling prices. The company said average selling price remained broadly stable against the June quarter.
The underlying activity measures were stronger: the average number of active US implanting physicians rose 47% to 374, while physician utilisation increased 5%. Around 75% of the US sales force was fully trained at September-end, and roughly half of viable US territories had at least one fully trained representative. Saluda says the emphasis in FY27 is shifting from rapid sales-force expansion towards productivity and lower territory selling costs relative to revenue.
CAP24 opens a new surgical sales channel
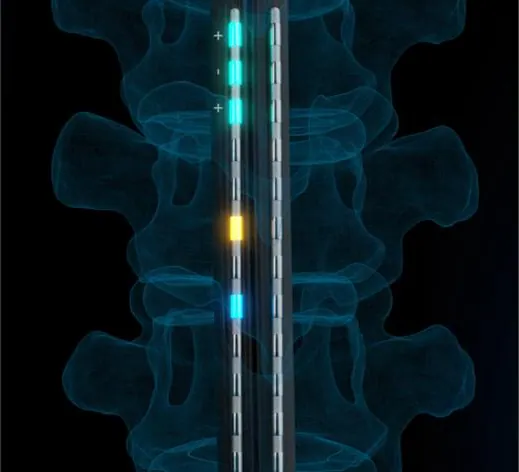
Saluda has moved its CAP24 paddle lead from a limited release into full US commercial release after a test involving approximately 10 initial accounts and subsequent expansion. The FDA-approved device is designed to allow the Evoke system’s physiologic, dose-controlled closed-loop therapy to reach neurosurgery and orthopaedic spine practices that were not previously addressed by Saluda’s percutaneous leads.
The company estimates the US paddle segment generated about US$670 million of revenue in 2024, or roughly 30% of the total US spinal cord stimulation market. The commercial opportunity is material, but the rollout is still at an early stage: the immediate execution question is how quickly Saluda can activate accounts and turn the existing sales infrastructure into repeat procedure volume. The device’s CAP24 FDA approval had previously been presented as the gateway to this surgeon segment.
Guidance holds while funding becomes the central constraint
International revenue rose 7% to US$5.8 million, led by Australia and Germany, with Austria added during the quarter. The September result was seasonally softer than the record US$27.0 million June quarter, which also included about US$600,000 of European deferred-revenue recognition. Saluda reaffirmed FY27 revenue guidance of US$113 million to US$122 million, gross margin of 50% to 52%, and an adjusted EBITDA loss of US$95 million to US$101 million.
The quarter’s cash use included US$4.5 million of annual employee incentive payments, US$2 million of previously disclosed executive retention payments, about US$2.4 million in two non-recurring project payments and roughly US$2.5 million tied to inventory-payment timing. Those items help explain why management expects lower cash use ahead, but they do not remove the need to demonstrate that revenue growth, CAP24 adoption and sales-force productivity can materially narrow the funding gap before the current runway shortens.
Get ASX:SLD news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Saluda has clear commercial momentum, but the next quarter must show whether one-off payments really drove the cash spike or whether growth still requires fresh capital.
Questions in the middle?
- How far will quarterly operating cash use fall once the incentive, retention and project payments do not recur?
- Can CAP24 generate meaningful incremental procedure volume before Saluda’s current funding runway becomes restrictive?
- Will higher implant volumes translate into revenue growth without further pressure from inventory timing and volume-based pricing?
Sources
3-
Quarterly Investor Presentation (opens in a new tab)Verified source. Saluda Medical, Inc · 29 Oct 2026
-
Quarterly Activity Report (opens in a new tab)Verified source. Saluda Medical, Inc · 29 Oct 2026
-
Quarterly Appendix 4C Cash Flow Report (opens in a new tab)Verified source. Saluda Medical, Inc · 29 Oct 2026