Beonic’s Vision platform moves from demonstration to paying customers

Beonic has launched its in-house Vision platform across four countries while delivering a profitable first quarter, with EBITDA of A$853,000 and an 83.0% gross margin. The stronger operating result came alongside weaker total revenue, negative operating cash flow and only 1.7 quarters of estimated funding.
- Vision launched commercially across the UK, South Africa, USA and Australia
- Q1 EBITDA of A$853,000 at a 15.1% margin
- Gross margin increased to 83.0%, while recurring revenue rose 2.3%
- Moroccan airport rollout reached five of seven sites
- Cash fell to A$1.633 million, equal to 1.7 quarters of estimated funding
 Add us as a preferred source on Google
Vision launches across four international markets
Beonic Limited (ASX:BEO) has put its newest growth product into paying customer deployments in the UK, South Africa, the USA and Australia, turning Beonic Vision from a product demonstration into a commercial offering within months. The in-house platform was first shown publicly at London’s Passenger Terminal Expo in March and has since been connected to a top-ten US airport using the customer’s existing CCTV network.
That architecture is central to the pitch. Beonic says Vision has been validated on low-cost computing hardware, removing a server supply constraint and reducing deployment costs. It has also matched point-of-sale transactions in a retail proof of concept, producing checkout abandonment and staffing insights, while a major US transport authority has begun a 250-camera evaluation. The early deployments do not yet establish the scale of future revenue, but they give the product a commercial foothold across airports, retail and transport.
The launch builds on the company’s earlier positioning of Vision as a key FY27 growth product, alongside a target of about A$20 million in ARR. Beonic Vision launch is now being tested against actual customer adoption rather than remaining a roadmap item.
Profitability and recurring revenue hold up
Beonic reported Q1 total revenue of A$5.6 million, down 10.7% from the prior comparable period. Management attributed the entire shortfall to non-recurring revenue, which fell to A$1.3 million from A$2.0 million after the prior period included the first tranche of the Moroccan airports project.
The recurring base was more resilient. Quarterly recurring revenue rose 2.3% to A$4.4 million, representing 78% of total revenue, while ARR increased 1.8% to A$17.3 million. Beonic said currency movements reduced the reported figure, with ARR standing at A$17.9 million on a constant-currency basis. The company also secured A$3.5 million of renewals across 18 customers, including five international airports, compared with A$0.5 million in new contract wins and expansions across 16 customers.
Profitability improved despite the softer headline revenue number. EBITDA reached A$853,000, or a 15.1% margin, and unaudited gross margin rose to 83.0% from 78.4% in FY26. CEO Billy Tucker said the result reflected a higher-quality revenue mix and lower delivery costs (ASX:BEO). The quarter therefore presents a mixed operating picture: recurring revenue and margins moved higher, but new-business conversion was slower than expected.
Morocco and cash collections become near-term tests
The Moroccan Airports deployment is live at five of seven airports, with the remaining two regional sites in user acceptance testing. Delivery is expected during Q2 FY27, after which Beonic says the contract will move towards its full operating revenue contribution. A$7.3 million Moroccan airport contract was previously identified as a major FY26 contract win, making the final two sites important not only for revenue timing but also for the company’s near-term cash expectations.
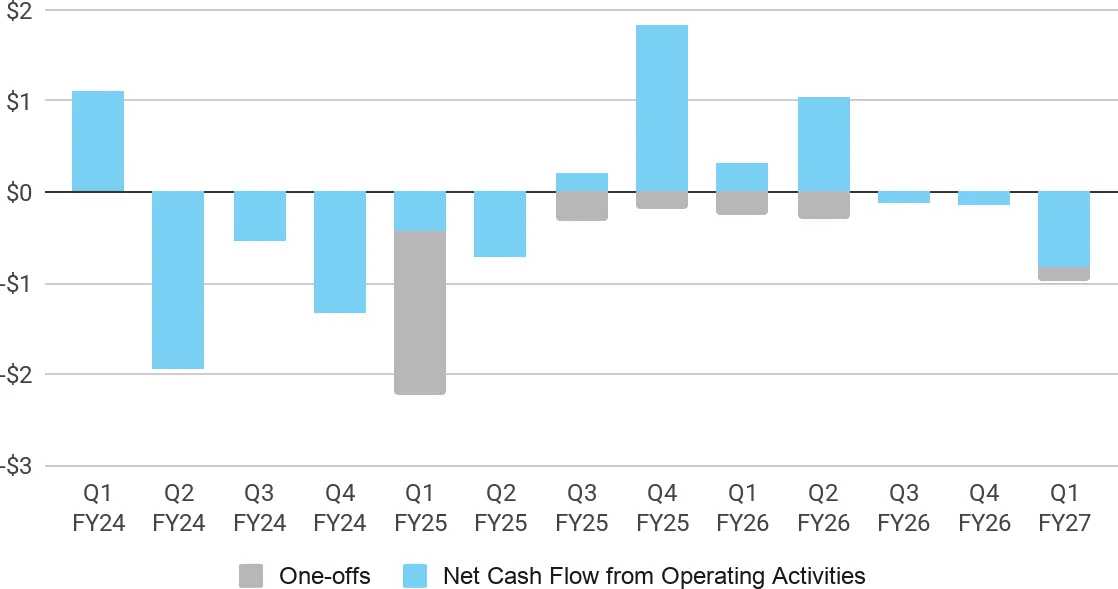
Beonic used A$987,000 in operating cash during the quarter and spent a further A$728,000 on investing activities, including A$723,000 on intellectual property. A A$683,000 equity inflow softened the impact, but cash still declined from A$2.671 million to A$1.633 million. The company reported September as cash-flow positive and said customer collections, including a major Middle East airport renewal signed during the quarter, are its immediate priority.
That leaves little room for execution slippage. The Appendix 4C calculates 1.7 quarters of available funding, with no unused finance facilities. Beonic said it does not currently plan to raise further cash and expects billings from the Abu Dhabi Airport renewal and Moroccan milestones to fund operations through FY27. The filing also records A$5.692 million of drawn financing facilities, including convertible notes and loans, adding a financing obligation to the collection and delivery timetable.
Get ASX:BEO news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Vision now has to convert early deployments into repeatable revenue while Morocco collections and cash generation carry the near-term funding burden.
Questions in the middle?
- Can the final two Moroccan airports move from user acceptance testing into revenue contribution during Q2 FY27?
- Will Vision’s airport, retail and transport evaluations convert into material recurring contracts?
- Are customer collections sufficient to restore cash generation before Beonic reaches the end of its stated 1.7-quarter funding estimate?
Sources
1-
Quarterly Activities/Appendix 4C Cash Flow Report (opens in a new tab)Verified company source. Beonic Ltd · 29 Oct 2026 · investorhub.beonic.com