Carbonxt’s contracted growth story clears A$22 million as Kentucky remains unfinished

Carbonxt is forecasting at least A$22 million of FY27 revenue after securing larger customer orders, but the growth plan remains tied to a delayed Kentucky facility and shareholder approval of a proposed balance sheet restructure. Cash stood at just A$0.7 million after a A$1.0 million operating outflow in the September quarter.
- FY27 revenue forecast of at least A$22 million, up 40% on FY26
- Larger WPS and Reworld orders underpin expected growth
- September quarter revenue fell to A$3.3 million during Minnesota relocation
- Kentucky kiln repairs and testing remain incomplete
- Stage 2 restructure could inject up to A$11 million and cut debt by about A$5 million
 Add us as a preferred source on Google
Contracted Orders Drive A$22 Million FY27 Target
Carbonxt Group Ltd (ASX:CG1) is aiming for a record FY27, with revenue expected to reach at least A$22 million, a 40% increase on FY26. The forecast is based on existing customer activity rather than any contribution from the delayed Kentucky facility, giving the company a clearer commercial target even as its largest expansion project remains unfinished.
The uplift is spread across several customers. Wisconsin Public Service has increased its activated carbon pellet order by 60% on FY26 volumes, while Reworld’s expanded agreement is expected to lift annual powdered activated carbon supply by about 25% and contribute roughly A$1.0 million in 2027. Carbonxt also points to a more than 30% increase under an extended principal-customer contract, worth approximately A$2.0 million of additional FY27 revenue, as well as orders from a new steel-sector customer.
The Reworld expansion, which adds four US waste-to-energy facilities from 1 January 2027, follows the company’s expanded Reworld agreement previously reported in October. Carbonxt says gross margins on the additional volume should remain around current performance. At Black Birch in Georgia, a roughly A$1.1 million mill installation is expected to double production capacity to about 12,000 tons by the third quarter of FY27.
Minnesota Move Hits September Revenue and Cash Flow
The near-term numbers were less flattering. September quarter revenue fell to A$3.3 million from A$4.0 million in the June quarter, while customer receipts declined to A$2.9 million from A$4.1 million. The relocation of pellet production from Arden Hills to a new Minnesota site removed about four weeks of production and deferred approximately A$0.8 million of pellet sales.
Net operating cash outflow was A$1.0 million, compared with a A$0.3 million inflow in the previous quarter. Carbonxt attributed the result to the lower sales, A$0.25 million of inventory built for deferred production and about A$0.25 million in one-off relocation costs. Cash and cash equivalents were A$0.7 million at 30 September, equivalent to 0.69 quarters of funding on the company’s reported cash-flow calculation.
The new Minnesota facility is now operating and is expected to reduce monthly operating costs by about US$10,000, while allowing lower-cost expansion. That benefit will need to emerge alongside the promised volume growth, rather than from the September quarter itself.
Kentucky Kiln Remains the Main Execution Risk
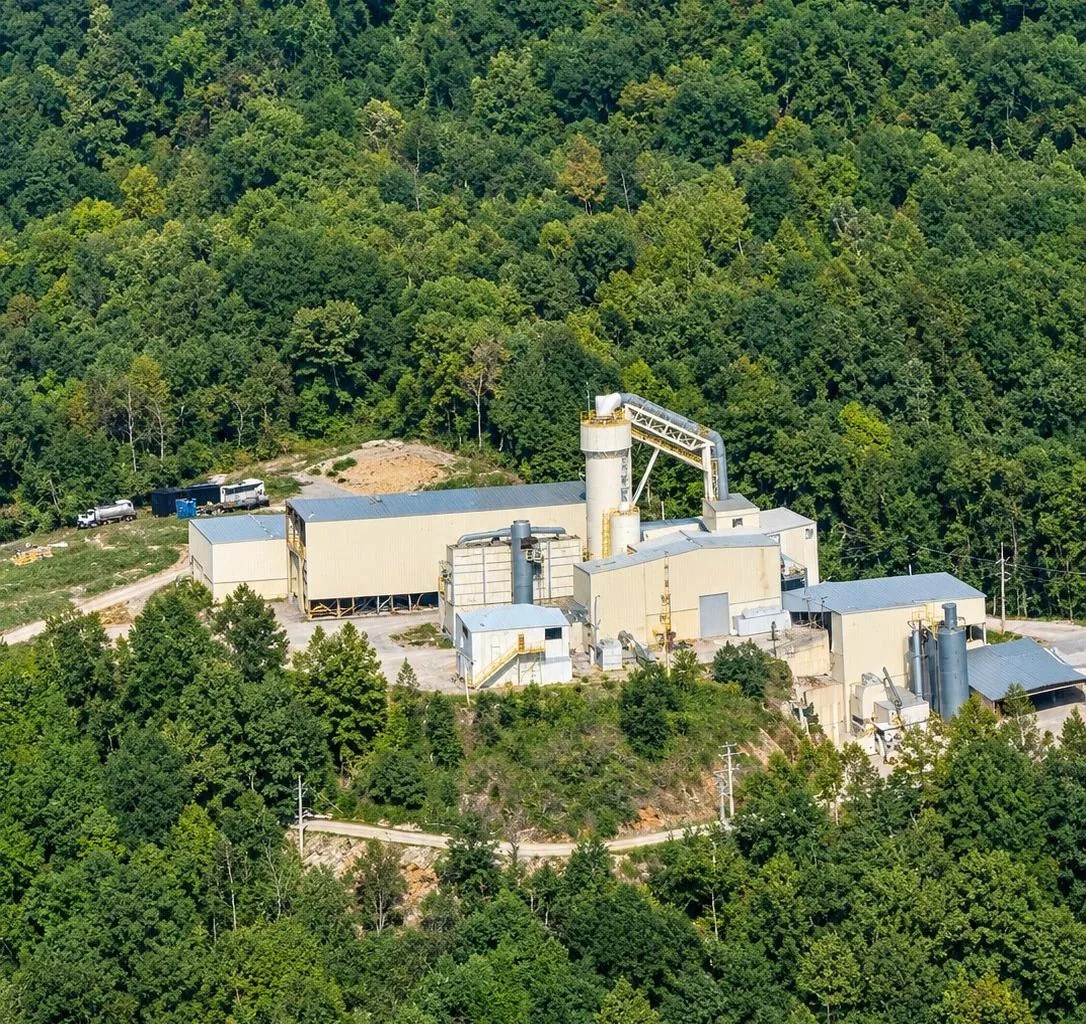
Carbonxt’s Kentucky facility has not yet reached the milestone required to unlock the next stage of the company’s funding plan. Replacement kiln parts were delayed until the week of 26 October after mechanical issues at the manufacturer, and repair and testing have now commenced. Construction was not completed during the September quarter, contrary to the company’s earlier expectation.
Once construction is complete, the project still requires commissioning, independent engineering certification and an initial US$1 million revenue milestone. Carbonxt says the facility could eventually increase group sales by about 200% over two years and open access to the larger liquid-phase activated carbon market, but those outcomes remain dependent on completion and successful operation.
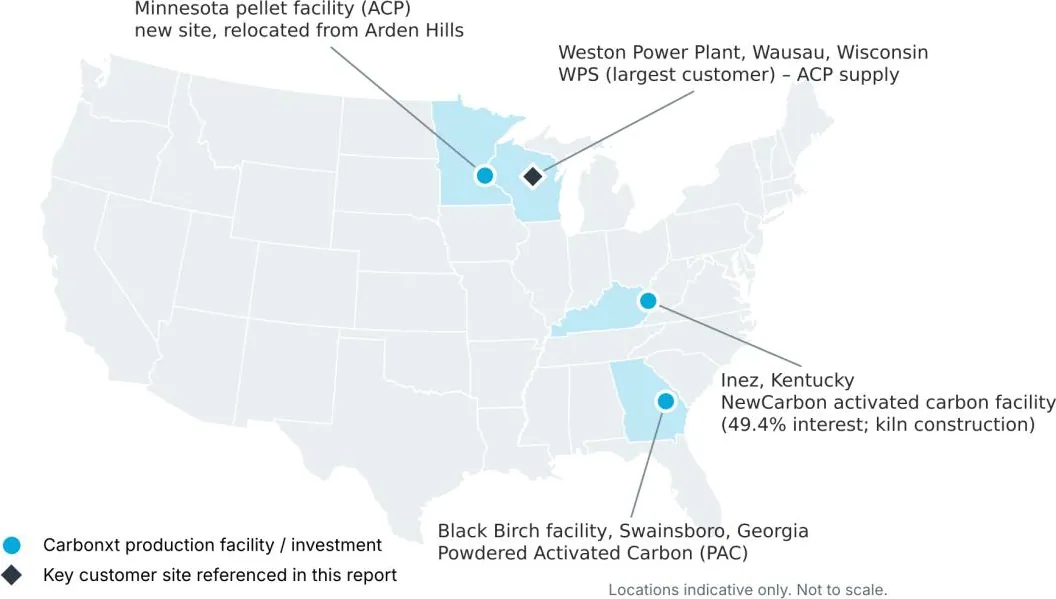
The company has invested a total of US$9.75 million in NewCarbon Processing, taking its ownership interest to 49.4%. That additional exposure increases the importance of the repair process, particularly while the company is also funding a A$1.1 million Black Birch capacity project from operating cash flow.
Shareholders Face a Funding Decision on 9 November
Stage 1 of Carbonxt’s balance sheet restructure is complete, including A$3.5 million of convertible notes comprising A$2.0 million in new cash from Phelbe and A$1.5 million from PURE set against senior debt and accrued interest. Phelbe has also provided a secured A$1.0 million loan, with A$0.5 million advanced during the quarter and a further A$0.5 million after quarter end.
Stage 2 could provide up to A$11 million of cash and reduce senior debt by approximately A$5 million, from A$15 million to about A$10 million. It is conditional on shareholder approval, a share price closing at or above A$0.09 for five consecutive trading days before 31 December, and Kentucky reaching operational status with the US$1 million revenue milestone.
Those proposals will be considered at the 9 November AGM, alongside resolutions that could allow Phelbe’s voting power to rise from approximately 12.3% to a maximum of 29.6%. The independent expert concluded that the proposed increase was not fair but reasonable to non-associated shareholders. The immediate question is therefore not simply whether Carbonxt can deliver its growth orders, but whether it can reach the Kentucky and capital milestones quickly enough to avoid the reported funding pressure becoming the dominant story.
Get ASX:CG1 news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Carbonxt has a substantial order-backed growth target, but the next quarter must show improved cash generation while Kentucky repairs and the conditional restructure remain unresolved.
Questions in the middle?
- Will the 9 November AGM approve the securities issues, Phelbe voting-power increase and early-conversion incentive?
- How quickly will Kentucky move from kiln testing to commissioning, certification and its initial US$1 million revenue milestone?
- Can Minnesota’s lower operating costs and larger customer orders convert the FY27 revenue target into sustained positive operating cash flow?
Sources
1-
Q1 FY27 Quarterly Activities Report & Appendix 4C (opens in a new tab)Verified source. Carbonxt Group Limited · 30 Oct 2026 · investorhub.cglimited.com.au