Carnavale clears Kookynie feasibility hurdle with A$104m cash flow case

Carnavale Resources has completed a bankable feasibility study for its 80%-owned Kookynie Gold Project, outlining an 18-month open-pit operation targeting 35.6koz of gold and A$104 million in pre-tax free cash flow. The economics are strong on paper, but funding, approvals, processing arrangements and a final investment decision remain ahead.
- A$104m pre-tax free cash flow at a A$6,000/oz gold price
- 35.6koz open-pit Ore Reserve from Swiftsure and Tiptoe
- A$24m peak funding requirement, excluding contingency
- Production targeted for the second half of 2027
- Underground development remains a scoping-study opportunity, not a reserve
 Add us as a preferred source on Google
Kookynie BFS sets out a short, high-margin open-pit plan
Carnavale Resources (ASX:CAV) has put a number on the first stage of its Kookynie development: A$104 million in undiscounted pre-tax free cash flow from an 18-month open-pit operation, based on a A$6,000 an ounce gold price. The bankable feasibility study supports a maiden 35.6koz Ore Reserve from the Swiftsure and Tiptoe pits, with production targeted for the second half of 2027 subject to approvals and a positive final investment decision.
The study models 220,000 tonnes of ore at an average grade of 5.0 grams per tonne, producing 35.6koz of gold at an all-in sustaining cost of A$2,721 an ounce. Pre-tax NPV8 is estimated at A$87 million and the pre-tax IRR at 417%, while the project is expected to repay its initial investment in month 10 of operations. The model assumes contract mining and an Ore Purchase Agreement or third-party processing pathway rather than construction of a processing plant.
The numbers are notably sensitive to gold prices, although the study remains cash-generative across the disclosed range. At A$5,000/oz, pre-tax free cash flow falls to A$72 million and NPV8 to A$59 million; at A$8,000/oz, those figures rise to A$170 million and A$143 million respectively. The economics described in the filing are therefore projections built around operating, funding and commodity-price assumptions, not realised returns.
Funding gap remains material before construction
The headline cash-flow figure sits alongside a more immediate financing task. Carnavale estimates peak funding of A$24 million, including A$2.4 million of pre-operating capital but excluding contingency. Its cash balance at 30 September was A$2.27 million, after quarterly operating and exploration outflows of A$721,000, and the company reported no drawn financing facilities.
The next development hurdles are practical rather than geological: finalising an Ore Purchase Agreement or toll-milling arrangement, selecting mining and haulage contractors, securing project funding and reaching FID. Carnavale says it has submitted the Mining Development and Closure Proposal, Native Vegetation Clearing Permit and Works Approval applications, with approvals expected in the first half of 2027. That timing leaves limited room between permitting and the stated production target.
The filing formalises the transition from the company’s earlier Kookynie mine plan, which had identified the same 18-month open-pit concept but left funding, approvals and processing arrangements unresolved. The BFS now provides a more detailed economic case, while those conditions remain live.
Underground upside is promising but not yet a reserve
Carnavale has not included underground mining in the BFS. Instead, it has applied updated cost and revenue assumptions to the underground resource from its October 2025 scoping study, estimating A$111 million of pre-tax free cash flow at an AISC of A$2,875/oz from a 47koz production target. That work remains at scoping-study confidence, carries no underground Ore Reserve and cannot be treated as equivalent to the completed open-pit feasibility study.
The company says the open pits could generate cash to support a later underground transition, with 11koz of high-grade resources beneath the Swiftsure BFS pit excluded from the current open-pit design. Technical work to test the underground potential is expected to be completed in the first half of 2027. Whether that becomes a mine plan will depend on further engineering, evaluation and funding.
Drilling and metallurgy add support, not certainty
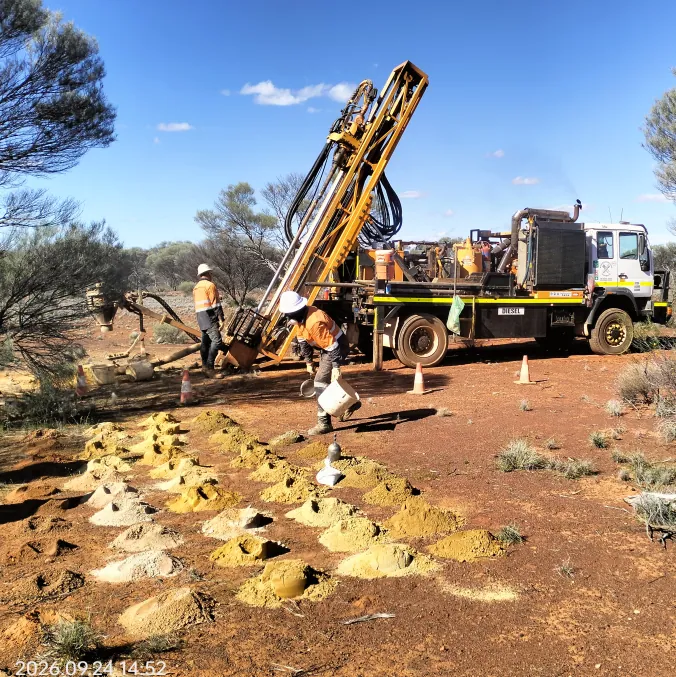
Exploration has continued alongside the development work. More than 4,000 metres of aircore drilling is testing the greenstone-granite boundary about 2km northwest of Swiftsure, while more than 3,000 metres of sterilisation drilling has tested proposed infrastructure areas. Results from the sterilisation programme are expected in about six weeks, and the exploration targets remain untested or underexplored rather than an addition to the current Ore Reserve.
Metallurgical testwork supplied a useful foundation for the processing strategy, with cyanidation recoveries above 96% across oxide, transitional and fresh samples and recoveries of roughly 98% to 99% at the 106-micron grind size. The company says the samples showed no issues with preg-robbing, refractory mineralisation or deleterious elements, supporting the proposed use of a conventional Goldfields CIL facility. That strengthens the toll-treatment case, but a processing agreement still has to be negotiated.
Get ASX:CAV news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Kookynie has moved from feasibility modelling to a defined development pathway, but the next value test is whether Carnavale can turn a A$24 million funding requirement and pending approvals into a funded FID before the 2H27 production target.
Questions in the middle?
- Can Carnavale secure project debt, equity or other funding without materially changing the economics or ownership structure?
- Will the company finalise a commercially attractive Ore Purchase Agreement or toll-treatment arrangement?
- Do the 2027 underground studies and exploration results add mineable ounces beyond the 35.6koz open-pit reserve?
Sources
1-
Quarterly Activities/Appendix 5B Cash Flow Report (opens in a new tab)Verified company source. Carnavale Resources Limited · 29 Oct 2026 · carnavaleresources.com