Cyprium funds Nifty growth as first cathode target nears

Cyprium Metals has secured an approximately A$20.7 million institutional placement and outlined a proposed debt extension that could take its staged Nifty funding package to A$83 million. The capital is aimed at advancing the open-pit feasibility study, infrastructure upgrades and a major SXEW expansion while first cathode production remains targeted for Q4 2026.
- A$20.7 million institutional placement at A$0.330 per share
- Proposed US$40 million Nebari debt extension remains conditional
- Up to A$83 million package includes a proposed A$5 million SPP
- Funds target Nifty DFS, infrastructure and SXEW expansion
- First copper cathode remains targeted for Q4 2026
 Add us as a preferred source on Google
Institutional Placement Funds Nifty’s Next Stage
Cyprium Metals Limited (ASX:CYM) has raised approximately A$20.7 million from institutional investors at A$0.330 a share, giving the Nifty Copper Complex redevelopment a firmer financial base as it approaches first cathode production. The issue price is 9.6% below Cyprium’s last traded price of A$0.365 and 14% below its 10-day volume-weighted average price.
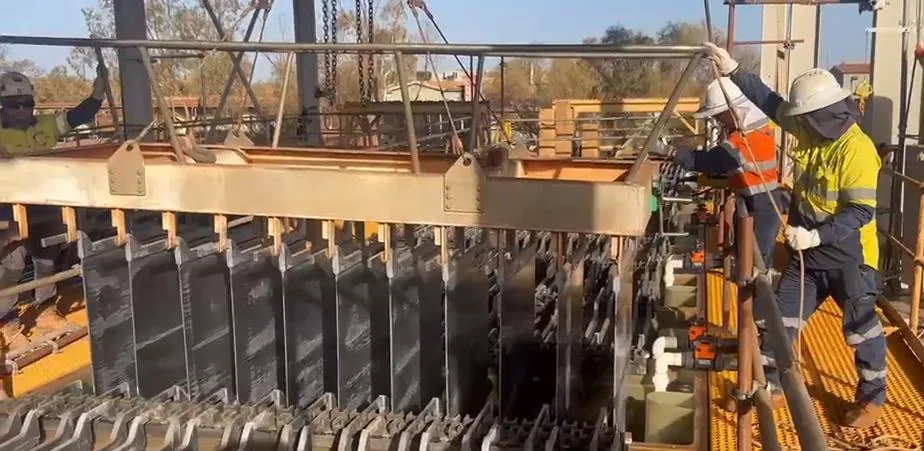
The placement will issue approximately 62.8 million shares, taking the company’s pro-forma share count to 640.9 million before any share purchase plan allotment. Cyprium also intends to offer eligible shareholders up to A$5 million of shares at the same price, although the SPP is not underwritten and may be scaled back or accept oversubscriptions.
First Cathode Target Supports Expansion Push
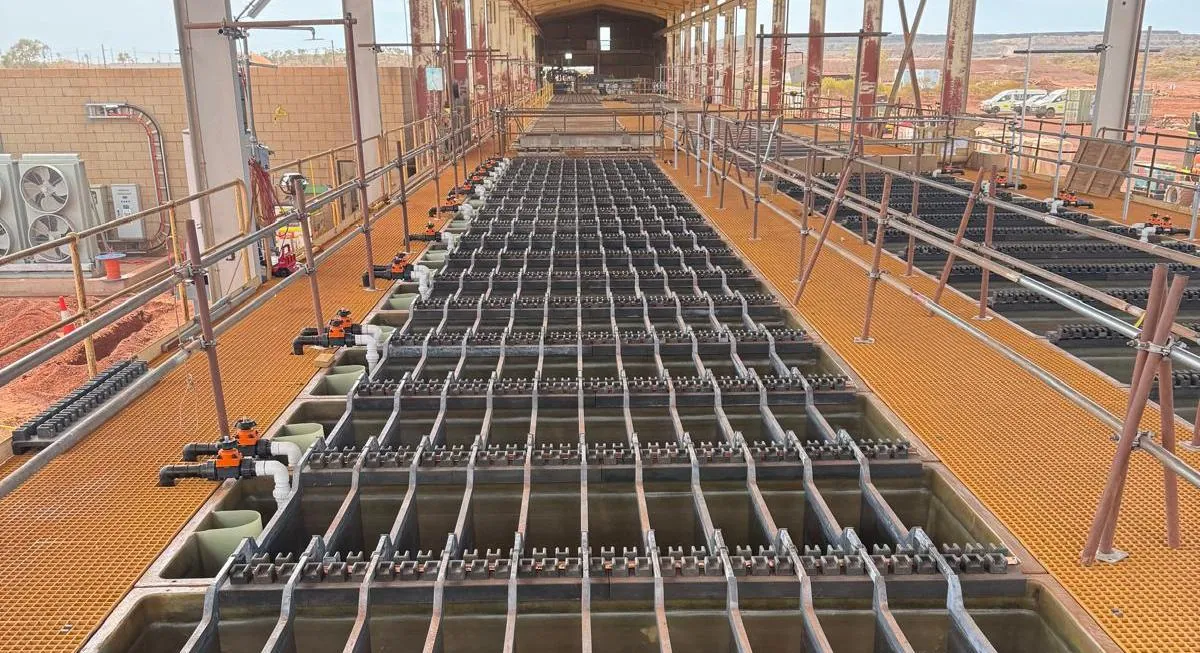
The funding arrives with Cyprium’s heap leach restart moving from commissioning towards production. The company says the SXEW plant is in its final weeks before commissioning and remains on track for first copper cathode in Q4 2026, following the Nifty leach commissioning milestones reported earlier this month.
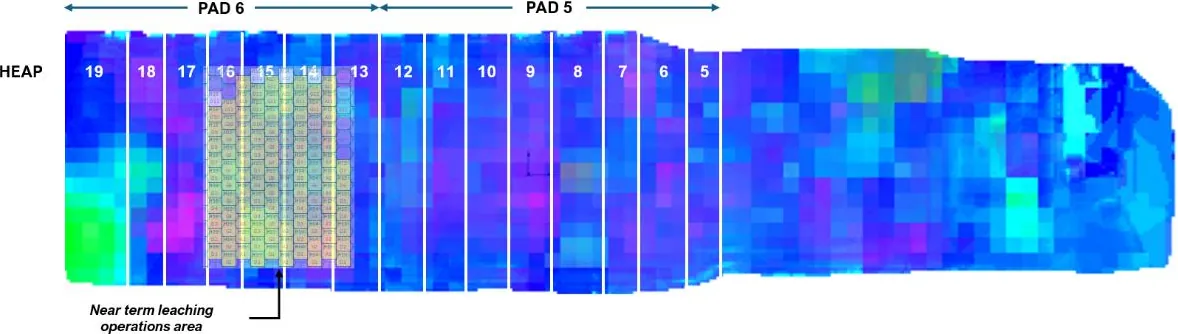
Phase 1 is designed to produce about 6,000 tonnes a year of cathode by reprocessing material already on the heap leach pads. Cyprium wants to use the initial restart as a platform for a larger expansion, with studies examining restoration of the SXEW plant to more than 20,000 tonnes of installed annual capacity. That capacity figure is not a production target and would still depend on feed, grades, recoveries, plant availability and other operating factors.
Nebari Debt Extension Remains Conditional
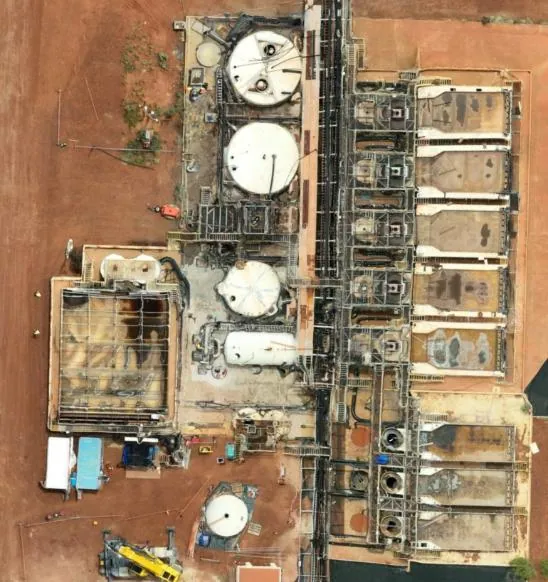
Cyprium has signed a term sheet with existing lender Nebari for up to US$40 million of additional senior secured debt. The proposed facility comprises a US$25 million Tranche 2 for DFS work, SXEW design, long-lead items and early works, followed by a US$15 million Tranche 3 intended to fund execution of the SXEW expansion.
The debt is not yet fully committed. Both tranches require binding loan documentation and lender due diligence, while Tranche 3 also depends on a final investment decision for the SXEW expansion and a loan-to-value ratio below 0.3 times. The proposed terms include quarterly interest payments, a 2.5% original issue discount, a 2% arrangement fee, a 0.5% annual administration fee and warrants. Repayments of 12.5% of drawn amounts would begin after the December quarter of 2027, with maturity scheduled for 31 December 2029.
Funding Targets DFS and Site Infrastructure
Cyprium’s indicative A$77.8 million sources-and-uses table excludes the SPP and assumes full drawdown of both proposed Nebari tranches. It allocates A$12 million to the open-pit DFS, A$14 million to infrastructure including the aerodrome, access road and power generation, A$41 million to SXEW expansion and early works, and A$10.8 million to working capital.
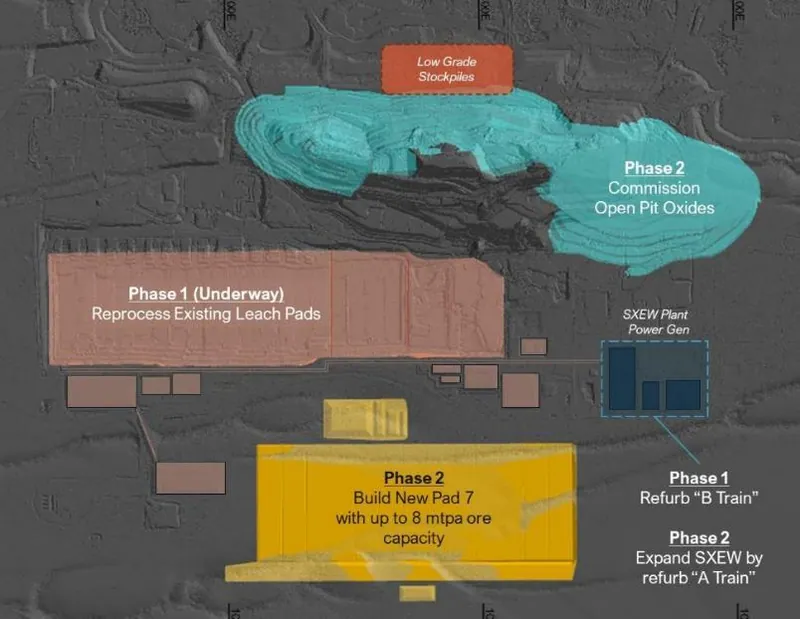
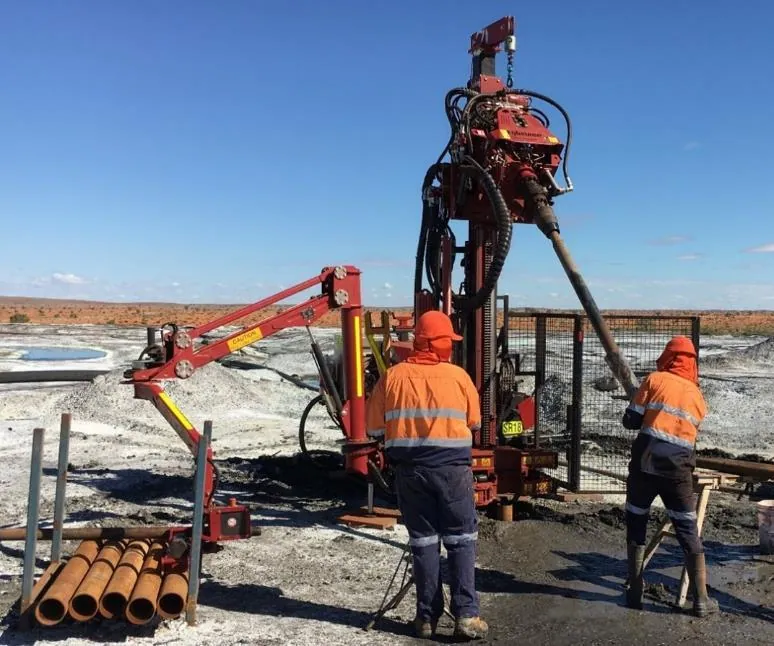
That ambition builds on the company’s earlier SXEW capacity expansion plans, which contemplated growing from the initial approximately 6,000-tonne phase towards roughly 20,000 tonnes of installed capacity. Cyprium is also running a roughly 10,000-metre drilling programme and says its DFS is targeted for completion in the first half of calendar 2027.
The financing improves Cyprium’s ability to progress several workstreams at once, but it also increases the importance of execution and funding conditions. After the placement, the company presents A$58.3 million of cash against A$39 million of senior debt and A$36 million of convertible notes, or pro-forma net debt of A$16.7 million, before the proposed debt extension and excluding the SPP.
Get ASX:CYM news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The near-term test is whether commissioning converts the new funding into first cathode, while the longer-term question is whether conditional debt can support expansion without placing too much weight on the balance sheet.
Questions in the middle?
- Will Cyprium complete Nebari documentation and draw Tranche 2 on the expected timetable?
- What production rates and recoveries will the refurbished SXEW plant achieve after first cathode?
- Can the open-pit DFS support a final investment decision for SXEW expansion while new debt and warrant obligations remain manageable?
Sources
2-
Capital Raise Presentation (opens in a new tab)Verified company source. Cyprium Metals Limited · 30 Oct 2026 · investorhub.cypriummetals.com
-
Up to A$83M funding to Accelerate Next Stages of Growth (opens in a new tab)Verified company source. Cyprium Metals Limited · 30 Oct 2026 · investorhub.cypriummetals.com