Kalamazoo’s Mt Olympus drilling gives Ashburton a larger development runway

Kalamazoo Resources has reported a strong quarter at Ashburton, where high-grade Mt Olympus drilling is feeding an updated resource and pre-feasibility study. The company also secured A$18 million in placements, although its September cash balance was just A$670,000 before the post-quarter raise.
- 38 Mt Olympus intercepts above 50 gram-metres, including 16 above 100 gram-metres
- Updated Mt Olympus Mineral Resource Estimate expected in Q4 2026
- Pre-feasibility study targeted for April 2027
- A$18 million raised through two placements, including A$10 million at a 29% premium
- September quarter ended with A$670,000 cash and 0.1 quarters of funding under the Appendix 5B measure
 Add us as a preferred source on Google
Mt Olympus drilling strengthens Ashburton’s development case
Kalamazoo Resources Limited (ASX:KZR) is moving Ashburton into a more consequential phase: the company now has a denser geological dataset, a pipeline of growth drilling and fresh capital aimed at turning Mt Olympus from a resource story into a mine-planning exercise.
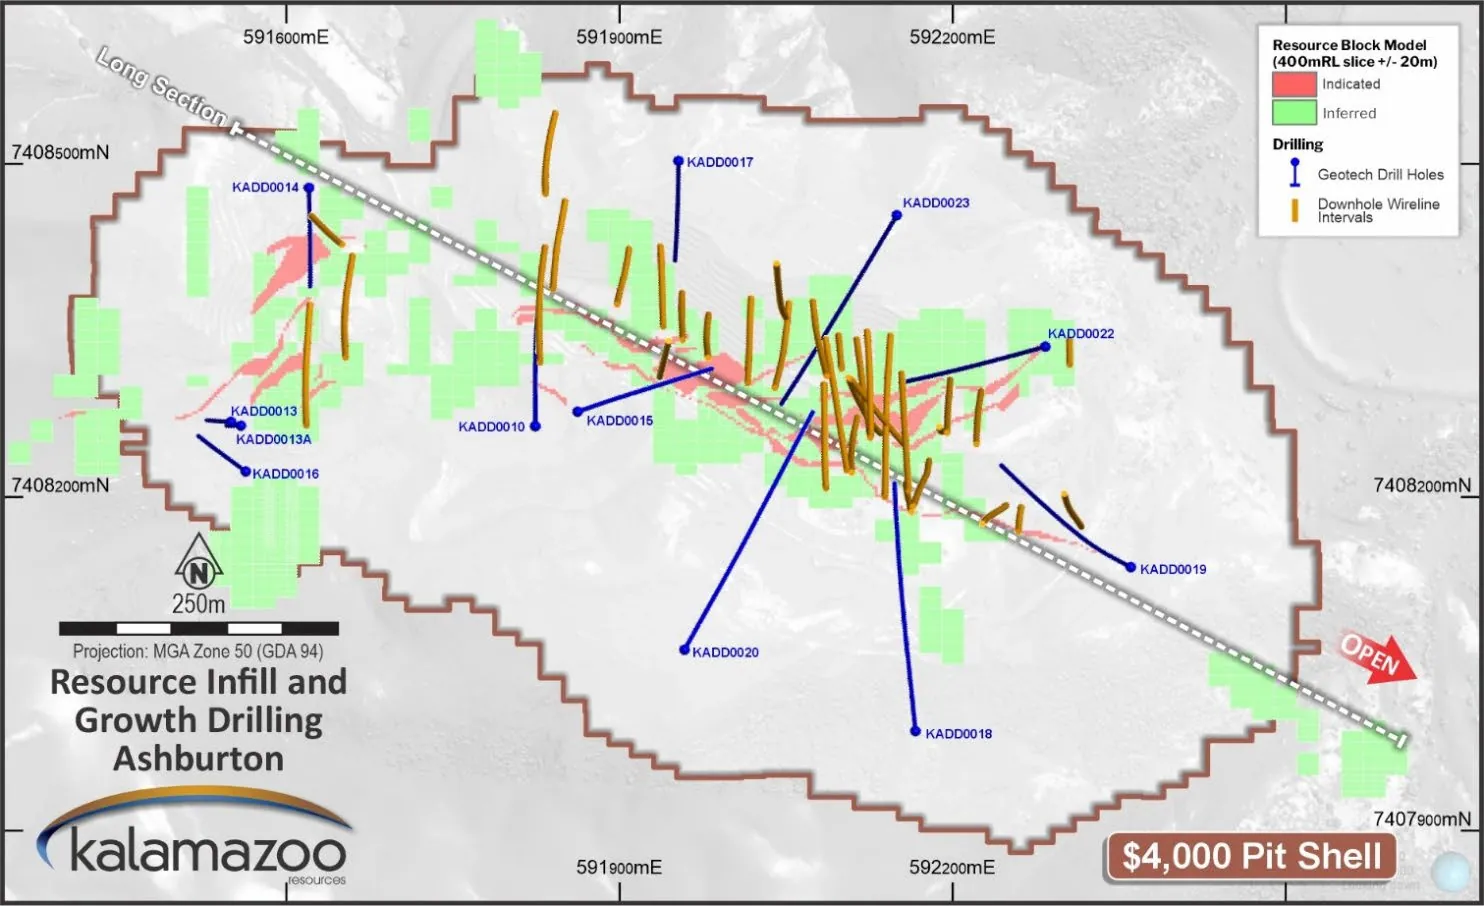
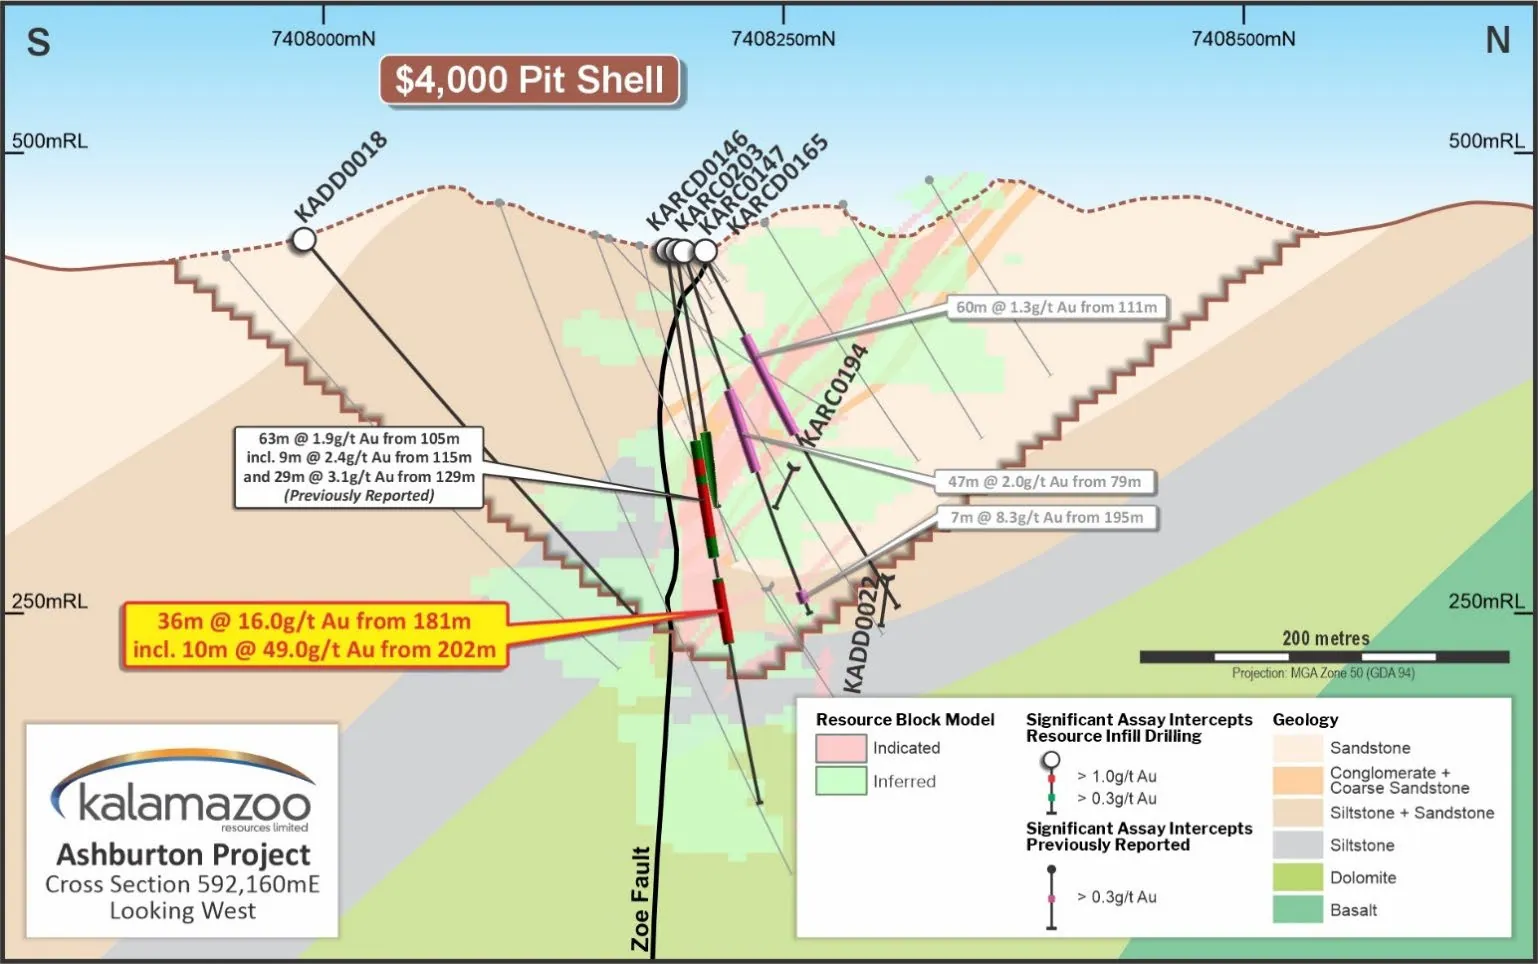
The headline drilling numbers are difficult to ignore. Kalamazoo’s 72-hole, 13,726-metre Mt Olympus resource-definition program delivered 38 intercepts above 50 gram-metres, including 16 above 100 gram-metres. Standout results included 36 metres at 16 grams per tonne gold, including 10 metres at 49 grams per tonne, alongside 20 metres at 19 grams per tonne, 74 metres at 4.1 grams per tonne and 50 metres at 4.9 grams per tonne.
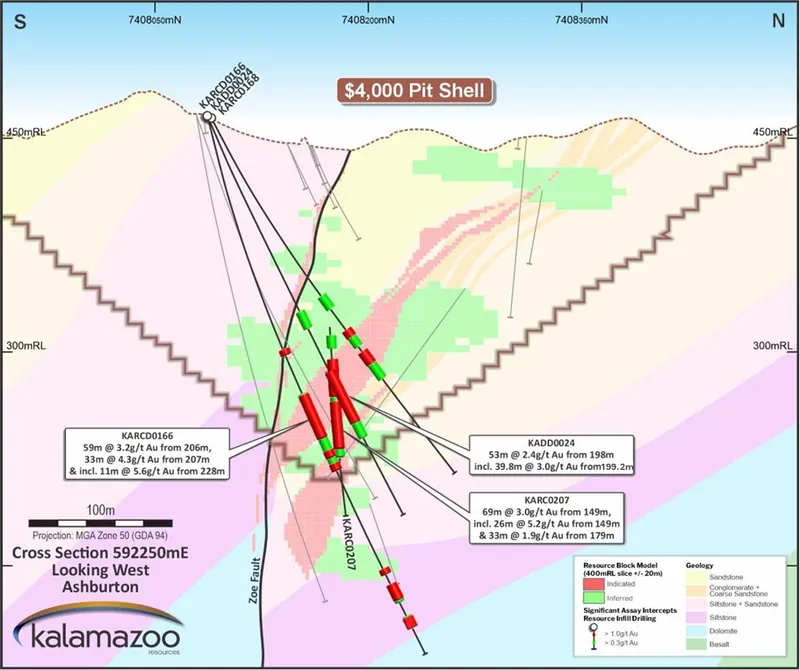
The program reduced spacing to about 20 metres by 20 metres across key areas and confirmed mineralisation beyond the existing resource envelope while remaining within the conceptual open-pit shell used in the Ashburton Scoping Study. That does not establish an economic reserve, but it gives the company more information to work with as it updates the resource model and mine plan. The results build on the earlier Mt Olympus high-grade drilling, which had already identified broad and high-grade zones ahead of the resource update.
Resource update and feasibility study set the next tests
Kalamazoo expects the updated Mt Olympus Mineral Resource Estimate in the fourth quarter of 2026. It will incorporate roughly 25,000 metres of drilling since the previous 2022 estimate, more than 28,000 sulphur assays, 12 geotechnical holes totalling 2,662 metres and about 6,700 metres of downhole wireline logging.
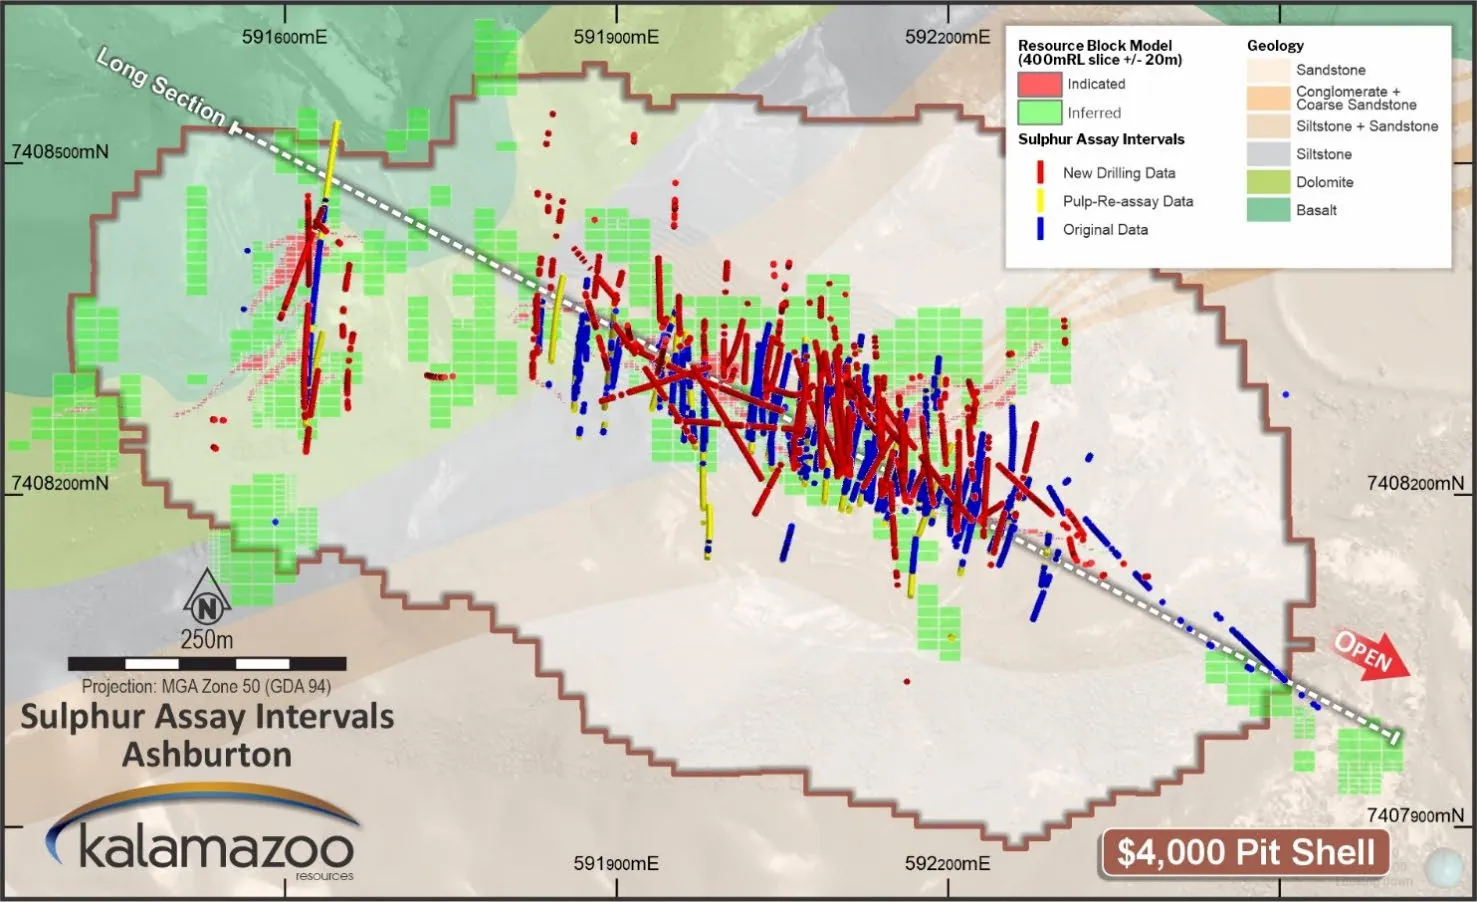
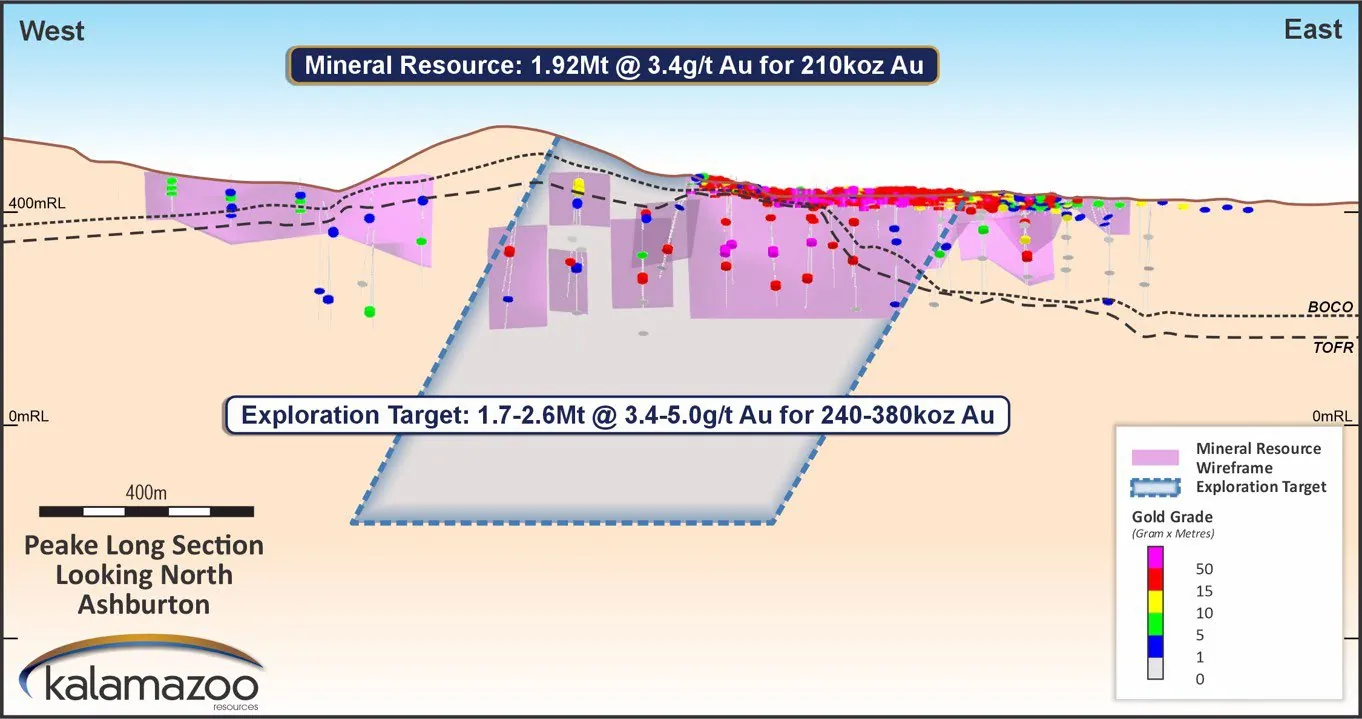
Growth drilling has also begun beneath Mt Olympus and down-plunge of the conceptual pit, while work at Peake is testing extensions below its historical open pit. Peake currently carries a resource of about 1.92 million tonnes at 3.4 grams per tonne for 210,000 ounces of gold, although the company’s larger exploration target remains conceptual and cannot be treated as a Mineral Resource.
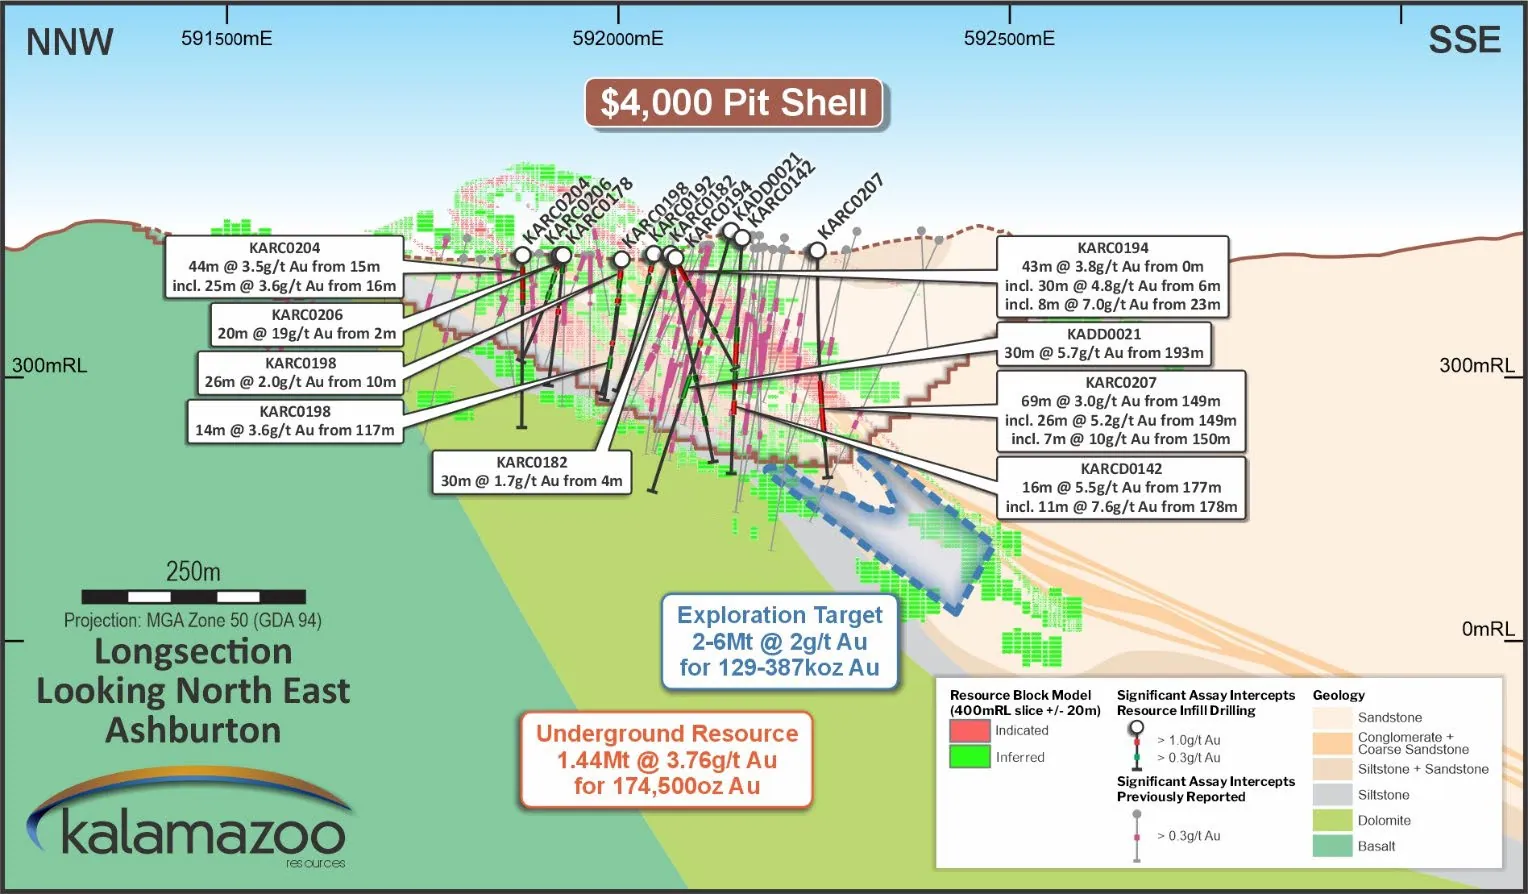
The pre-feasibility study is targeted for completion in April 2027. Kalamazoo says the updated resource and ongoing drilling will feed mine optimisation, future ore-reserve estimation and project economics. The central question is therefore no longer whether Mt Olympus has impressive intersections, but how much of that mineralisation can survive the conversion from drill results to a defined, financeable mine plan.
Capital raising eases the immediate funding pressure
Kalamazoo completed an oversubscribed A$8 million placement in July at A$0.12 a share, then announced firm commitments for a further A$10 million placement at A$0.18 a share, a 29% premium to the last closing price and a 27% premium to the 15-day VWAP used for the announcement. The second raise includes A$7.84 million from Muqasab SPV Holdings, which is expected to become a 9.9% strategic shareholder on completion, while YT International’s holding is expected to rise from about 6.6% to 8.5%.
The placement is intended to fund resource-growth drilling, the updated resource, the Ashburton PFS, early feasibility work and an accelerated evaluation of Xanadu as a potential second development opportunity. It follows the A$10m premium placement, which was reported as strategic backing for Ashburton drilling, feasibility work and Xanadu evaluation.
September cash balance highlights execution risk
The cash-flow statement provides a less comfortable counterpoint to the drilling narrative. Kalamazoo spent A$8.14 million on exploration and evaluation during the quarter, with total relevant outgoings of A$8.787 million. After the July placement and other cash movements, cash and equivalents stood at A$670,000 on 30 September, which the Appendix 5B calculated as 0.1 quarters of funding with no unused finance facilities.
The company said it did not expect the quarter’s spending rate to continue because drilling activity is expected to reduce after the Mt Olympus program and PFS work. It also pointed to the post-quarter A$10 million placement as the basis for continuing operations and meeting its objectives. The timing of that capital, its completion and the pace of expenditure will matter as much as the next batch of assays.
Mt Piper expands the exploration portfolio
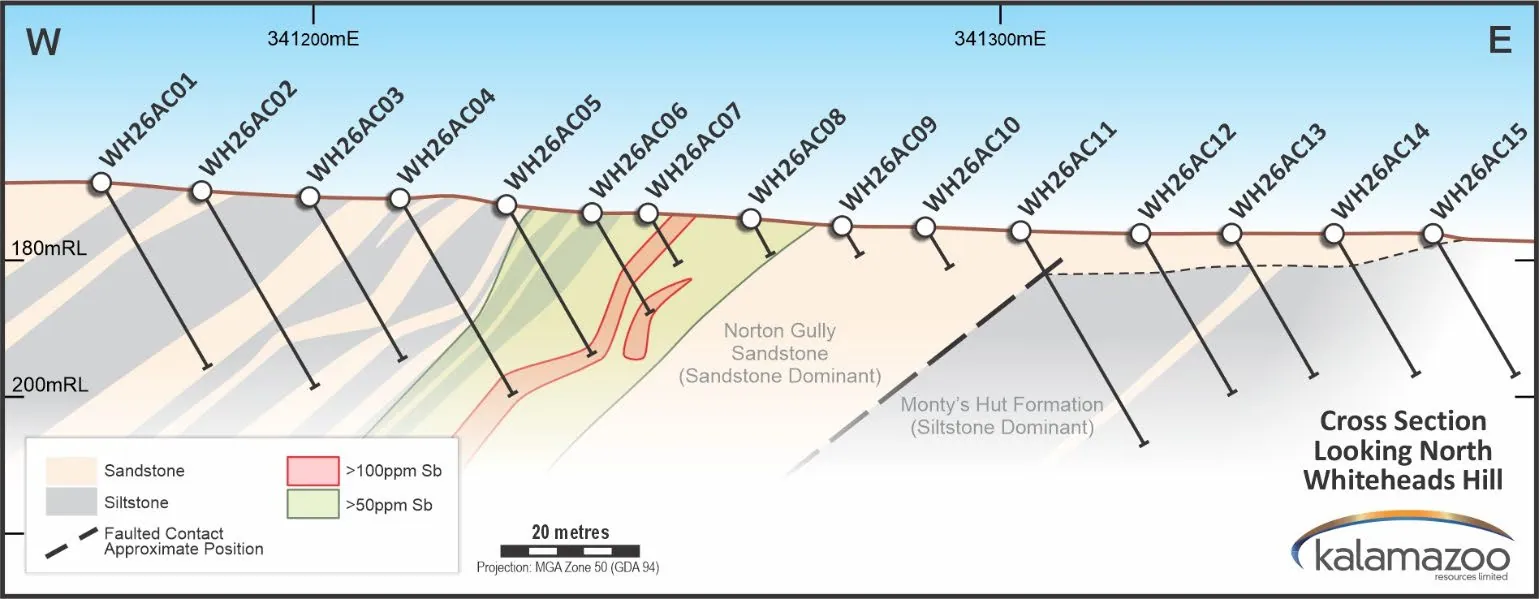
Outside Ashburton, Kalamazoo expanded its 100%-controlled Mt Piper gold-antimony position in Victoria to 1,574 square kilometres and secured continuous coverage over a 15-kilometre structural corridor through Whiteheads Hill. Reconnaissance aircore drilling there identified anomalous antimony and gold, including a three-metre zone above 100 parts per million antimony with a peak of 155 parts per million and gold of up to 68 parts per billion. The company characterises those results as sub-economic, making the project an exploration option rather than a near-term development asset. The expanded ground position and early results were detailed in the 15km Mt Piper corridor coverage.
Get ASX:KZR news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Kalamazoo now has the data and announced capital to push Ashburton forward, but the Q4 resource update and April 2027 PFS must convert geological promise into credible mine economics.
Questions in the middle?
- How much will the updated Mt Olympus resource increase, and how much material will convert into mineable inventory?
- Will the A$10 million placement complete on the proposed terms and provide sufficient funding through the PFS?
- Can Xanadu or Peake emerge as a meaningful second development opportunity without diluting focus from Mt Olympus?
Sources
2-
Quarterly Cashflow Report (opens in a new tab)Verified source. Kalamazoo Resources Limited · 30 Oct 2026
-
Quarterly Activities Report (opens in a new tab)Verified source. Kalamazoo Resources Limited · 30 Oct 2026