Monvia adds Capgemini as sales pipeline expands after $8m cash quarter

Monvia reported $8.0 million in cash at the end of Q1FY27 and says its sales pipeline expanded, while a new Capgemini teaming arrangement aims to accelerate client opportunities. The quarter also brought $1.6 million of product investment and a fully drawn $6.0 million secured debt facility.
- $1.0 million adjusted operating cash flow, versus $0.564 million statutory operating cash outflow
- $7.992 million closing cash and a fully drawn $6.0 million loan facility
- Capgemini teaming arrangement announced after quarter-end
- $1.6 million invested in product development, with $1.0 million capitalised
- Management says trading performance remains in line with expectations
 Add us as a preferred source on Google
Capgemini arrangement targets new client opportunities
Monvia Limited (ASX:MNV) has put a large systems integrator alongside its expanding sales pipeline, with a teaming arrangement with Capgemini announced after the September quarter. The companies will collaborate on new business opportunities, according to Monvia, which said the agreement should accelerate its go-to-market strategy. No contract value, customer win or guaranteed revenue was disclosed.
The arrangement arrives as Monvia pursues its stated financial-year objective of winning a new major client. Managing Director Simon Bright said the company was “confident” the partnership would materially expand its sales ecosystem. That remains an ambition rather than a reported outcome: the quarter’s announcement records pipeline expansion, but not a signed major customer arising from the relationship.
Monvia’s first quarter as an ASX-listed company also included the launch of an AI Claims Summarisation tool, which it plans to sell as an add-on to its Life Claims and Group Life Claims modules. The company continued extending its claims platform for new distribution channels and said it was embedding AI in internal operations while expanding offshore capability.
Cash balance strengthened by IPO funding
Cash stood at $7.992 million on 30 September, up from $5.642 million at the start of the quarter. The movement included $17.489 million of equity proceeds, partly offset by $12.5 million used to redeem Series B preference shares, $1.077 million of equity-issue costs, $994,000 of investing outflows and a $564,000 statutory operating cash outflow.
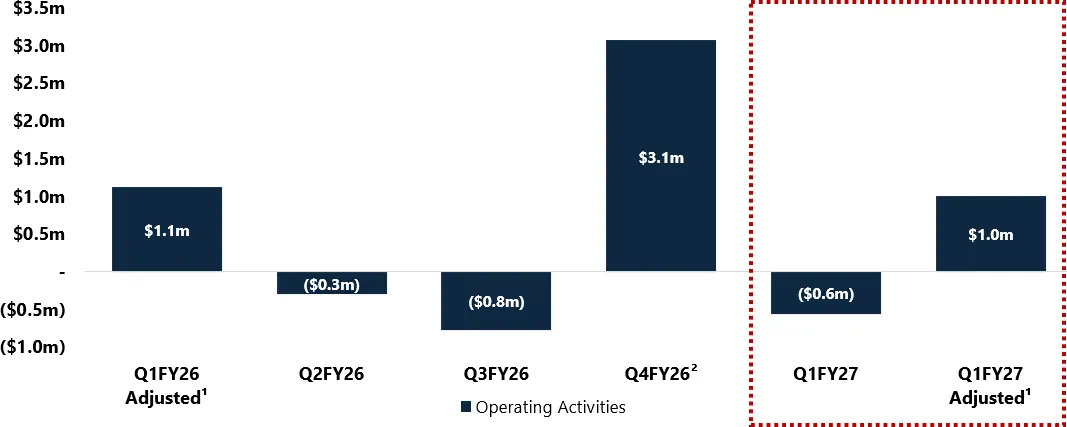
Monvia presents an adjusted operating cash flow figure of $1.0 million after excluding one-off and timing-related payments, including IPO and restructuring costs, an additional income-tax instalment and the cash-flow transition associated with Payday Super. The distinction matters: the statutory Appendix 4C figure was negative, while cash receipts can also move between quarters because many customer contracts are billed annually in advance. The company says its adjusted measure is intended to remove those unusual or timing-related effects.
Product development absorbed $1.6 million during the quarter, of which $1.0 million was capitalised, as investment accelerated in the Group and Legacy Life Claims modules. Monvia expects that investment to reduce in the second half of FY27. Its earlier ASX listing and IPO raised $17.5 million, providing the funding base reflected in this quarter’s cash movement.
Debt is fully drawn ahead of 2027 maturity
The balance sheet is not debt-free. Monvia’s $6.0 million loan facility is fully drawn, secured by a first-ranking general security over group assets and carries fixed interest of 12% a year, payable monthly. It matures on 31 August 2027, leaving the company with no unused financing facilities at quarter-end.
Management said trading performance remained in line with expectations and plans to provide an update at the upcoming annual general meeting. The next test is whether the larger sales ecosystem and Capgemini relationship convert into a major client win before product investment eases in the second half. Until then, the pipeline is a growth signal, not yet a revenue result.
Get ASX:MNV news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Monvia has cash to fund its stated plans, but the investment case now turns on converting pipeline activity and the Capgemini relationship into contracted revenue while managing a fully drawn 12% debt facility.
Questions in the middle?
- When will Monvia report a major client win from its expanded sales pipeline or Capgemini relationship?
- How much of the $1.6 million quarterly product investment will translate into recurring revenue and lower spending in H2FY27?
- How will Monvia address the $6.0 million facility before its 31 August 2027 maturity?
Sources
1-
Quarterly Activities Report - 30 September 2026 (opens in a new tab)Official market announcement. Monvia Limited · 30 Oct 2026 · monvia.io