NMR’s production surge faces funding and going concern pressure

Native Mineral Resources’ first full year as a gold producer delivered A$24.1 million in revenue and a late-year production surge, but the balance sheet remains under acute pressure. The ASX-listed miner reported a A$34.8 million loss, negative operating cash flow and a material uncertainty over its ability to continue as a going concern.
- 3,561.7oz of gold produced in FY2026
- A$24.1 million first-year production revenue
- A$34.8 million net loss and A$13.9 million operating cash outflow
- A$1.9 million net asset deficiency and A$36.5 million current asset shortfall
- FY2027 hinges on production growth, debt reduction and further funding access
 Add us as a preferred source on Google
First Production Year Delivers Revenue, But Not Financial Breakeven
Native Mineral Resources Holdings Limited (ASX:NMR) has completed its transition from developer to gold producer, but its first year of sales came with a stark financial qualification: the group is still losing cash and relying on external support to fund operations. The Blackjack operation produced 3,561.7 ounces of fine gold across 75 smelts in FY2026 and generated A$24.1 million in revenue, yet the audited result was a A$34.8 million loss after tax.
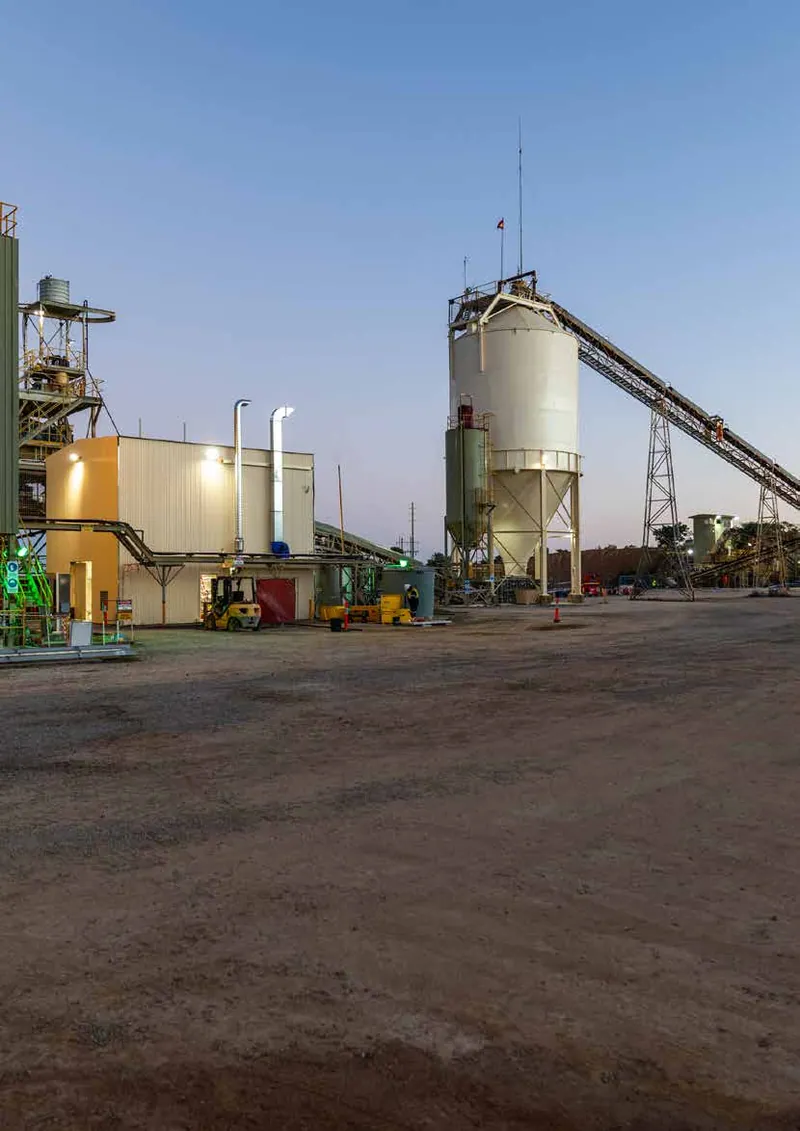
Operating cash flow was negative A$13.9 million, while cash at 30 June 2026 stood at just A$174,778. Total liabilities rose to A$55.9 million against A$53.9 million of assets, leaving NMR with a net asset deficiency of A$1.9 million. The company also reported a net current asset deficiency of A$36.5 million.
Blackjack Production Accelerates Into FY2027
The operational story improved sharply as FY2026 progressed. Throughput rose from 32.2 tonnes per hour in the September quarter to 39.1 tonnes per hour in the June quarter, while June delivered record monthly production of 763.8 ounces and plant recovery of 96.3%. Reconciled head grade climbed from 0.38 grams per tonne in April to 0.93 grams per tonne in June.
That momentum carried into the September quarter, which delivered 2,330.2 ounces of fine gold, roughly 65% of the full FY2026 total in three months. Mill availability exceeded 98% in each month of the quarter, and August produced 1,080.5 ounces at a record 1.38 grams per tonne reconciled head grade. The improvement is consistent with the company’s recent production quarter improvement reported in October, although the annual report’s figures run only to September.
Ore Pipeline Expands Beyond Blackjack
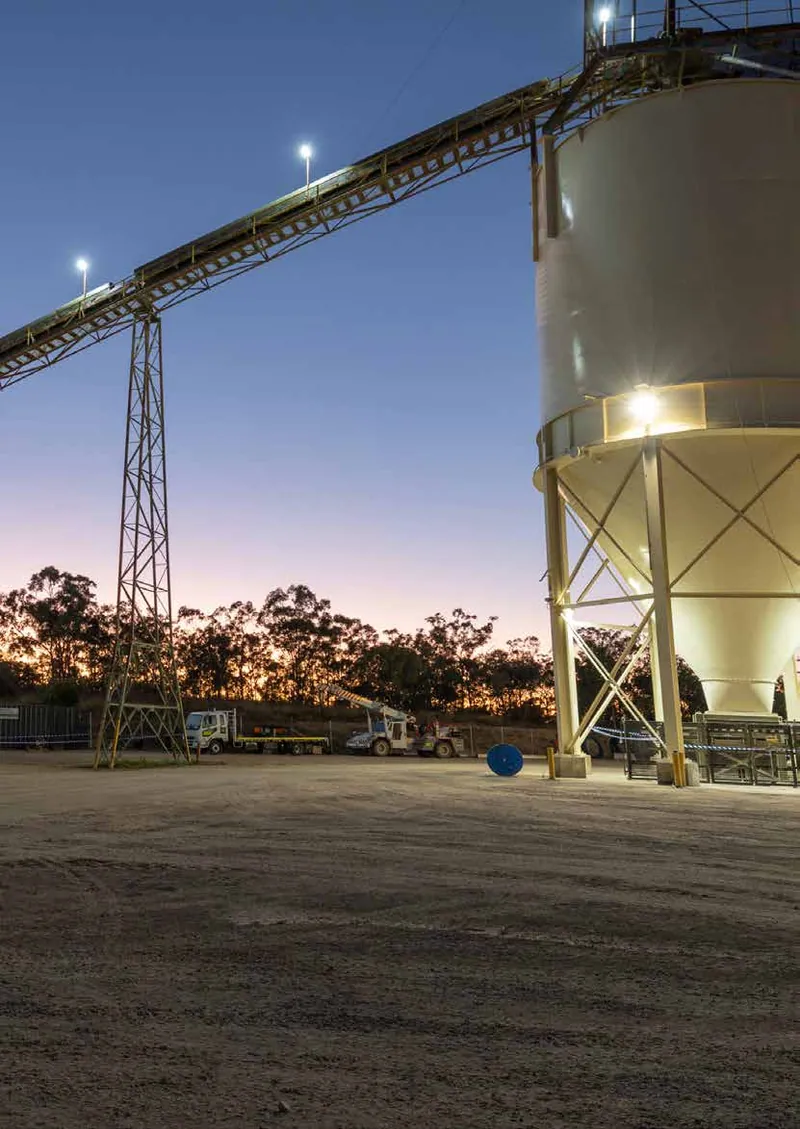
NMR is attempting to turn the 340,000-tonne-per-year Blackjack carbon-in-leach plant into a regional processing hub. Ore from Blackjack South and Mid pits was supplemented by legacy Far Fanning stockpiles and, from May 2026, Podosky ore supplied under the Haoma Mining joint venture. Around 125,000 tonnes had been mined at Podosky by year end, with approximately 6,400 tonnes processed.
The company has since added a second nearby growth option through its Stockholm arrangement with Citigold, giving NMR exclusive rights to drill and, if results support development, mine and process ore at Blackjack. The plan remains conditional on drilling results and approvals. At Blackjack North, early drilling returned intersections including 19 metres at 3.09 grams per tonne gold and 34 metres at 1.81 grams per tonne.
Funding Structure Leaves Little Room for Execution Errors
The central financial risk is not hidden in the accounts. NMR used a A$10 million placement, option exercises, convertible securities from Lind Global Fund III and related-party facilities associated with Managing Director Blake Cannavo to fund the transition and Podosky rights. Shares on issue increased from 918.3 million to 1.099 billion during the year.
At year end, NMR carried A$6.6 million of current convertible security liabilities and A$16.5 million of borrowings. After year end, it drew a further A$3.5 million convertible note from Lind and borrowed A$2.1 million from Yogi Bear Holdings, repayable in October 2026. Collins St repayments also fell behind schedule after year end, although management said the lender had not exercised its default rights and had shown flexibility over timing.
Auditor Highlights Material Going Concern Uncertainty
HLB Mann Judd gave an unmodified audit opinion but separately drew attention to a material uncertainty regarding going concern. The directors’ forecasts depend on continued production growth, access to further debt or equity funding, support from financiers and related parties, and the company’s ability to convert higher grades and plant availability into sustained cash generation.
The risk is particularly significant because NMR’s key assets are already carrying substantial obligations. The company reported A$45.6 million of property, plant and equipment, a A$9.5 million rehabilitation provision and a A$6.2 million increase in environmental surety requirements payable through July 2027. Its convertible securities are also valued using assumptions including share-price volatility, settlement timing and the probability of repayment in cash or shares.
FY2027 Tests Production Consistency and Liquidity
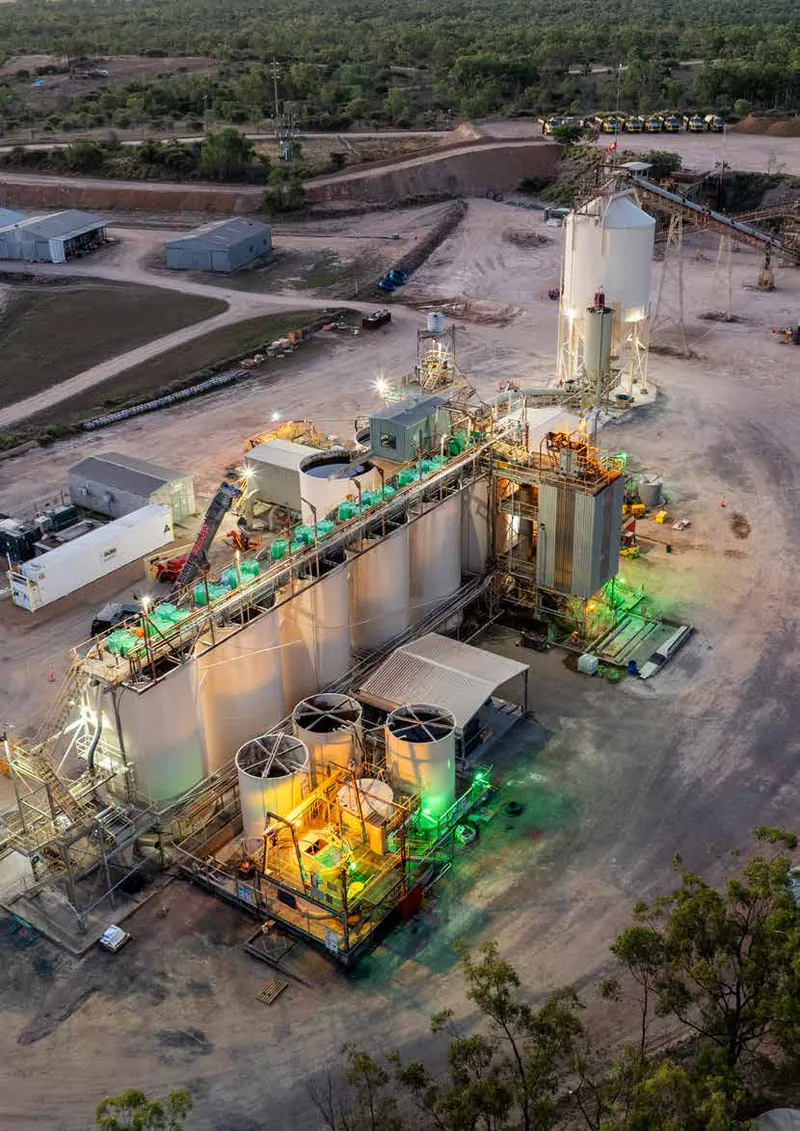
NMR’s stated priorities are to maintain weekly smelting, keep multiple mining fronts open, improve mine-to-mill reconciliation, complete plant improvement works and reduce debt from operating cash flow. The mine plan includes Blackjack Mid, Podosky, North Pit and Far Fanning, while Stockholm is targeted for mining from February to April 2027 subject to results and approvals.
The immediate test is whether the stronger September-quarter production rate can persist while the company meets debt, rehabilitation and operating commitments. Record ounces have improved the operating narrative, but the balance sheet still requires those ounces to arrive regularly, at sufficient grade and with enough margin to replace the funding that has carried NMR through its first year as a producer.
Get ASX:NMR news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
NMR has demonstrated a sharper production trajectory, but the investment case now turns on whether higher-grade, multi-source ore can generate enough cash to cover near-term debt and keep funding access open.
Questions in the middle?
- Can Blackjack sustain September-quarter production levels as Mid Pit and Podosky transition toward North Pit and Far Fanning?
- How will NMR meet the October 2026 Yogi Bear repayment and scheduled Collins St obligations without further dilution or debt?
- Will operating cash flow turn consistently positive before the company must fund TSF Stage 4, grid power and further mine development?
Sources
1-
Annual Report to shareholders (opens in a new tab)Verified source. Native Mineral Resources Holdings Limited · 30 Oct 2026 · wcsecure.weblink.com.au