US$33.6m cash and 59.0Mlbs resource shape Peninsula’s Lance reset

Peninsula Energy has reported materially stronger flow rates at several Lance header houses and reconfirmed its 500,000 to 600,000-pound CY2027 production target. The operational gains come alongside a US$30 million convertible debt draw, US$11.5 million of quarterly operating cash outflows and only 2.9 quarters of estimated funding at the current burn rate.
- HH15 and HH17 reach approximately 370 GPM and 500 GPM respectively
- CY2027 production guidance retained at 500,000 to 600,000 pounds of U3O8
- Lance mineral resource rises 1.7% to 59.0 million pounds
- US$30 million Soul Patts convertible facility fully drawn
- US$33.6 million cash balance and 2.9 quarters of funding at current outflows
 Add us as a preferred source on Google
Lance flow rates improve as production test moves to uranium grades
Peninsula Energy Limited (ASX:PEN) has produced its most encouraging operational evidence in months at the Lance uranium project, with two new or recently commissioned header houses reaching targeted flow rates. HH15 was operating at approximately 370 gallons per minute and HH17 at about 500 gallons per minute by the end of the September quarter, broadly in line with or above their respective targets.
The improvement is important because Lance’s problem has been less about the size of its uranium inventory than the ability to move solution through the low-pH in-situ recovery wellfields. Peninsula says new recovery wells in HH12, HH14 and HH16 are also showing stronger flows and, in some cases, encouraging uranium concentrations. The company’s current assessment is that previous underperformance was principally linked to localised well completion, wellfield design and solution-management practices rather than a broad permeability problem, although further operating data is required to test that view.
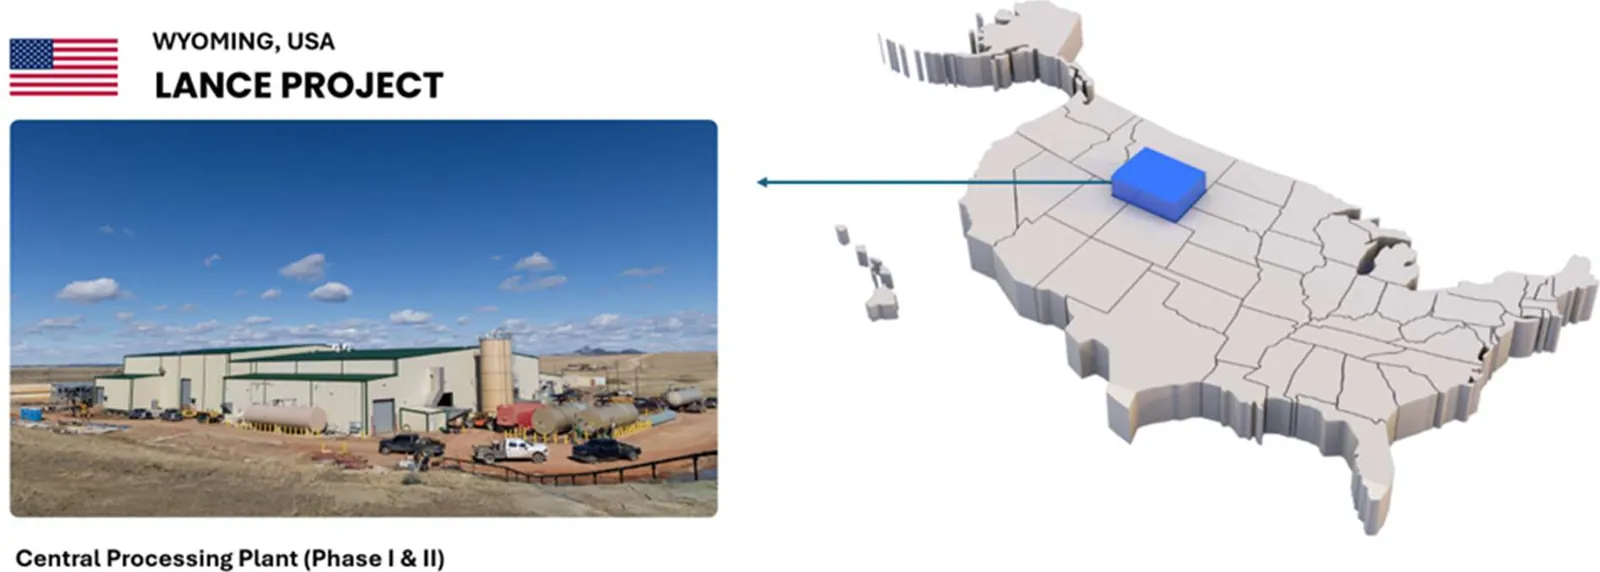
The operational gains build on the Lance flow-rate update, which reported stronger performance at several header houses while Peninsula retained its 2027 target. The next challenge is less visually dramatic but commercially decisive: lowering wellfield pH towards approximately 1.8 standard units, improving contact with mineralised formations and lifting head grades. Peninsula is also targeting better utilisation of resin loading and elution in the central processing plant.
CY2027 target survives, while CY2026 guidance remains withdrawn
Peninsula reconfirmed production guidance of 500,000 to 600,000 pounds of U3O8 for calendar 2027. It has no production guidance for 2026, after the Lance ramp-up took longer than expected. September-quarter production remained modest, with 17,968 pounds captured on resin and 15,588 pounds drummed.
That gap between improving hydraulics and saleable production is the central qualification to the update. HH17’s flow was capped at 500 GPM by the available dissolved air flotation capacity, while lower-than-target pH performance continues to weigh on grades at parts of HH14 and HH16. Peninsula expects hydrogen peroxide effects at HH15 to become more apparent during the December quarter and is redesigning parts of MU-3 after new recovery wells delivered the best flow per well seen there to date.
59 million-pound resource provides scale, not near-term cash
Peninsula’s Lance mineral resource increased 1.7% to 59.0 million pounds of contained U3O8, comprising 4.3 million pounds Measured, 12.9 million pounds Indicated and 41.7 million pounds Inferred. The Ross mining area delivered the sharper increase, rising 15.6% to 7.4 million pounds after drilling associated with Mine Unit 4.
The Ross resource increase gives the project more geological scale and confidence around part of MU-4, but it does not alter the distinction between a mineral resource and a production forecast. The immediate investment question remains whether the enlarged inventory can be converted into reliable uranium output at Lance.
US$30 million debt draw extends funding, but leaves little spare capacity
Peninsula ended September with US$33.6 million in cash after fully drawing its US$30 million Soul Patts convertible debt facility. The quarter consumed US$11.5 million in operating cash and a further US$6.5 million on Lance development, leaving the company with an estimated 2.9 quarters of funding based on current operating outflows and no unused finance facilities.
That runway calculation is not a forecast of insolvency, and Peninsula says it expects uranium sales to begin in coming months. But the company also cautions that the timing and volume of those sales may vary while newly commissioned wellfields remain in ramp-up. The cash position therefore depends heavily on the operational improvements translating into production and revenue before the current burn rate becomes the more important story.
Impairment and technical reset sharpen the Lance test
The quarter also crystallised the cost of the previous strategy. Peninsula recognised a US$50.1 million non-cash impairment against legacy wellfield development assets and other historically capitalised costs, following its decision to concentrate resources on MU-4 and future mine units. The US$50.1 million impairment does not reduce cash or current funding arrangements, but it marks a material reduction in the carrying value of selected legacy assets.
Peninsula has added low-pH ISR specialist Gary Birch as chief technical officer, formed a technical committee and hired Rendement to examine wellfield flow and ion-exchange performance. Those steps add expertise and scrutiny; they do not yet prove that the revised operating model will deliver sustained grades, production or cash generation. The next quarter should provide the clearest test of whether better flow rates are becoming better uranium economics.
Get ASX:PEN news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Peninsula has bought time with fresh debt and gained operational traction, but the Lance thesis now turns on converting stronger well flows into consistent grades, sales and lower cash burn.
Questions in the middle?
- Will the improved flow rates at HH15, HH17 and the new recovery wells translate into sustained uranium head grades?
- How quickly can Lance uranium sales begin, and will their timing materially change the current cash runway?
- Can the revised MU-4 strategy support the retained CY2027 production target without another funding requirement?
Sources
2-
Quarterly Activities Report (opens in a new tab)Verified source. Peninsula Energy Limited · 30 Oct 2026
-
Quarterly Cashflow Report (opens in a new tab)Verified source. Peninsula Energy Limited · 30 Oct 2026