Vitasora adds 9,000-patient Florida opportunity as care activity accelerates

5 min read
9:13am on Friday 30th of October, 2026 AEDT ~9am, 30th Oct, 26
Vitasora Health has signed a Florida healthcare agreement covering an initially addressable 9,000 Medicare patients while estimated October billable care minutes rose 50%. The ASX-listed company also agreed terms for an A$3 million secured facility, but the funding is not yet drawn and carries approval, interest and dilution conditions.
- TCCH agreement covers seven Florida locations and approximately 9,000 initially addressable Medicare patients
- October billable care minutes estimated at 263,000, up 50% from September
- Estimated October revenue of US$450,000 implies an illustrative A$8.1 million annualised run-rate, not a forecast
- A$3 million Peters Investments facility remains subject to documentation, drawdown conditions and shareholder approval
- September quarter ended with A$862,000 cash and 0.41 quarters of funding under the Appendix 4C measure
 Add us as a preferred source on Google
Florida contract expands Vitasora’s Medicare opportunity
Vitasora Health Limited (ASX:VHL) has added a sizeable Florida healthcare customer at a moment when its existing US operations are already accelerating. Treasure Coast Community Health, which operates seven locations and serves approximately 31,000 patients, has signed an agreement covering an initially addressable Medicare population of about 9,000 people.
The initial programme will provide Chronic Care Management and Principal Care Management, with enrolments targeted to begin in November 2026. That 9,000-patient figure describes potential eligibility, not confirmed enrolments or revenue. TCCH will also be the first Vitasora customer to deploy the complete vCare platform integrated with its electronic medical record system, although vCare is already operating across existing US customers.
Existing customers drive October activity surge
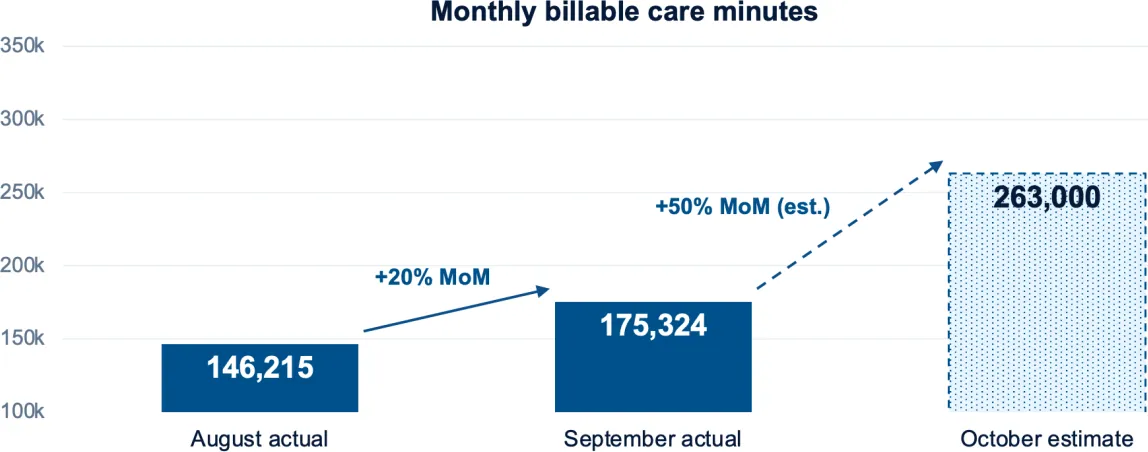
The more immediate operating signal is coming from Vitasora’s current customer base. Management estimates October billable care minutes at approximately 263,000, up 50% from 175,324 in September, which itself rose 20% from August. Care Coordinator utilisation exceeded 95% on recent operating days, with 42 coordinators active and targets of 48 by November and approximately 115 during the first quarter of 2027.
The workforce expansion was a central feature of Vitasora’s 115-Coordinator hiring target and is now being tested against actual billable activity. Management estimates October revenue at about US$450,000, equivalent to an illustrative annualised run-rate of US$5.4 million, or approximately A$8.1 million using the exchange rate disclosed in the filing. That comparison is nearly 90% above FY2026 audited revenue of A$4.29 million, but it is based on one month of estimated activity and is not a forecast.
Revenue growth is running ahead of cash collection
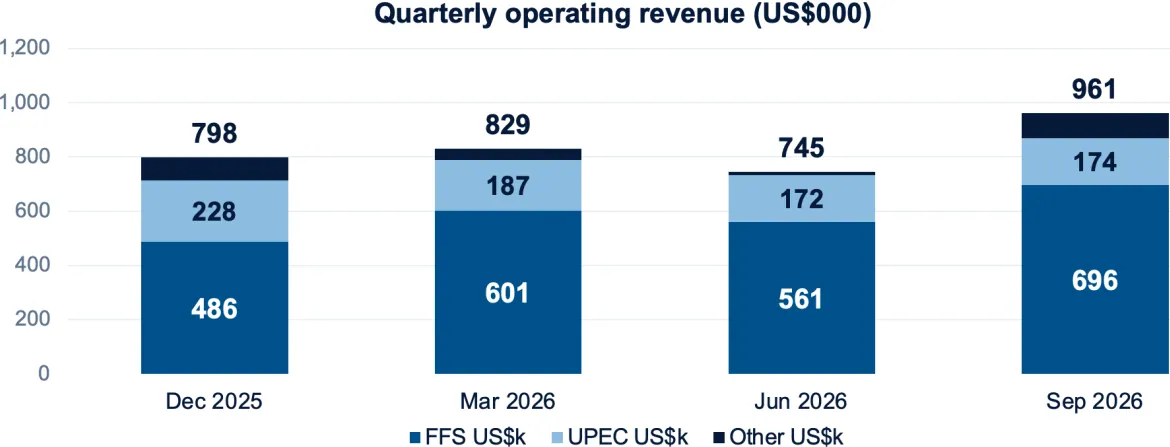
For the September quarter, fee-for-service revenue reached approximately US$695,911, up 24% from the June quarter, while total operating revenue rose 29% to about US$960,504. Customer cash receipts increased 9% to A$1.015 million, but the company said collections had not yet fully reflected the growth in revenue-generating activity because of claims processing and billing reconciliation.
That timing gap matters. Vitasora reported a September-quarter net operating cash outflow of A$2.081 million and ended the period with A$862,000 in cash, equivalent to 0.41 quarters of funding under the Appendix 4C calculation. The company said its adjusted business-as-usual monthly cash burn was approximately A$562,000, down from A$650,000 in the June quarter, but that measure is separate from the statutory cash-flow total.
A$3 million loan brings runway and financing obligations
Against that cash position, Peters Investments has signed a binding terms sheet for an A$3 million secured loan and option facility. Peters was the cornerstone investor in Vitasora’s June cornerstone investment, and the new facility is intended to fund Care Coordinator recruitment, TCCH and other client implementations, patient enrolments and working capital.
The proposed loan runs for 24 months at 12.5% annual interest, compounded daily and paid monthly in cash. It would be secured by a first-ranking general security deed over Vitasora and its Australian subsidiaries, subject to shareholder approval. The facility remains undrawn until formal loan and security documents are completed, with drawdown also subject to applicable conditions.
The financing includes 208,971,000 four-year options initially exercisable at A$0.012 a share, with a floor of A$0.004 if the exercise price is reset following a lower-priced cash issue. Shareholder approval is required for both the security and the option issue. If either approval fails, Vitasora would have to repay the loan, accrued interest and a fee equal to 6% of the loan amount within 30 days of the meeting.
Cash-flow breakeven depends on execution
Vitasora continues to target cash-flow breakeven in the first half of 2027, with management expecting pro forma operating profitability to precede cash breakeven because of the lag between billing and collections. That objective depends on TCCH enrolments, sustained eligible activity, recruitment, claims conversion, collections and the eventual availability of the Peters facility.
The next hard evidence will come from whether the October activity estimates convert into recognised revenue and cash, and whether TCCH can move from an addressable population to actual patient enrolments. Until the financing is documented, drawn and approved, Vitasora has a growth opportunity and a funding plan, not yet the full liquidity cushion implied by the headline A$3 million.
Get ASX:VHL news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Vitasora has added a meaningful customer and stronger operating momentum, but the investment case still turns on converting billable activity into cash before the conditional funding and its associated obligations become critical.
Questions in the middle?
- How many of TCCH’s approximately 9,000 addressable Medicare patients will actually enrol, and how quickly?
- Will the October estimated revenue and care-minute surge translate into recognised revenue and customer receipts after billing reconciliation?
- Can Vitasora secure shareholder approvals and draw the A$3 million facility without materially constraining flexibility through debt, security and option terms?
Sources
2-
Quarterly Activities/Appendix 4C Cash Flow Report (opens in a new tab)Official market announcement. Vitasora Health Limited · 30 Oct 2026 · vitasorahealth.com.au
-
VHL Secures Major Contract and $3m Working Capital Facility (opens in a new tab)Official market announcement. Vitasora Health Limited · 30 Oct 2026 · vitasorahealth.com.au