A$6.6 million development spend follows PV-14 tie-in and PV-15 spudding

Echelon Resources has tied in Palm Valley 14, but output has fallen to around 0.5 TJ a day after pre-completion testing indicated 3-4 TJ a day. The company is funding its expanded drilling programme from operating cash flow while PV-15 moves towards expected first production in early 2027.
- PV-14 output falls to around 0.5 TJ/d after tie-in
- PV-15 spudded after quarter end, with first production expected early 2027
- Quarterly production rises to 250,224 boe
- Operating cash flow of A$7.1 million funded A$6.6 million of development spending
- Cue divestment delivers more than A$17 million in cash proceeds
 Add us as a preferred source on Google
PV-14 output falls well below initial testing
Echelon Resources Limited (ASX:ECH) has reached the operational milestone at the centre of its Palm Valley drilling programme, but the first well is not yet delivering the result suggested by early testing. Palm Valley 14 was completed and tied in during the quarter, with testing indicating a potential production rate of 3-4 terajoules a day. After tie-in, however, the rate declined to around 0.5 TJ/d, possibly because of water loading.
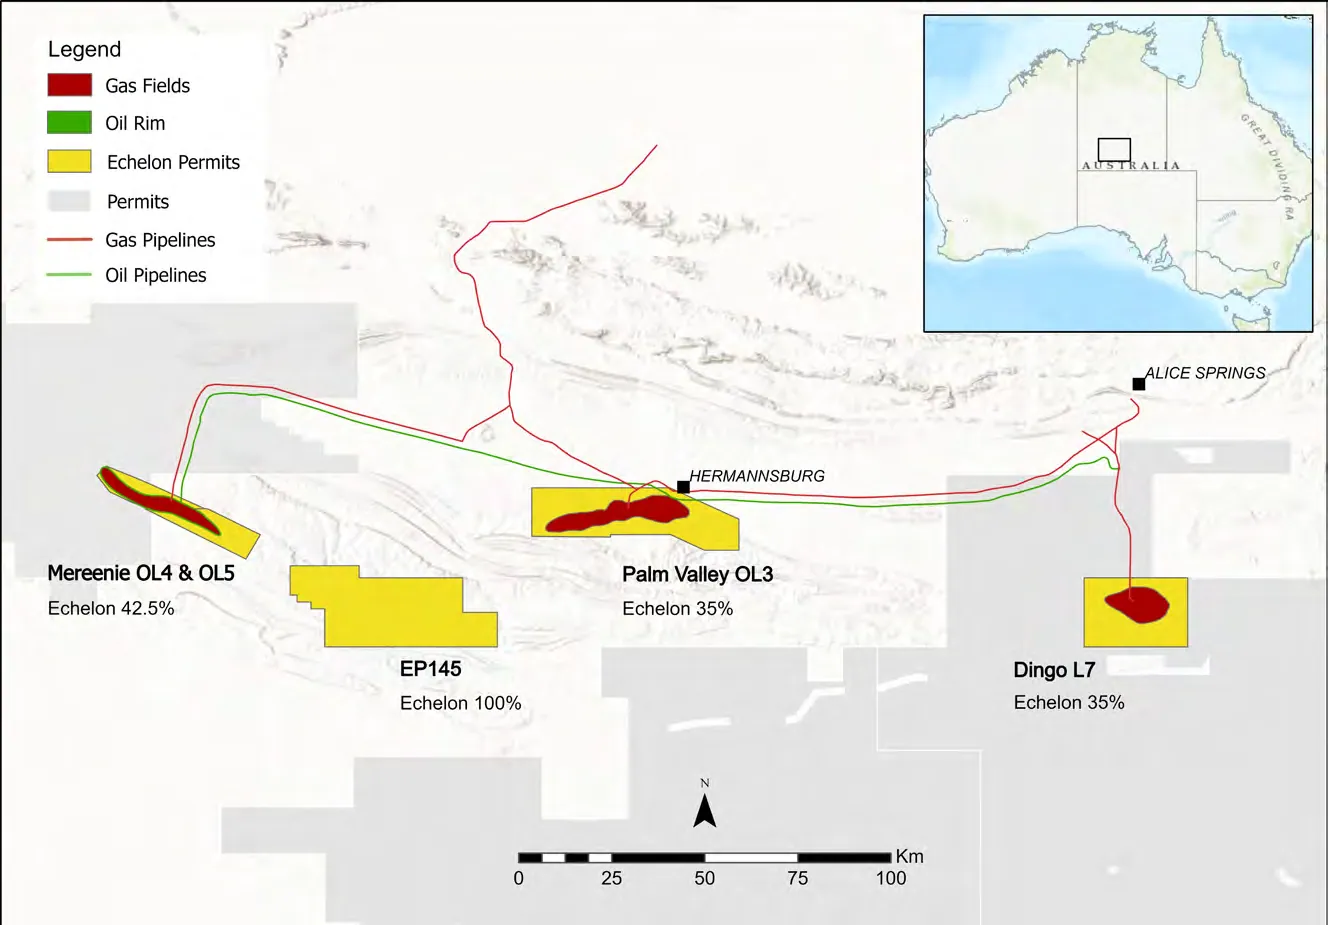
The joint venture is reviewing options to improve the well’s performance, and Echelon says its ultimate production rate cannot yet be assessed confidently. That makes the PV-14 water-loading concern more than a technical footnote: the well’s sustained output will help determine how much of the Palm Valley development plan is actually delivered.
PV-15 keeps the drilling programme moving
The rig moved to Palm Valley 15 after PV-14 completion activities, and PV-15 was spudded in early October, after the reporting period. Drilling is expected to continue through the current quarter, with first production expected in early 2027. Echelon is pursuing the two-well programme to support its new long-term gas supply agreement, which took effect on 1 October.
The timing leaves PV-15 as the next clear operational test. Its contribution will need to be assessed alongside any remediation or production-improvement work at PV-14, rather than treated as a simple addition to the field’s output.
Operating cash flow funds higher development spending
Quarterly production increased modestly to 250,224 barrels of oil equivalent, from 243,691 boe in the previous quarter, while average daily production rose to 2,720 boe. Customer receipts were A$16.1 million, broadly in line with the June quarter, and operating cash flow reached A$7.1 million.
That cash generation funded development expenditure of A$6.6 million, up 145% from A$2.7 million as drilling activity accelerated. Cash at quarter end was A$25.1 million, down from A$26.9 million, while the loan balance remained unchanged at A$10.5 million. The figures show a company spending materially more on development without drawing further debt during the quarter.
Cue divestment leaves Echelon with cash and Horizon stake
Echelon also completed the remaining steps in its Cue Energy exit, receiving the final A$1.7 million of consideration in July and taking total cash proceeds above A$17 million. The company now holds a 6.61% stake in Horizon Oil, and received a further A$1.2 million dividend on those shares after quarter end. The Cue Energy divestment had previously simplified Echelon’s portfolio and supported debt reduction during FY26.
The transaction provides additional balance-sheet capacity, but the immediate investment question has shifted from portfolio restructuring to execution at Palm Valley. Proposed changes to Australian domestic gas reservation settings are also under assessment. Echelon says its existing contracts provide some protection and that its Northern Territory exposure is lower than that of some industry participants, though the report does not quantify the potential effect.
Kupe remains steady ahead of planned shutdown
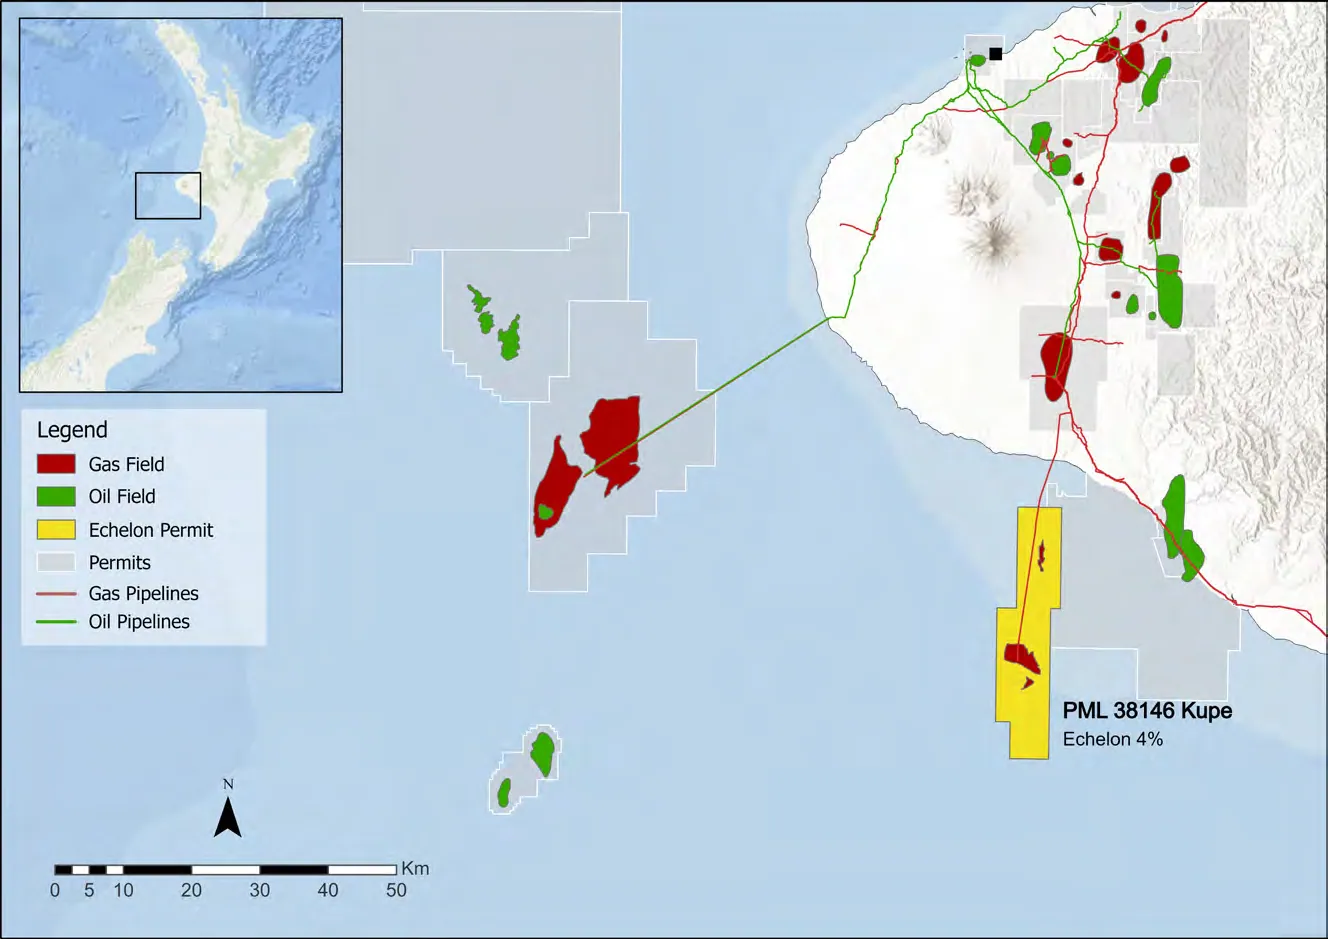
Kupe production was steady despite an unplanned one-day shutdown in September, with a seven-day optimisation shutdown planned for November. Gas sales were marginally higher than in the prior quarter, while activity also continued across the Amadeus Basin, including a review of further Mereenie appraisal opportunities and prospectivity work at EP145.
Get ASX:ECH news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
PV-15 is now the next operational catalyst, but the investment case will also depend on whether Echelon can restore PV-14 from its current 0.5 TJ/d rate without materially expanding development costs.
Questions in the middle?
- Can the joint venture resolve the possible water-loading issue and establish a sustainable PV-14 production rate?
- Will PV-15 deliver first production in early 2027 and at what rate?
- How will the new gas sales agreement and proposed reservation changes affect future receipts and cash generation?
Sources
1-
Quarterly Activities Report (opens in a new tab)Official market announcement. Echelon Resources Limited · 30 Oct 2026 · echelonresources.com