A$108.9 million cash balance cushions Kingsgate’s disrupted Chatree quarter

Kingsgate’s cash balance climbed to A$108.9 million despite a difficult September quarter at Chatree, where a 47-day mill shutdown, heavy rainfall and geotechnical constraints cut gold production. The company is relying on a stronger second half of FY27, insurance proceeds and longer-term growth at Nueva Esperanza to offset the near-term disruption.
- Cash balance increased 27% to A$108.9 million
- Chatree produced 14,802 ounces of gold and 187,925 ounces of silver
- FY27 production guidance remains 75,000-85,000 ounces of gold
- Plant 1 replacement component is expected in the fourth quarter of FY27
- Nueva Esperanza reserves rose to 51.9 million ounces of silver and 0.26 million ounces of gold
 Add us as a preferred source on Google
Chatree disruption cuts quarterly gold output
Kingsgate Consolidated (ASX:KCN) finished the September quarter with more cash but less operating momentum. Gold production at its Chatree mine fell to 14,802 ounces, down from 20,163 ounces in the June quarter, after a prolonged Plant 1 shutdown collided with heavy rainfall and geotechnical constraints in the A Pit area.
The quarter included a 47-day shutdown of Ball Mill 1 after its trunnion bearings failed and damaged the trunnion journals. A modified circuit allowed Plant 1 to restart at about 50% of nameplate capacity on 15 July, while repairs continued. The company has ordered a new discharge-end mill head, with delivery expected in the fourth quarter of FY27 and a planned shutdown required for installation.
The disruption was not the only drag on output. Open-pit ore mined fell 59% to 635,000 tonnes as the operation prioritised waste movement and water management, while the stripping ratio rose to 8:1. Ore processed declined to 1.18 million tonnes, and lower-grade stockpile material contributed to a fall in gold head grade to 0.47 grams per tonne. Chatree nevertheless moved 7.28 million tonnes of material during the quarter, broadly consistent with the previous period.
Cash improves while costs remain elevated
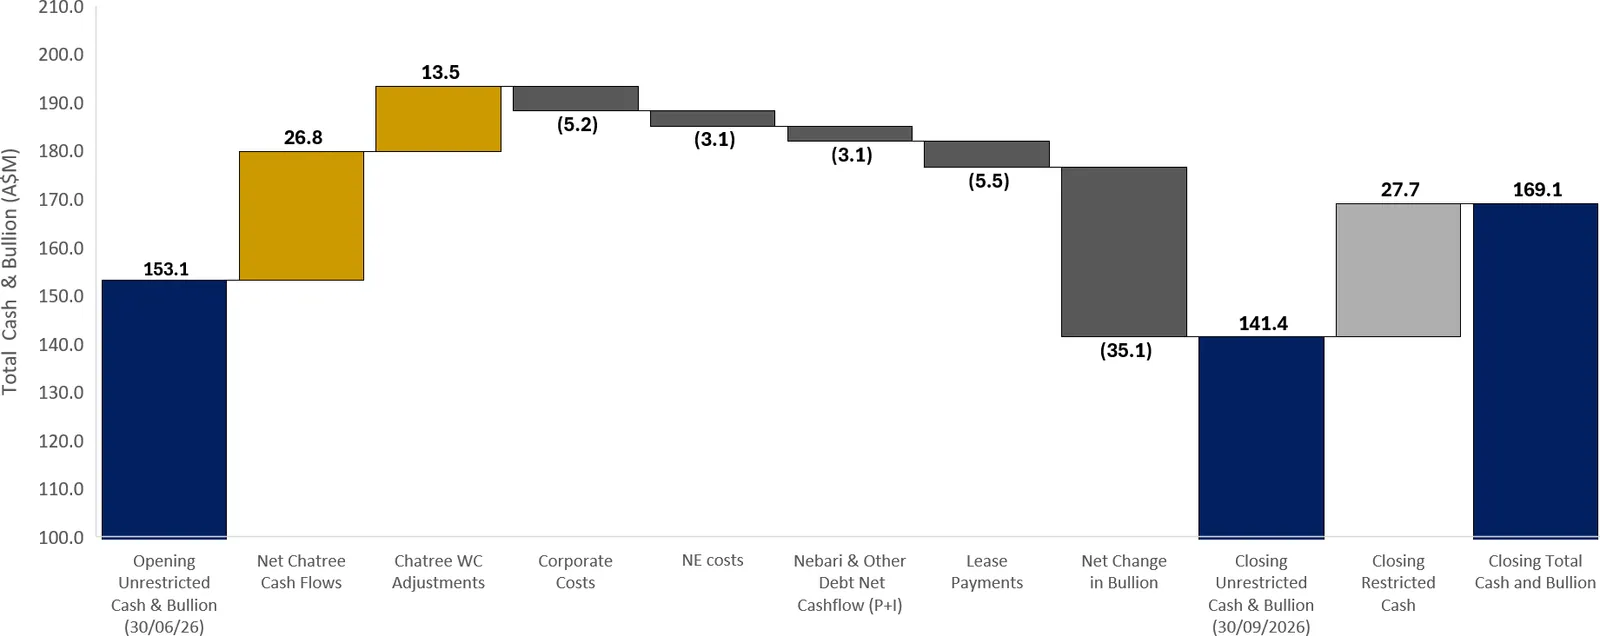
The financial picture was more resilient than the production numbers. Kingsgate’s cash balance rose 27% to A$108.9 million, while total cash, bullion and doré reached A$169.1 million, including A$27.7 million of restricted cash. Available cash and bullion was A$141.4 million at quarter end, down from A$153.1 million, reflecting lower bullion holdings and investment in the mine and growth projects.
Chatree generated positive net mine cash flow of A$26.8 million, excluding a A$13.5 million working-capital benefit. The mine sold 17,339 ounces of gold and 211,081 ounces of silver at an average gold sale price of US$4,236 an ounce. However, Chatree’s all-in sustaining cost rose to US$2,514 an ounce sold, compared with US$2,197 in the June quarter, even as the operation recorded a US$1,722 an ounce margin.
The cost increase partly reflects lower gold sales, stockpile drawdown and the quarter’s reclamation, maintenance and sustaining capital charges. Kingsgate spent A$21.5 million on major capital and A$8.4 million on sustaining capital, including A$16.7 million of deferred stripping and A$7.4 million on the TSF2 lift and buttressing. The Plant 1 insurance claim is well advanced, but the company expects the majority of proceeds to arrive during calendar 2027 and has not disclosed the amount.
FY27 guidance depends on a stronger second half
Kingsgate maintained FY27 guidance of 75,000-85,000 ounces of gold, 650,000-750,000 ounces of silver and 82,000-93,000 gold-equivalent ounces for Chatree. Production is expected to be weighted towards the second half as A-West de-stacking progresses, the A-East cutback advances and Q-Pit contributes additional ore.
The company also retained guidance for pre-royalty AISC of US$1,650-US$1,850 an ounce and sustaining capital of about A$30 million. That range incorporates the lower production profile, planned Plant 1 maintenance in 2027 and higher consumable costs. Kingsgate says a localised movement affecting the A-Pit ramp deferred about 3,000 ounces of production to FY28, adding another constraint to the near-term plan.
The immediate operational test is whether the mine can convert the current waste movement into improved ore access without another processing interruption. Kingsgate’s earlier Plant 1 repair program maintained partial output during the mill failure; the next planned shutdown will test whether the permanent equipment solution can improve reliability without materially extending the production squeeze.
Nueva Esperanza adds a longer-dated growth option
At Nueva Esperanza in Chile, the Ore Reserve increased 31% to 51.9 million ounces of silver and 37% to 0.26 million ounces of gold, extending the planned reserve life beyond 12 years. The increase primarily reflected higher long-term metal price assumptions and lower royalty obligations following the 2026 Anglo American royalty purchase, rather than the results of new drilling.
The company has now started Nueva Esperanza’s first drilling program in nine years, while geometallurgical drilling continues at the Teterita deposit. Kingsgate’s Nueva Esperanza reserve increase had already lifted the project’s stated reserve base; the current drilling campaign is intended to provide further technical information as development studies continue.
Closer to Chatree, Kingsgate substantially completed an A$11 million acquisition of 24 land parcels covering about 86 hectares. The land is intended to support expanded tailings and waste-dump capacity for the next six to eight years. An updated Interim Mine Plan and an Environmental and Health Impact Assessment are expected to be submitted in the December quarter, while an independent safety review of the TSF1 and TSF2 facilities is due in November.
Get ASX:KCN news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Kingsgate has the liquidity to absorb a difficult quarter, but the investment case now hinges on a reliable Plant 1 restart, improved ore access and the timing of insurance proceeds.
Questions in the middle?
- Can A-West, A-East and Q-Pit deliver the higher-grade ore volumes assumed in the second half of FY27?
- How much of the Plant 1 interruption and related production loss will the insurance claim ultimately recover?
- Will Nueva Esperanza drilling add operating value beyond the reserve uplift driven by price and royalty assumptions?
Sources
1-
September 2026 Quarterly Report (opens in a new tab)Official market announcement. Kingsgate Consolidated Limited · 30 Oct 2026 · kingsgate.com.au