Lithium Plus advances Lei with A$325m study as funding becomes the key test

Lithium Plus Minerals has outlined a preliminary A$325 million post-tax NPV for its Lei lithium project, alongside a six-year production target and a 34% resource increase. But the ASX explorer ended September with A$1.054 million cash, estimated funding of just 0.78 quarters and plans for an additional equity raising.
- A$325 million post-tax NPV and 75.4% IRR for Lei
- 3.52Mt six-year production target at 1.37% Li₂O
- Lei resource rises to 5.22Mt at 1.50% Li₂O
- A$1.054 million cash balance and no debt at quarter end
- Additional equity raising planned as funding runway falls below one quarter
 Add us as a preferred source on Google
Lei study delivers strong headline economics
Lithium Plus Minerals Limited (ASX:LPM) has put a potentially valuable lithium project on paper, but will need fresh capital before the story can move much further. Its Lei Lithium Project scoping study outlined a post-tax NPV of A$325 million, a 75.4% internal rate of return and an initial project capital requirement of A$87.7 million.
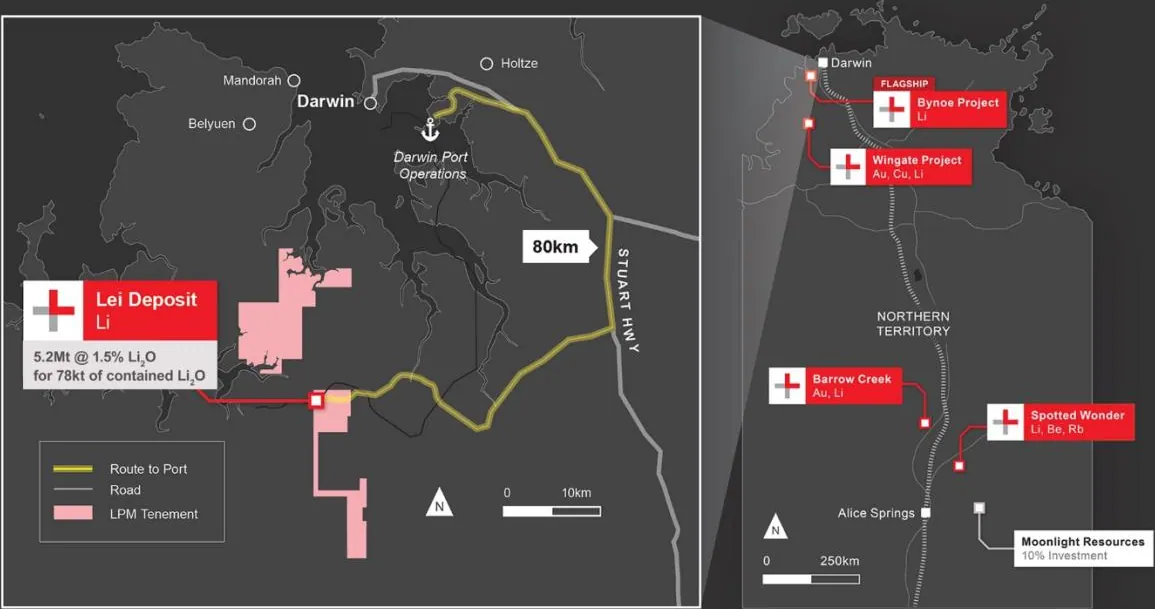
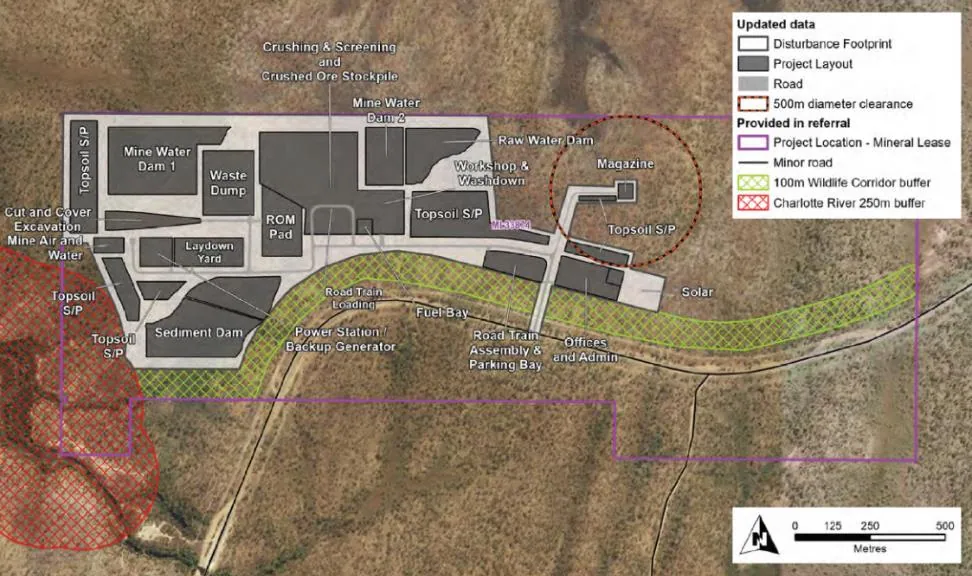
The proposed operation would mine and ship 3.52 million tonnes of mineralised material grading 1.37% Li₂O over six years. The design is deliberately lean: contractor-operated underground mining, on-site crushing and screening, road haulage to Darwin Port and no processing plant at the mine. The study forecasts A$1.613 billion in life-of-mine revenue and A$907 million in EBITDA, with sustaining capital of A$129.6 million expected to be funded from operating cash flow.
The figures were set out in the and are based on a DSO price assumption of US$350 a tonne CIF China for material at a 1.5% Li₂O reference grade. Lithium prices remain volatile, and the company says actual realised prices could differ materially from that assumption. The study is preliminary, no Ore Reserve has been declared, and 43% of the scheduled production is drawn from Inferred Resources.
Resource growth strengthens the mine plan
Lei’s Mineral Resource now stands at 5.22Mt at 1.50% Li₂O, containing 78.42kt of Li₂O, at a 0.5% cut-off. That is up from 4.09Mt at 1.43% Li₂O in the December 2023 estimate, representing a 34% increase in contained lithium. Indicated Resources account for 2.85Mt, or 55% of the total.
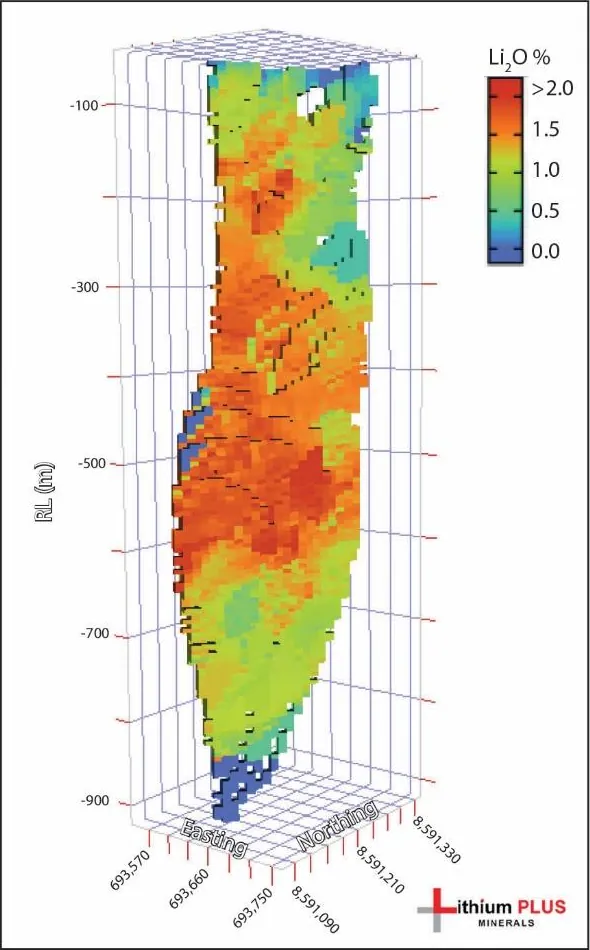
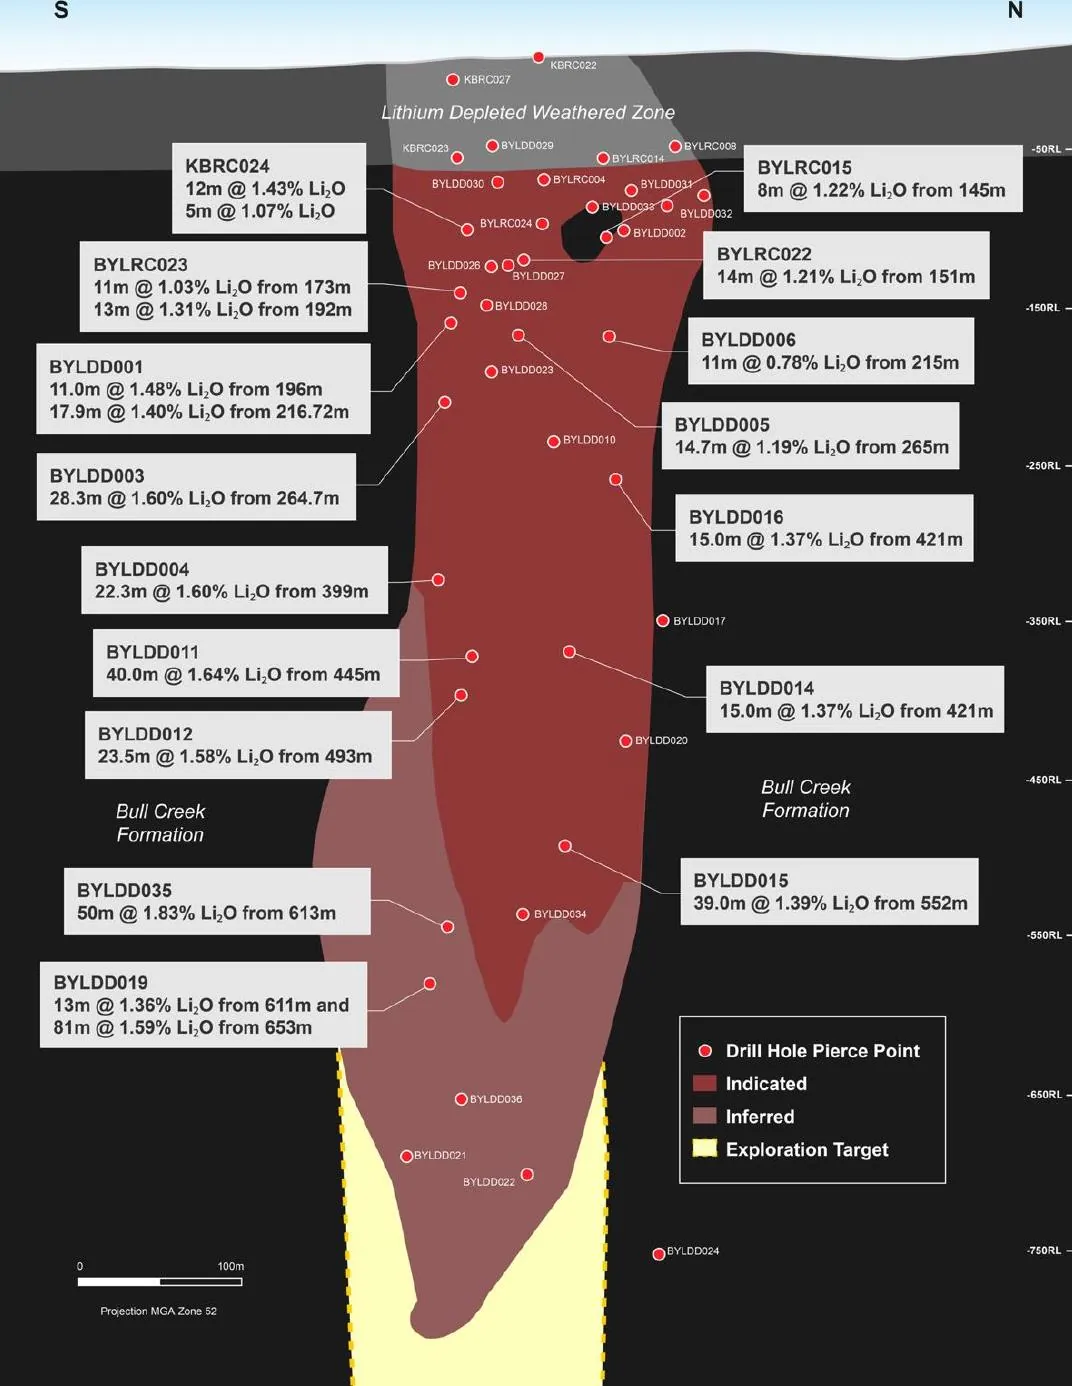
The upgrade, covered in the 34% Lei resource increase, followed drilling that extended the pegmatite at depth and along plunge and improved confidence in its geometry and grade continuity. The study says all scheduled production in Years 1 and 2 is classified as Indicated, while Indicated material represents 88% of cumulative production through Year 3.
Drilling and approvals remain on the critical path
Lithium Plus plans eight reverse-circulation holes into the largely untested Lei Secondary Pegmatite, about 170 metres east of the primary body, as well as two deep diamond holes targeting both resource confidence and the secondary pegmatite. The company also intends to test the nearby Perseverance target after the Lei program.
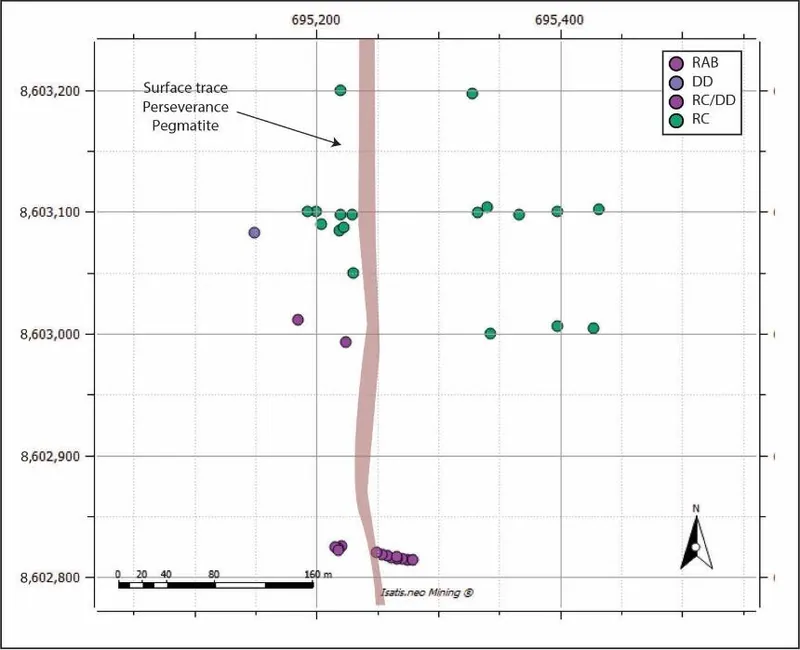
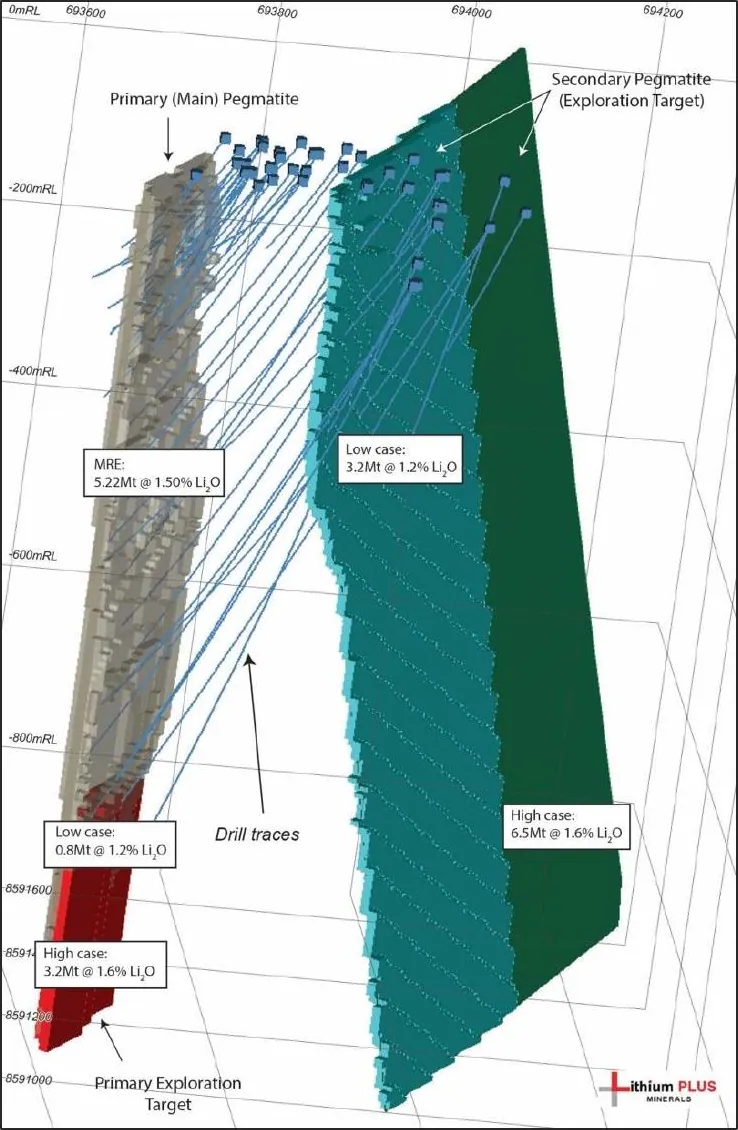
Those targets could add to the mine plan, but the company’s exploration estimates remain conceptual rather than Mineral Resources. The combined low-to-high Exploration Target range across the Lei primary and secondary pegmatites and Perseverance is 7.6Mt to 19.4Mt at 1.2% to 1.6% Li₂O. Lithium Plus cautions that insufficient exploration has been completed to estimate a Mineral Resource and that further work may not achieve that outcome.
Environmental approval is another gate. Lithium Plus submitted its Supplementary Environmental Report during the quarter in response to additional information requirements from the Northern Territory Environment Protection Authority, with approval targeted for the first quarter of calendar 2027. The company also has non-binding arrangements covering Darwin Port discussions and a potential Canmax offtake, rather than final commercial commitments.
Cash runway puts funding ahead of construction
The immediate financial issue is more pressing than the eventual construction bill. Lithium Plus held A$1.054 million in cash and no debt at 30 September, after spending A$966,000 on exploration and evaluation and recording net operating cash outflows of A$389,000. On the ASX Appendix 5B calculation, total relevant quarterly outgoings were A$1.355 million, leaving estimated funding of 0.78 quarters.
The company said it expects exploration and evaluation spending to be limited by the Northern Territory wet season from November or December, and that it is in the process of raising additional equity. It did not disclose the size, pricing or timing of that raising in the report. That makes the next capital event central to the Lei timetable: the study’s A$87.7 million initial capital requirement is many times larger than the company’s current cash balance, before sustaining capital is considered.
Get ASX:LPM news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Lei has a sizeable preliminary valuation and a clearer development pathway, but the proposed equity raising is now the near-term catalyst and financing risk.
Questions in the middle?
- What size, price and structure will Lithium Plus seek for the additional equity raising?
- Can the company secure environmental approval and convert its non-binding port and offtake arrangements into binding commitments?
- Will drilling convert enough Inferred material or discover additional pegmatite to support a larger or more confident mine plan?
Sources
1-
Quarterly Activities/Appendix 5B Cash Flow Report (opens in a new tab)Official market announcement. Lithium Plus Minerals Ltd · 30 Oct 2026 · lithiumplus.com.au