Sunrise clears key hurdle for 2028 Syerston scandium production

Sunrise Energy Metals has approved development of its Syerston Scandium Project in New South Wales, targeting first commercial production in the second half of 2028. The decision moves the project into construction while leaving financing, listing and execution milestones ahead.
- Final investment decision approved for Syerston
- 60 tonnes per annum of high-purity scandium oxide targeted
- First production targeted for the second half of 2028
- Conditional US$400 million U.S. government debt commitment
- Proposed U.S. redomiciliation and Nasdaq listing remain subject to approvals
 Add us as a preferred source on Google
Syerston receives final investment approval
Sunrise Energy Metals Limited (ASX:SRL; OTCQX:SREMF) has crossed the most consequential gate in its scandium development story, approving the Final Investment Decision for the Syerston Scandium Project in central-west New South Wales. The company is now targeting first commercial production in the second half of 2028, with the project positioned as a potential major primary source of scandium outside China.
The initial development is designed to process 64,000 tonnes of ore a year and produce 60 tonnes of high-purity scandium oxide annually. Sunrise says the deposit averages 690 parts per million scandium in its first decade, while the life-of-mine average mill-feed grade is 656 parts per million. The company’s design parameters point to a 32-year operating life, comprising 21 years of mining followed by 11 years of processing stockpiled ore.
Early construction work supports 2028 target
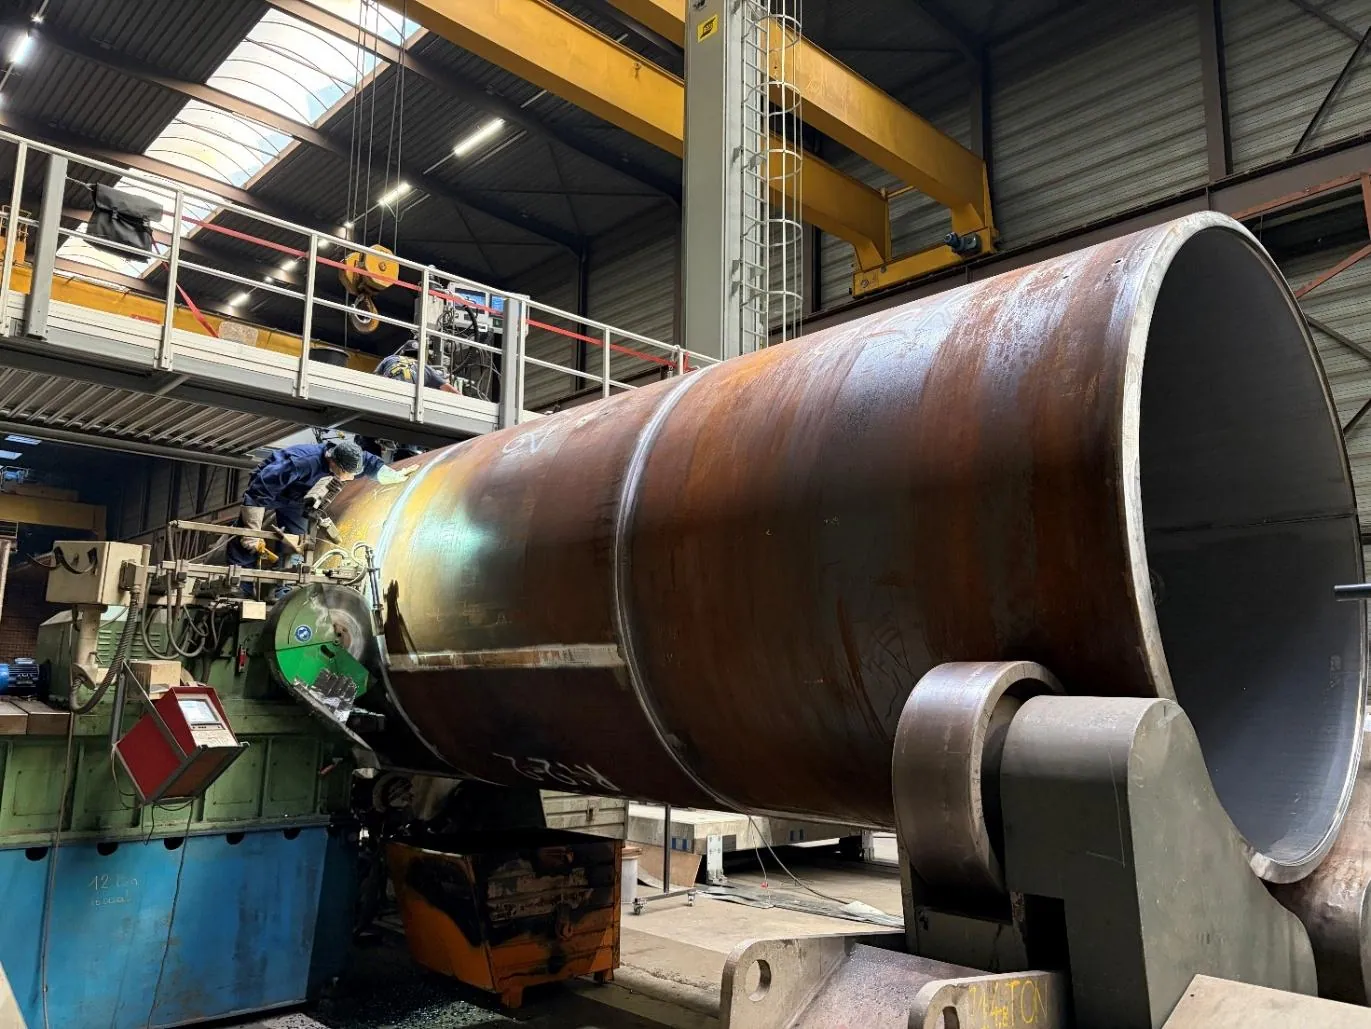
The FID arrives with parts of the project already moving beyond study work. Sunrise says long-lead equipment packages have advanced through tender evaluation and supplier selection, while Stage 2 design for the water pipeline has been completed and procurement of critical equipment has begun. Images released with the announcement show water pipeline construction starting on 9 October and autoclave construction underway at the end of September.
The mine is expected to use conventional open-pit excavation and trucking, with hydrometallurgical leaching and refining used to produce scandium oxide exceeding 99.9% purity. A 24-month construction and commissioning period is included in the project design. That timetable leaves execution, commissioning and ramp-up as the practical tests of the newly approved plan rather than simply the next items on a development checklist.
Conditional U.S. financing remains central
Sunrise says the positive FID was supported by a conditional commitment for up to US$400 million in long-term debt from the U.S. Department of War’s Office of Strategic Capital. That commitment was reported alongside the company’s move into a more advanced project and procurement phase in the US$400 million funding commitment, but it remains conditional rather than drawn project finance. Sunrise also reported $148.1 million of available cash at 30 September 2026.
The announcement does not provide a clearly stated development-capital figure in its project-parameter table, so the FID should not be read as a complete disclosure of the project’s funding requirement. The company is also studying possible expansion capacity, although its timing and scale have not been determined and would depend on customer commitments, demand, engineering outcomes, financing and further Board approval.
Nasdaq pathway tied to project funding
Sunrise is pursuing a proposed redomiciliation of its parent company to Delaware and a Nasdaq listing, with ASX exposure intended to continue through CHESS depositary interests. The transaction remains subject to the Scheme process and shareholder, court, regulatory and listing steps; the company says a Scheme Booklet is being prepared. The proposed listing was first framed as part of the Nasdaq redomiciliation plan, and Sunrise again links that U.S. pathway to the OSC financing commitment.
The strategic case is clear enough: Sunrise is attempting to pair a new Western scandium supply source with U.S. capital-market access and government-backed debt. The harder questions are now operational. Procurement must become construction, conditional financing must become available funding, and the company must turn a specialised mineral opportunity into dependable customer demand before the 2028 date becomes more than a target.
Get ASX:SRL news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The FID materially advances Syerston, but the investment case now turns on converting conditional U.S. funding and early works into a fully financed, commissioned operation by the second half of 2028.
Questions in the middle?
- When will the conditional OSC debt commitment become binding and available for drawdown?
- What final project capital requirement will Sunrise disclose as construction progresses?
- Can customer commitments and scandium demand support the planned 60-tonne annual operation and any later expansion?
Sources
1-
Syerston Scandium Project FID Approved (opens in a new tab)Verified source. Sunrise Energy Metals Limited · 2 Nov 2026