EcoQuip sales shortfall puts Volt's $3 million fleet investment under scrutiny

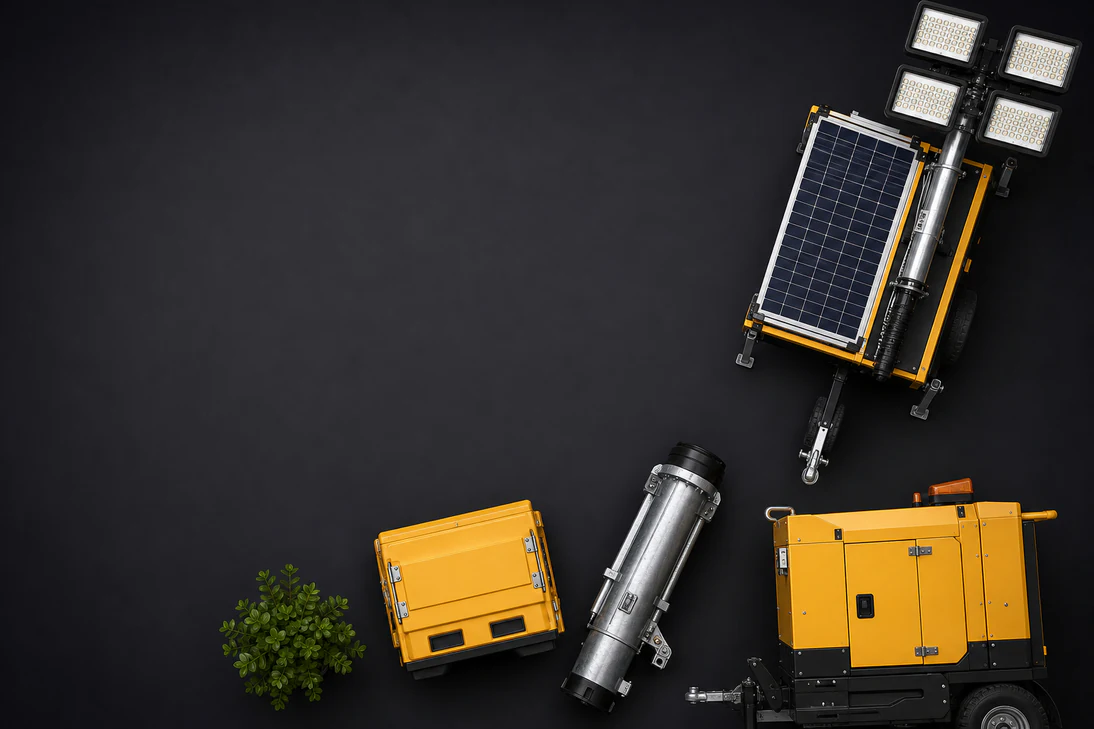
Volt Group has lowered its FY26 revenue and EBITDA guidance after weaker-than-expected EcoQuip sales, despite reporting stronger year-to-date operating cashflow and solid growth from 4D Delta. The company is committing $3.0 million to expand and refurbish its mobile solar-lighting fleet as it tries to convert customer trials into revenue.
- FY26 revenue guidance reduced to $9.5 million-$10.5 million
- FY26 EBITDA guidance cut to $3.0 million-$3.4 million
- Year-to-date ordinary revenue receipts rose 72% to $6.9 million
- EcoQuip year-to-date receipts fell 32% to $1.16 million
- $3.0 million approved for 50 new and 50 refurbished MSLTs
 Add us as a preferred source on Google
EcoQuip weakness forces FY26 guidance cut
Volt Group Limited (ASX:VPR) has cut its FY26 revenue and EBITDA guidance after EcoQuip sales fell well short of expectations, turning an otherwise stronger nine-month trading update into a mixed result for shareholders. Revenue guidance has been reduced from $11.0 million-$12.2 million to $9.5 million-$10.5 million, while EBITDA guidance has fallen from $4.1 million-$4.5 million to $3.0 million-$3.4 million.
The midpoint of the revised revenue range is about 14% below the midpoint of the original range. The equivalent reduction for EBITDA is roughly 26%, although the company said the downgrade was solely attributable to lower-than-expected EcoQuip sales.
4D Delta supplies the growth engine
Group ordinary revenue receipts reached $6.9 million for the nine months to 30 September, up 72% from $4.0 million a year earlier. That comparison includes 4D Delta from its 6 January 2026 acquisition settlement date, making the contribution material rather than incidental.
4D Delta generated $3.47 million in year-to-date revenue receipts, in line with its acquisition budget, while customer assets connected to its condition-monitoring platform rose 21% year to date to 927. The business is pursuing additional resource-sector customers and distribution partners in Europe and the Middle East, building on the earlier 4D Delta acquisition covered in 4D Delta acquisition growth.
EcoQuip revenue falls as fleet investment rises
EcoQuip produced $1.16 million in year-to-date revenue receipts, down 32% on the prior-year comparison. Its 65-unit deployed MSLT fleet recorded 99% availability, and the company said new deployments at four Westgold-operated gold mines performed reliably through winter. Those operating metrics, however, have not yet translated into the sales volume required to support the original FY26 outlook.
Volt has responded with a $3.0 million capital investment approved in September. The plan covers 50 new MSLTs, refurbishment of about 50 returned units and two research and development projects, with the first 20 new towers planned for assembly completion by 31 March 2027. If completed as described, the programme would give the sales team 100 units available for deployment by July or August 2027. That is a substantial inventory bet on a sales pipeline that currently consists partly of site trials and vendor registrations, rather than disclosed orders.
Cashflow improves while Wescone remains broadly steady
Net operating cashflow totalled $2.05 million year to date, excluding $0.52 million of one-off 4D Delta acquisition costs, up 63% from the prior-year comparison of $1.26 million. The company reported $0.2 million of operating cashflow in the quarter, $0.3 million of investing outflow and no financing cashflow, with cash payments totalling $2.03 million.
Wescone's year-to-date revenue receipts were $2.23 million, down 3%, after higher-than-expected BHP service-exchange crusher returns reduced quarterly cash receipts. The filing says the relevant $0.35 million offset had already been provided for in the HY26 interim report. Volt also said its African distribution partner, Mineral Innovative Technologies, has ordered two new crushers for delivery in the final quarter.
New sales leadership faces a demanding test
Byron Hoy joined Volt as chief operating officer in October, with responsibility for sales growth across EcoQuip, 4D Delta and Wescone. The company said EcoQuip's management restructure, initiated in June and completed with new operational and sales appointments in July, is intended to move the business from technology development towards commercial execution.
The filing refers to cash at bank of $3.53 million, but gives conflicting dates: one section identifies 30 June 2026, while the chairman's commentary identifies 30 September 2026. It also does not explain how the $3.0 million EcoQuip investment will affect cash holdings or be funded. The next evidence will need to come from actual MSLT deployments and receipts, not just the availability of refurbished equipment.
Get ASX:VPR news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The downgrade puts EcoQuip's sales conversion at the centre of the story: Volt now needs trials, registrations and a larger fleet to produce measurable revenue before the revised FY26 range comes under pressure again.
Questions in the middle?
- How many of the planned EcoQuip site trials will convert into paying deployments?
- What cash balance and funding position will remain after the $3.0 million fleet investment?
- Can 4D Delta's platform growth continue to offset weaker EcoQuip performance in future quarters?
Sources
1-
Quarterly Shareholder Update (opens in a new tab)Official market announcement. Volt Group Limited · 2 Nov 2026 · voltgroup.com.au