Coast Entertainment unveils staged Dreamworld hotel and precinct plan

5 min read
8:44am on Tuesday 3rd of November, 2026 AEDT ~8am, 3rd Nov, 26
Coast Entertainment has outlined a staged plan to build a four-star hotel and entertainment, dining and retail precinct beside Dreamworld, with preliminary modelling indicating a completion value of about $330 million. The proposal comes as the company returns to profit and reports stronger visitation, cash generation and asset valuations.
- Indicative $200 million Dreamworld-branded hotel and $60 million entertainment, dining and retail precinct
- Preliminary modelling points to a levered IRR above 20% and about $330 million value on completion
- FY26 net profit of $6.1 million, with $35 million cash and no drawn debt
- No equity raising currently contemplated, with funding expected to combine cash, debt and potential partners
- Development remains subject to feasibility, approvals, cost validation, funding and board investment gates
 Add us as a preferred source on Google
Dreamworld expansion moves from land option to development plan
Coast Entertainment Holdings Limited (ASX:CEH) has put a price and timeline around its most ambitious use of the newly approved Coomera landholding: an indicative $200 million, 250-room Dreamworld-branded hotel alongside a roughly $60 million entertainment, dining and retail precinct.
The proposed destination would be built in stages, with the hotel targeted for completion around 2030 to 2031 and the entertainment precinct potentially opening earlier. Coast says preliminary modelling indicates a levered internal rate of return above 20% and a value on completion of about $330 million, but those figures are modelling outputs rather than forecasts or committed project outcomes.
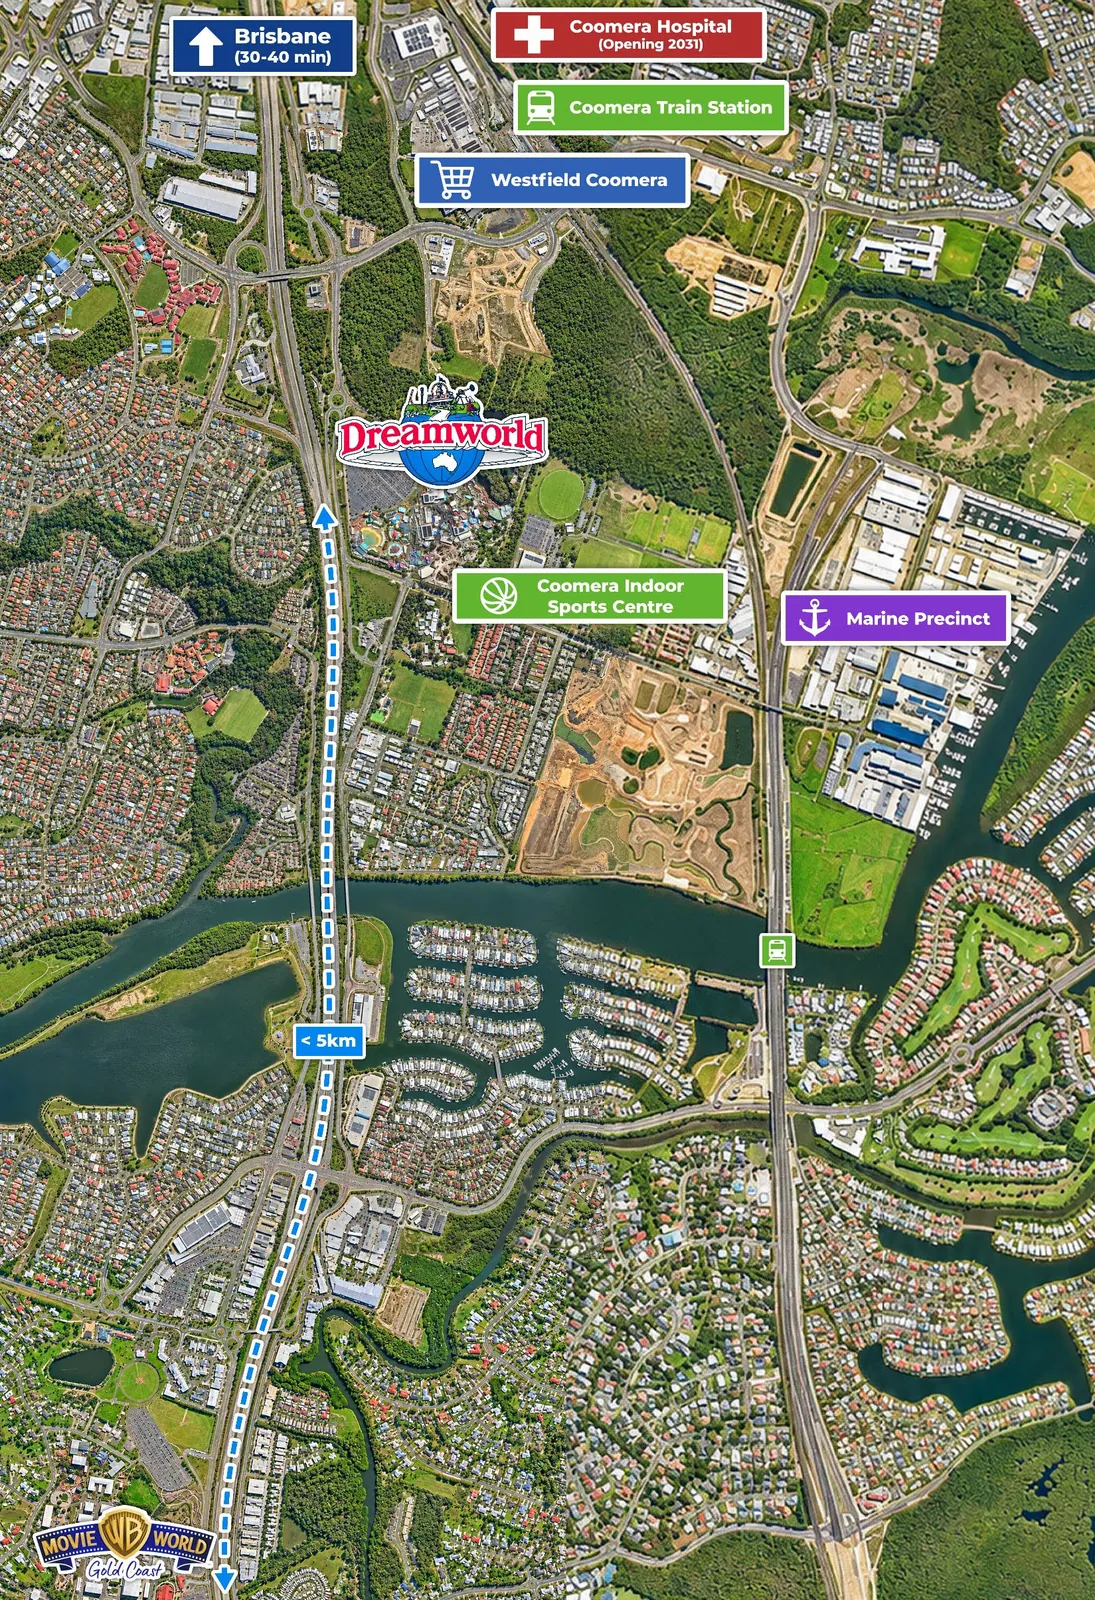
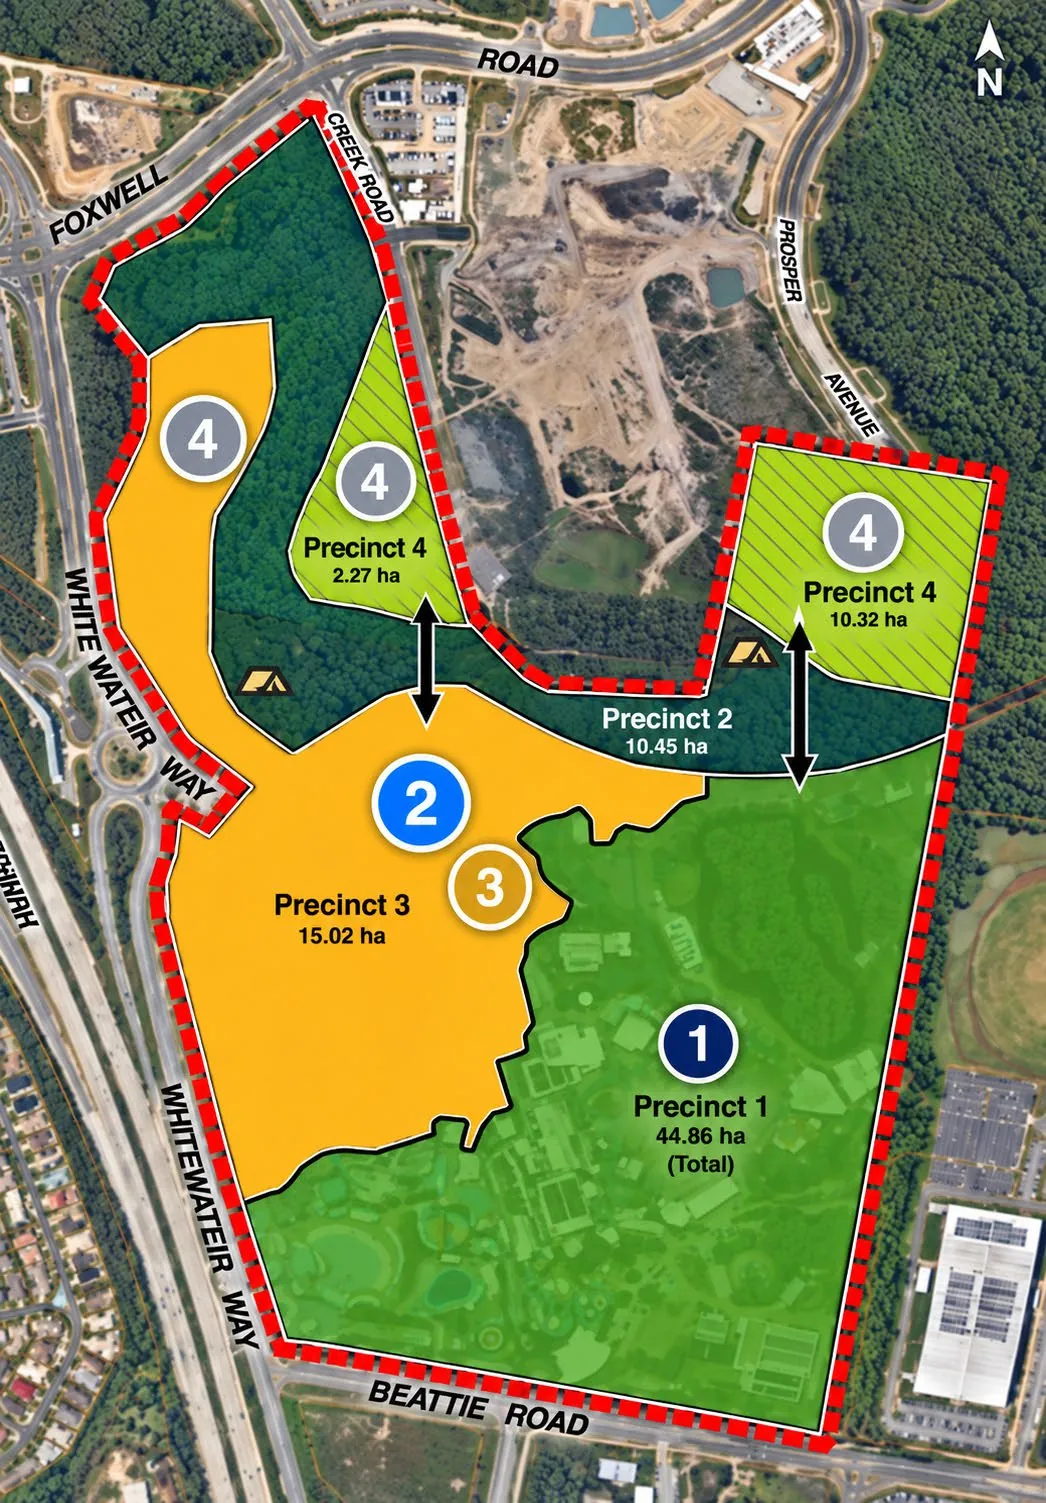
The plan follows the July Coomera development approval, which covered the company’s 55-hectare site. Coast has since engaged Barrenjoey to assess development, partnership, land-sale and status-quo options. The company says its review identified developing and owning the hotel and entertainment precinct as the highest-value pathway among those assessed, while leaving room for capital partners if they improve the risk-adjusted outcome.
Funding plan protects the theme park before expansion
Coast is pitching the project as an extension of its operating business rather than a replacement for it. Dreamworld would remain the anchor, with the hotel designed to convert day trips into short stays and the entertainment, dining and retail area intended to attract both park visitors and locals without requiring a theme park ticket.
The proposed funding mix includes existing cash, operating cash flow, new corporate or project debt, potential capital partners and eventual monetisation of surplus land. Management said no new equity raising is currently contemplated. Preliminary analysis suggests peak gearing could sit within the company’s 30% to 35% target range before falling as the developments reach stabilised operations.
That is an important distinction for shareholders. The proposal seeks to leverage the balance sheet without issuing new shares, but the final financing package has not been agreed. Coast says safety, maintenance and attraction renewal will be funded ahead of development spending, with board gates allowing the project to be paused, resized or reconsidered if costs, demand, financing or returns fail to meet the required tests.
Profit recovery gives Coast a stronger starting point
The development pitch arrives on the back of a materially improved operating year. FY26 theme park visitation rose 26.5% on a like-for-like basis to just over 2 million, operating revenue increased 19% to $116.5 million and EBITDA excluding specific items more than doubled to $18.8 million. Group EBITDA excluding specific items reached $13.8 million, while net profit after tax was $6.1 million.
Coast finished June with $35 million in cash, no debt and an undrawn $20 million banking facility. September year-to-date visitation was up 18.4%, revenue rose 12.5% and EBITDA excluding specific items increased 22.3% on the prior period, although the comparison was affected by the timing of a high-volume end-of-financial-year ticket sale.
The balance sheet also carries substantial valuation optionality. Independent fair values put Dreamworld at $295.9 million and SkyPoint at $51.7 million, while the company disclosed $136.1 million of available tax losses. Those values are gross and do not fully account for costs such as access works, infilling, car park relocation, transaction costs and compliance with approval conditions. The earlier Dreamworld valuation uplift established the scale of that land-related re-rating, but realising it will require construction, funding and execution rather than another valuation exercise.
Master planning and cost validation are the next tests
Coast says it is now progressing master planning, technical design and independent cost validation before development applications, engineering, tendering and financing arrangements. The indicative delivery window runs from 2028 to 2030, followed by the targeted hotel and precinct opening, subject to approvals and final investment decisions.
The central question is no longer whether the land has potential. It is whether a small listed theme park operator can convert that potential into a properly funded, commercially viable destination without compromising the recovery of the core park business. The answer will emerge through the company’s next decision gates, not through the preliminary return metrics presented at the AGM.
Get ASX:CEH news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The opportunity is now more tangible, but the next value test is costed design and committed funding rather than conceptual returns.
Questions in the middle?
- Will independent cost validation preserve the proposed hotel and precinct returns after construction, access and financing costs?
- Can Coast maintain its theme park investment program while funding development within the proposed gearing range?
- Will a capital partner improve risk-adjusted returns, or will Coast ultimately retain most of the project’s funding burden?
Sources
2-
AGM Addresses (opens in a new tab)Verified source. Coast Entertainment Holdings Limited · 3 Nov 2026
-
AGM Presentation (opens in a new tab)Verified source. Coast Entertainment Holdings Limited · 3 Nov 2026