AMD’s data centre surge points to another record quarter

AMD delivered a record fiscal third quarter as Data Center revenue nearly doubled year over year, pushing total revenue up 45% to US$13.4 billion. The company expects another sharp acceleration in the December quarter, but gaming weakened and customer warrant revaluations distorted GAAP earnings.
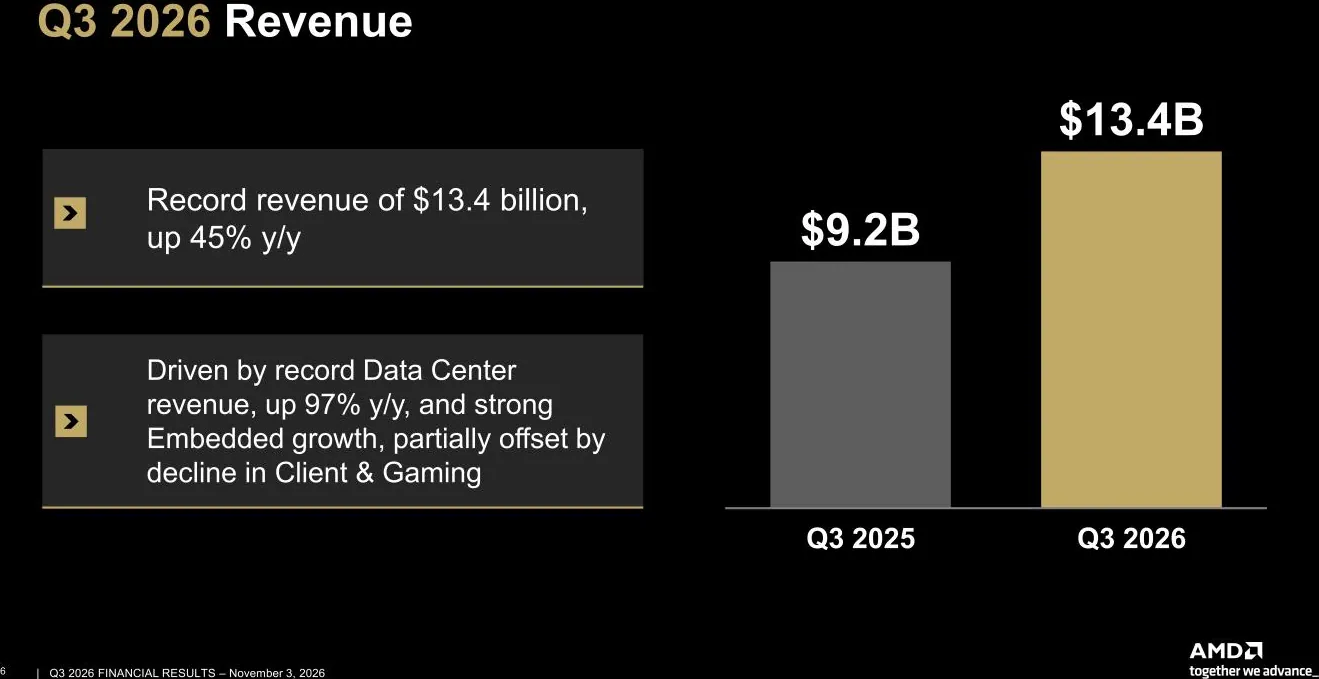
- Record US$13.4 billion quarterly revenue, up 45% year over year
- Data Center revenue surged 97% to US$8.5 billion
- GAAP diluted EPS rose 95% to US$1.46; non-GAAP EPS reached US$2.09
- Fourth-quarter revenue outlook of approximately US$17 billion, plus or minus 3%
- Client and Gaming revenue fell 8%, with gaming down 40%
 Add us as a preferred source on Google
AMD’s data centre business is now doing the heavy lifting. Advanced Micro Devices, Inc. (NASDAQ:AMD) reported record fiscal third-quarter revenue of US$13.4 billion, up 45% from a year earlier, as Data Center sales almost doubled to US$8.5 billion. The company’s fourth-quarter forecast points to another substantial jump, with revenue expected to reach approximately US$17 billion, plus or minus 3%.
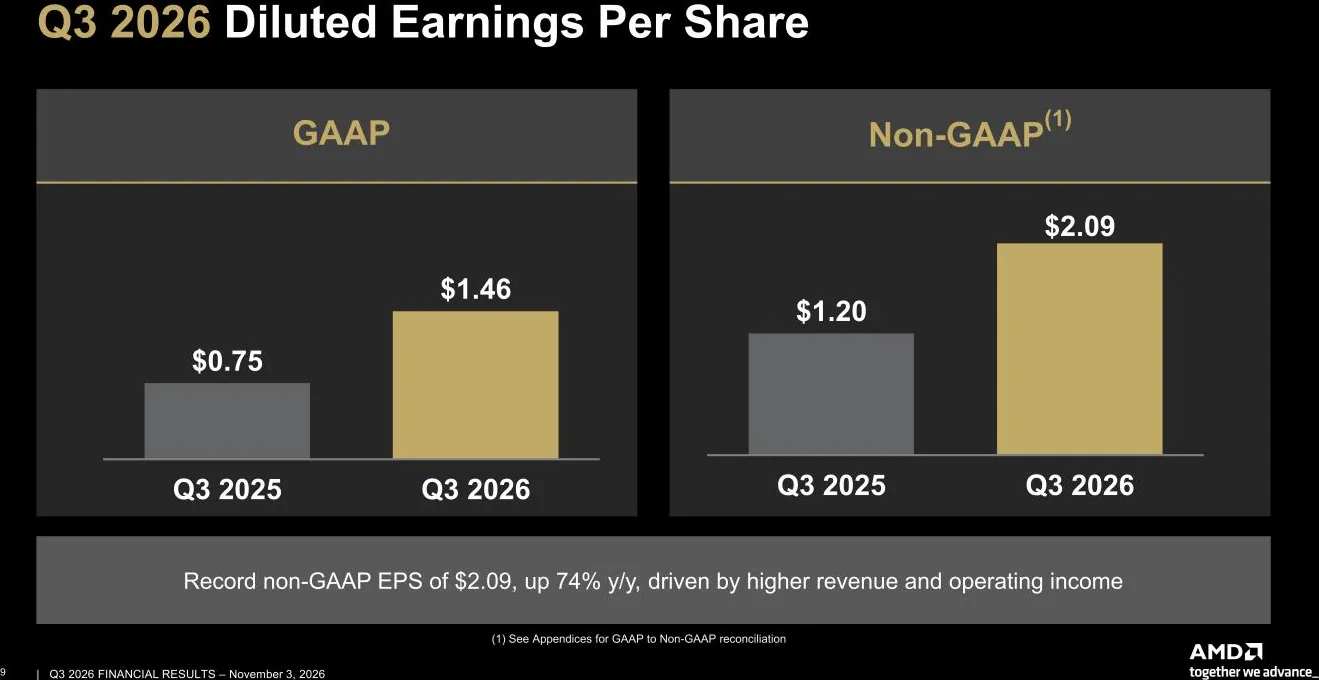
The quarter’s GAAP figures were strong: operating income rose 123% to US$2.8 billion, net income increased 95% to US$2.4 billion and diluted earnings per share reached US$1.46, compared with US$0.75 a year earlier. Non-GAAP operating income climbed 75% to US$3.9 billion, while non-GAAP diluted EPS rose 74% to US$2.09. AMD reported a 54% GAAP gross margin and a 56% non-GAAP gross margin.
Data Center Revenue Reaches US$8.5 Billion
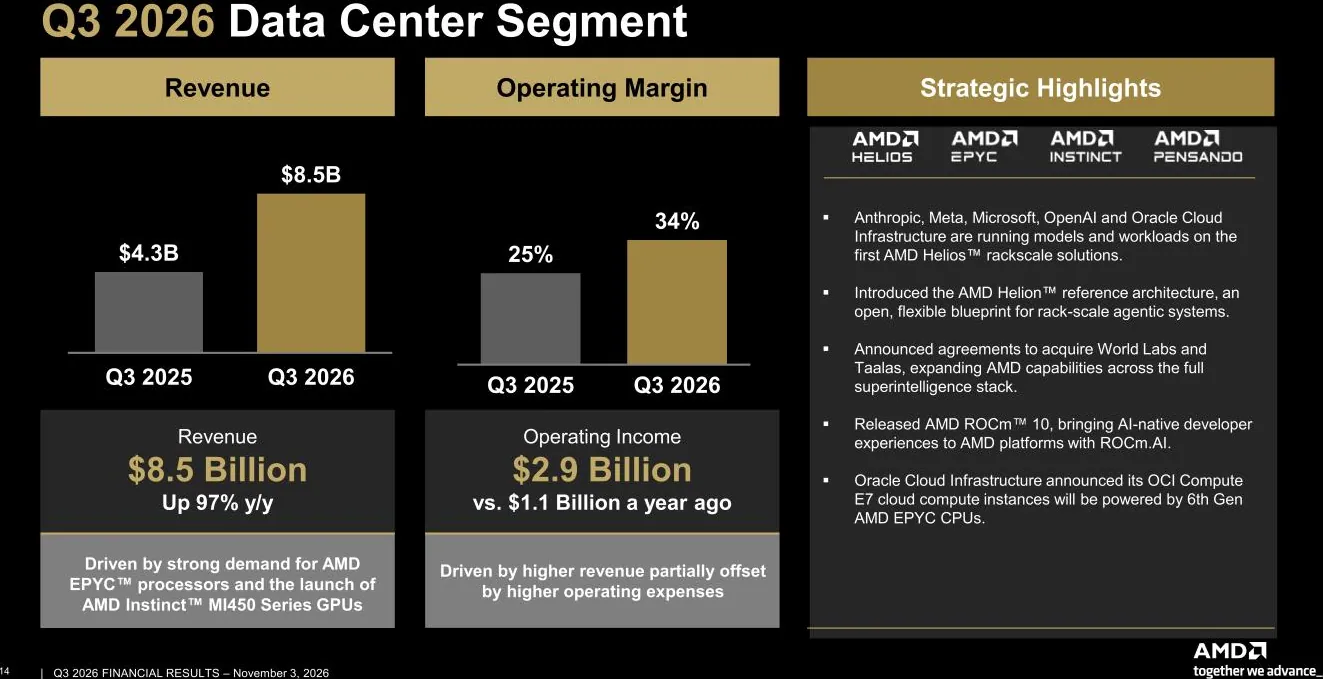
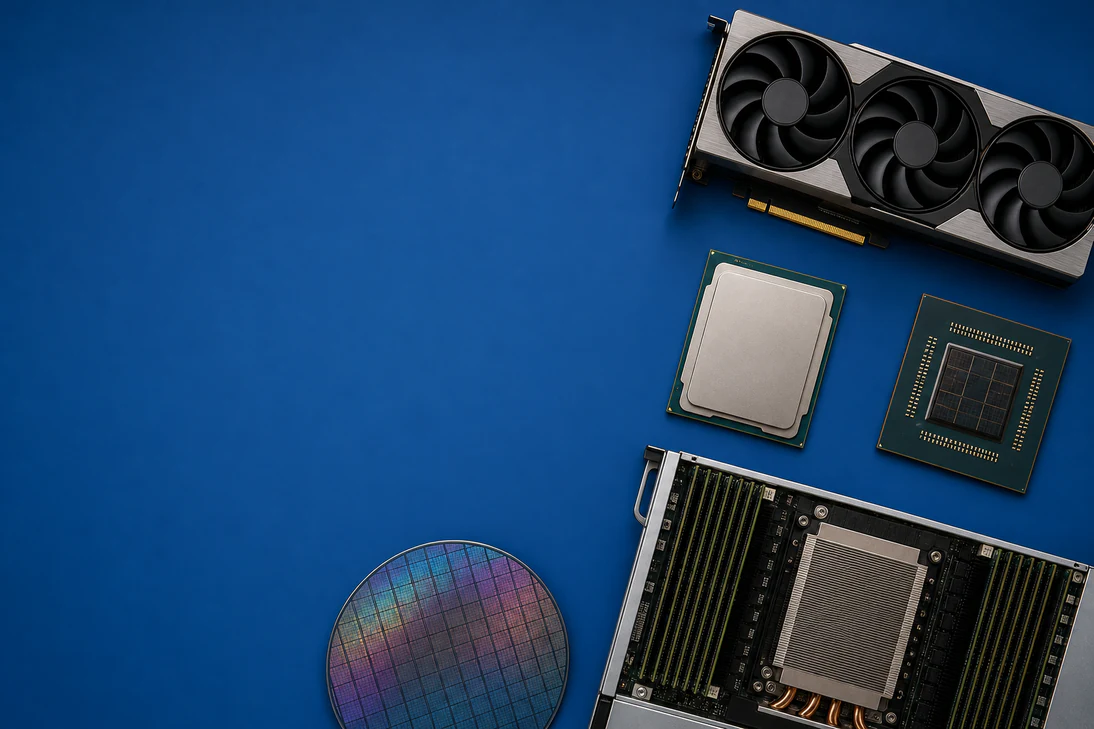
AMD said demand for EPYC processors and the launch of its Instinct MI450 Series GPUs drove the Data Center performance. Segment operating income rose to US$2.9 billion from US$1.1 billion, while the segment’s operating margin increased to 34% from 25% a year earlier.
The company also highlighted early deployments of its Helios rack-scale systems by Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure, alongside the release of its ROCm 10 software stack. AMD said it expects growth to accelerate as Helios and its next-generation “Venice” products move into production, although those statements remain subject to supply, execution, competitive and regulatory risks.
Gaming Declines as Embedded Expands
The growth story was not uniform. Client and Gaming revenue fell 8% to US$3.7 billion, with gaming revenue down 40% to US$773 million as semi-custom and graphics sales declined. Client revenue partly offset that weakness, rising 7% to US$2.9 billion on stronger Ryzen mobile processor sales.
Embedded revenue offered a second source of growth, increasing 29% to US$1.1 billion. AMD attributed the advance to aerospace and defence, automotive, communications and industrial end markets, with segment operating income rising 60% to US$453 million.
US$17 Billion Fourth-Quarter Target Raises Execution Stakes
AMD’s fourth-quarter outlook calls for revenue of approximately US$17 billion, representing roughly 66% year-over-year growth at the midpoint and a 27% sequential increase. Non-GAAP gross margin is expected to be about 55%, slightly below the 56% recorded in the latest quarter, while non-GAAP operating expenses are projected at approximately US$3.75 billion.
That forecast places the burden of proof on production and customer adoption rather than merely on demand. The balance sheet shows US$15.8 billion in cash, cash equivalents and short-term investments, but total debt has risen to US$7.1 billion after a US$4.75 billion senior notes offering completed in August. Inventory also climbed 35% from the previous quarter to US$11.5 billion, a figure that may become more important if shipment timing or product transitions do not proceed as planned.
GAAP earnings also require careful reading. AMD’s non-GAAP reconciliation excludes, among other items, US$523 million of stock-based compensation, US$534 million of acquisition-related amortisation and a US$1.097 billion change in the fair value of customer warrant liabilities. That warrant remeasurement was driven by AMD’s share price and other valuation assumptions, so it does not describe the underlying operating performance, but it did materially widen the gap between reported and adjusted results.
Get NASDAQ:AMD news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The next quarter will test whether Helios, MI450 and EPYC demand can convert an impressive Data Center run-rate into the US$17 billion forecast without a renewed drag from gaming, supply constraints or acquisition-related costs.
Questions in the middle?
- Can AMD scale Helios and Venice production quickly enough to support the projected 27% sequential revenue increase?
- How durable will MI450 and EPYC demand prove as customers adjust their AI infrastructure spending?
- What will the World Labs and Taalas acquisitions contribute after their expected closings, and how much additional dilution will they create?
Sources
1-
Results of Operations and Financial Condition; Regulation FD Disclosure (opens in a new tab)Official market announcement. SEC filing · Advanced Micro Devices, Inc. · 3 Nov 2026 · sec.gov