Scentre’s Westfield engine keeps gaining traction as occupancy holds at 99.8%

Scentre Group has reaffirmed its 2026 earnings and distribution targets after reporting higher customer traffic, stronger business partner sales and record-level occupancy across its Westfield portfolio. The update also puts a number on the group’s exposure to David Jones and details fresh debt funding and asset recycling.
- 554 million annual customer visits, up 3.1%
- Business partner sales rise to $30.5 billion
- Occupancy remains at 99.8%, with specialty rents up 5.6%
- David Jones contributes 1.8% of gross rent and 3.6% of annualised FFO
- 2026 FFO and distribution targets reaffirmed
 Add us as a preferred source on Google
Westfield occupancy stays near full capacity
Scentre Group (ASX:SCG) is carrying strong operating momentum into the final months of 2026, with annual customer visits reaching 554 million and portfolio occupancy holding at 99.8%. Business partner sales rose to $30.5 billion for the 12 months to 30 September, an increase of $1 billion on the prior comparable period.
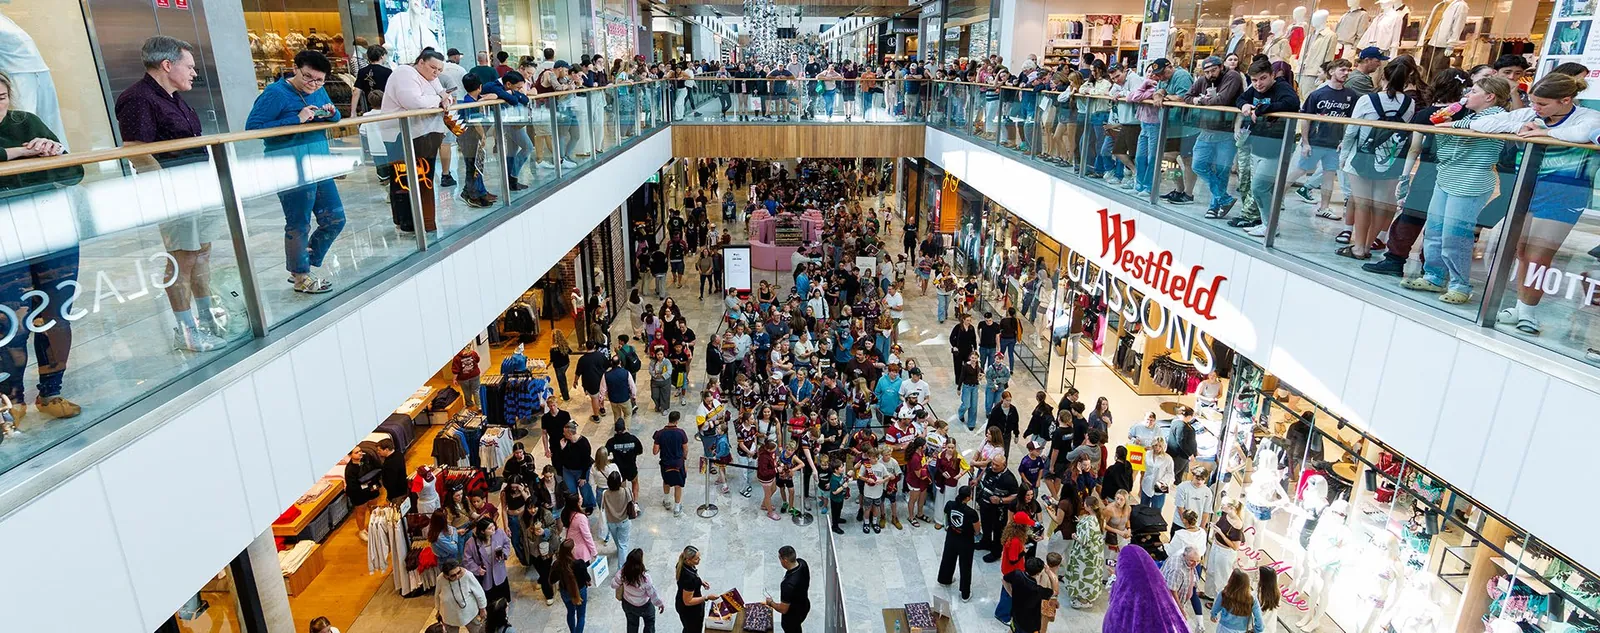
Traffic growth has continued into the current quarter. Visits from the start of the year to 1 November reached 452 million, up 3.2%, while sales rose 3.5% in the three months to September. Specialty store sales performed better, increasing 4.6% over that period, although the category data showed weaker momentum in leisure and sports, footwear and department stores.
The leasing figures give Scentre another source of support. The group completed 2,085 leasing deals in the nine months to September, achieving average specialty releasing spreads of 3.7% and rent escalations of 5.6%. Membership of the Westfield program also grew 10.8% to 5.4 million.
Asset sales and new debt reinforce capital flexibility
Scentre reaffirmed its target for 2026 funds from operations of at least 23.79 cents per security, representing growth of at least 4.25%, with distributions expected to rise by the same percentage to 18.473 cents per security. The targets remain subject to no material change in conditions.
The group settled the sale of a 50% interest in Westfield Mt Gravatt to Australian Retirement Trust for $882.5 million in late September, extending the asset-recycling strategy that was highlighted in its earlier Mt Gravatt transaction. In October, Scentre also issued US$750 million of 10-year guaranteed senior notes, equivalent to A$1.079 billion, with the obligations swapped into a floating-rate Australian-dollar liability at a margin of 141 basis points over three-month BBSW.
Available liquidity stood at $3.4 billion at 31 October, which Scentre said was sufficient to cover maturities until the second half of 2029. The new notes mark a return to the US bond market after six years, while the group’s earlier debt activity had included a tender process for US$1.312 billion of subordinated notes.
David Jones exposure remains quantified, not crystallised
Scentre used the update to quantify its exposure to David Jones amid recent media reports concerning the department store’s owner, Anchorage Capital Partners. David Jones occupies approximately 200,000 square metres across 17 Westfield destinations, generating $45 million of gross rent for Scentre in calendar 2026.
That rent represents about 1.8% of Scentre’s gross rent and approximately 3.6% of annualised FFO. David Jones has paid rent through 30 September and provided $45 million in bank guarantees across the Westfield Australia and New Zealand portfolio, of which Scentre’s share is approximately $30 million, or about eight months of gross rent. The filing does not state that a default or store closure has occurred, leaving rent payments and the value of those guarantees as the practical points to monitor.
Meanwhile, Scentre is continuing work on its destination pipeline. The $240 million Westfield Bondi redevelopment is due to open an upgraded Event Cinemas and new Kingpin entertainment offer in December, with the remainder progressing from 2027. The $30 million Westfield Penrith project is fully leased and due to open progressively from the second quarter of 2027, while the group’s Eastgardens proposal has been accepted for progression as a State Significant Development with potential for up to 1,300 dwellings.
Get ASX:SCW news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The operating numbers support Scentre’s 2026 targets, but the next test is whether sales growth, redevelopment openings and David Jones rent performance can hold together as capital commitments continue.
Questions in the middle?
- Will the 3.5% quarterly sales growth persist if weaker categories such as footwear and leisure remain under pressure?
- Can the Bondi, Penrith and Tuggerah projects translate high occupancy into durable rental growth as they open?
- Will David Jones continue paying rent on schedule, and how much protection would the bank guarantees provide if conditions deteriorate?
Sources
1-
Operating Update (opens in a new tab)Official market announcement. Scentre Group Trust 1 · 4 Nov 2026 · scentregroup.com