US$303 million net earnings after US$1.1 billion investment loss

Aflac’s third-quarter GAAP earnings plunged after a US$1.1 billion investment loss tied largely to portfolio repositioning, masking a more resilient operating result. The insurer raised its Aflac Japan margin outlook and outlined a potential US$1 billion capital release through reinsurance.
- GAAP net earnings fell 81.5% to US$303 million
- Adjusted earnings declined 8.5% to US$1.2 billion
- Aflac U.S. pretax adjusted earnings rose 31.5%
- Aflac Japan margin outlook lifted to 35%-38%
- US$804 million of shares repurchased during the quarter
 Add us as a preferred source on Google
A US$1.1 billion investment loss turned what might otherwise have been a solid operating quarter into a sharply weaker headline result for Aflac Incorporated (NYSE:AFL). Net earnings fell 81.5% to US$303 million, or US$0.61 a diluted share, from US$1.6 billion a year earlier, as the insurer repositioned its portfolio and booked a US$51 million tax valuation allowance.
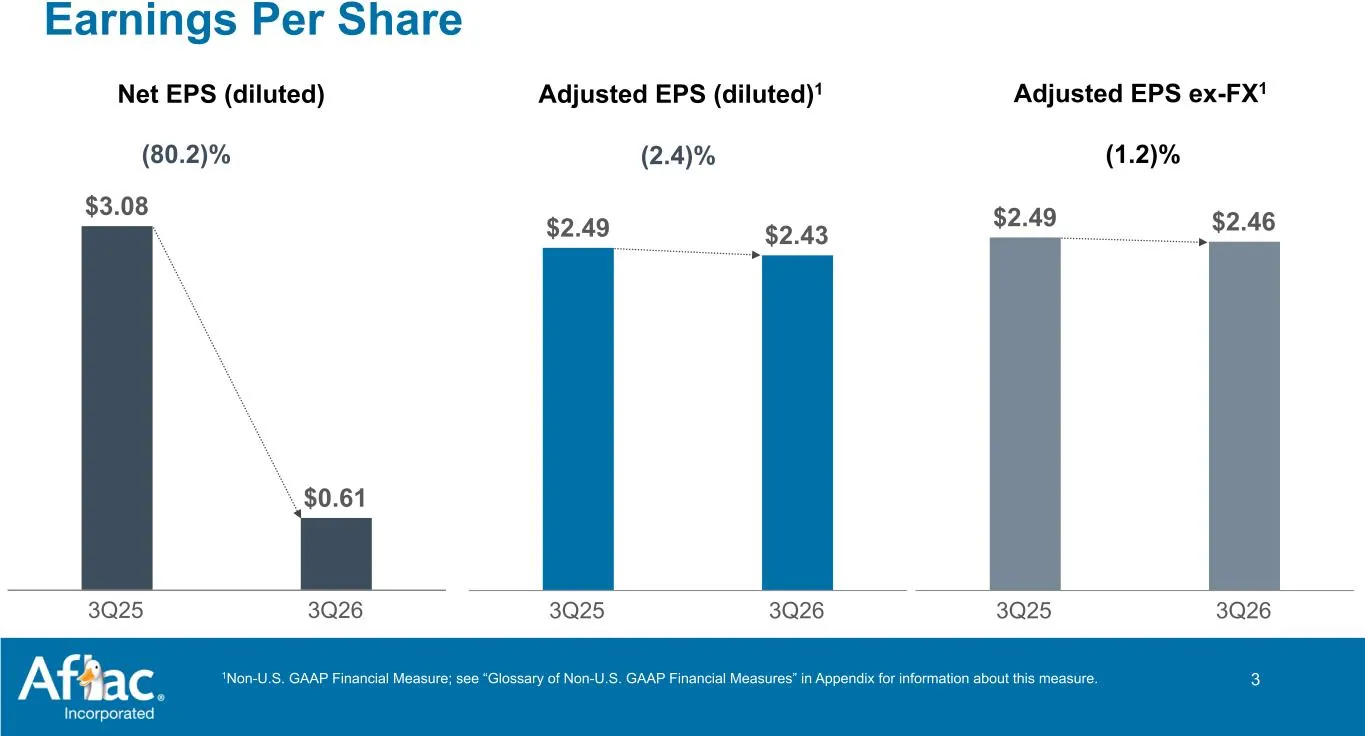
The more closely watched non-GAAP figures were less severe, but hardly buoyant. Adjusted earnings fell 8.5% to US$1.2 billion, while adjusted earnings per diluted share dropped 2.4% to US$2.43, or US$2.46 excluding the quarter’s foreign exchange effect. Aflac said adjusted earnings benefited from US$453 million of reserve remeasurement gains, highlighting how actuarial assumptions continued to influence the quarter.
Portfolio repositioning drives investment losses
The investment charge was dominated by US$842 million of losses on sales and redemptions, alongside US$146 million of losses from derivatives and foreign currency activities and US$102 million of expected credit losses. Aflac’s chief financial officer Max Brodén said the losses reflected a deliberate repositioning rather than a change to the insurer’s underlying investment strategy.
That repositioning included a further US$2.3 billion switch trade involving Japanese government bonds. Aflac said the transaction should lift future annual net investment income by more than US$30 million, while similar portfolio actions during the year have added more than US$80 million to annualised income. The trade-off is visible immediately in GAAP earnings, with the benefit dependent on the replacement assets delivering as expected over time.
US operations offset weaker Japan quarter
Aflac U.S. supplied the quarter’s clearest strength. Pretax adjusted earnings rose 31.5% to US$493 million as net earned premiums increased 3.3% to US$1.5 billion, benefits fell and the pretax margin widened to 27.7% from 21.7%. New sales rose 3.5% to US$403 million, helped by network dental, group life and disability products.
Aflac Japan moved in the opposite direction. Pretax adjusted earnings fell 15.2% in yen terms to ¥152.3 billion, while the margin declined to 44.4% from 52.2%. The company attributed the result primarily to higher benefits following actuarial assumption changes, and said US$40 million of cybersecurity expenses and enhancements in Japan added roughly 180 basis points to the segment’s expense ratio.
Reinsurance points to capital being redeployed
Aflac Japan ceded about ¥500 billion of cancer-policy reserves to Aflac Re Bermuda during the quarter. Management estimates the transaction will release approximately US$1 billion of capital over time, while also helping reduce risk and improve balance-sheet efficiency. That is an estimate rather than cash already available for distribution, and the filing does not specify when or how the capital would be redeployed.
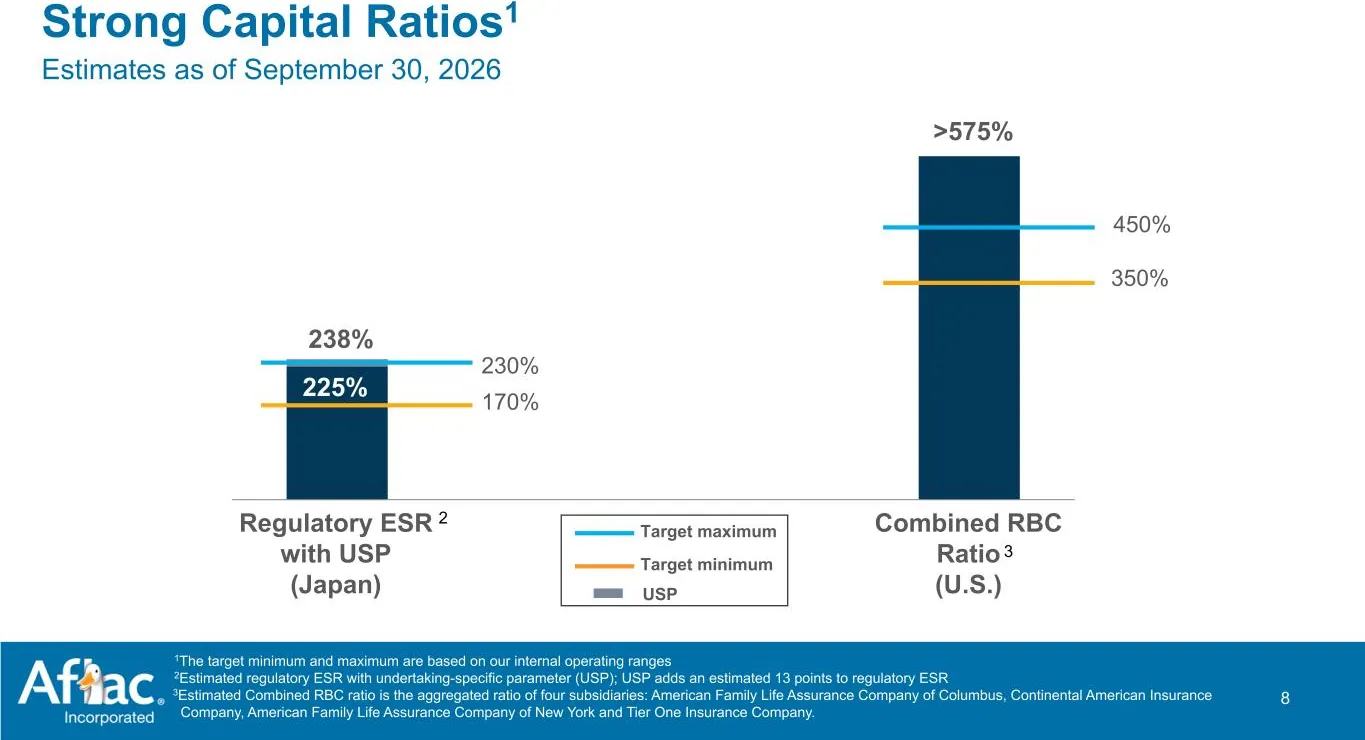
The company nevertheless raised its 2026 Aflac Japan pretax profit-margin outlook to 35%-38%, from 2026 expectations implied by its earlier 35%-38% range? Actually, Aflac explicitly said it raised the range to 35%-38%, while the U.S. pretax margin is now expected to finish above 17%-20%. Capital remains a central part of the story: Aflac reported estimated regulatory ESR of 225%, or 238% including the undertaking-specific parameter, combined RBC above 575%, and returned US$1.1 billion to shareholders in the quarter through US$804 million of buybacks and US$305 million of dividends.
The board also declared a fourth-quarter dividend of US$0.61 a share, extending Aflac’s run of annual increases to 44 years. The immediate question is whether the portfolio losses remain a one-off cost of improving future income, or whether credit losses, commercial property exposure and currency movements continue to make reported earnings more volatile than the adjusted figures suggest.
Get NYSE:AFL news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Aflac has improved its operating targets and capital position, but the investment repositioning will be judged by whether higher future income outweighs the near-term earnings damage.
Questions in the middle?
- How quickly, and in what form, will the estimated US$1 billion of reinsurance-released capital become deployable?
- Will the Japanese portfolio switch trades deliver the promised increase in recurring investment income without further material credit losses?
- Can Aflac sustain stronger U.S. margins while Japan absorbs cybersecurity costs and elevated actuarial volatility?
Sources
1-
Results of Operations and Financial Condition; Regulation FD Disclosure (opens in a new tab)Official market announcement. SEC filing · Aflac Incorporated · 4 Nov 2026 · sec.gov