CF Industries turns nitrogen strength into earnings and Blue Point momentum

CF Industries delivered stronger third-quarter earnings and cash generation as nitrogen prices and volumes improved, while construction began on its US$3.7 billion Blue Point One project. The result was helped by favourable market conditions, lower realised gas costs and a US$62 million business interruption insurance recovery.
- Third-quarter net earnings rose to US$436 million from US$353 million
- Adjusted EBITDA increased to US$833 million, up from US$667 million
- 97% available ammonia capacity utilisation reached in the first nine months
- Blue Point One construction began, with ammonia production targeted for 2029
- US$367 million spent on share buybacks during the quarter
 Add us as a preferred source on Google
Earnings rise as nitrogen pricing and volumes improve
CF Industries Holdings, Inc. (NYSE:CF) produced US$436 million in third-quarter net earnings attributable to common stockholders, up from US$353 million a year earlier, as stronger nitrogen pricing and higher sales volumes outweighed higher maintenance, freight and purchased-product costs. Diluted earnings per share rose to US$2.87 from US$2.19, while net sales increased 12% to US$1.86 billion.
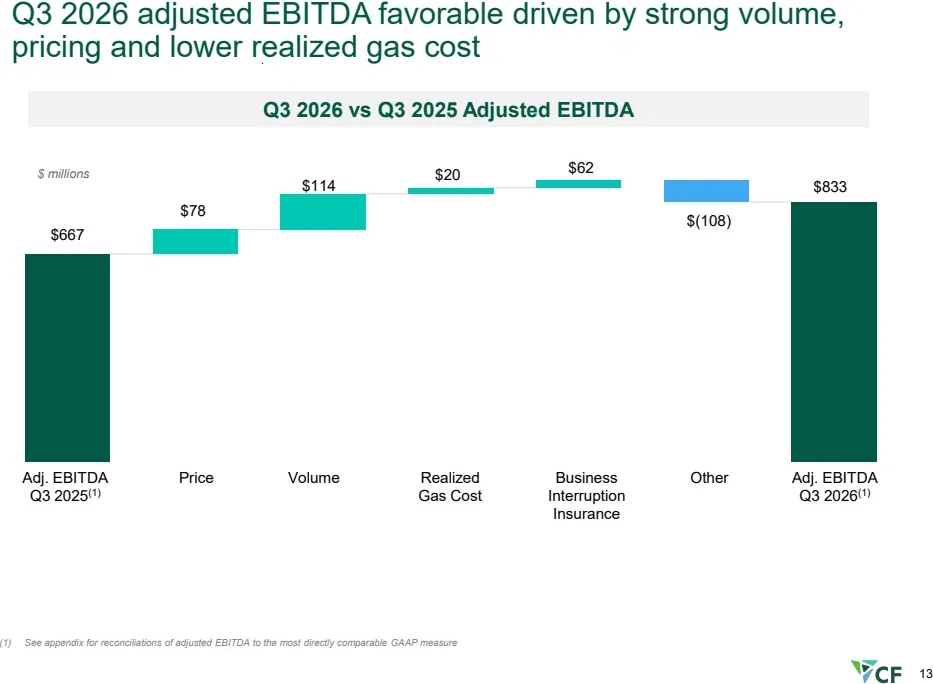
Adjusted EBITDA, a non-GAAP measure, climbed to US$833 million from US$667 million. GAAP EBITDA rose to US$822 million from US$671 million. The quarter included a US$62 million pre-tax business interruption insurance recovery linked to the Yazoo City outage, although the company’s presentation attributed the underlying improvement chiefly to pricing, volume and lower realised natural gas costs.
Operational execution keeps ammonia plants running hard
CF produced about 2.4 million tons of gross ammonia in the quarter and operated at 97% of available ammonia capacity during the first nine months. Management expects full-year gross ammonia production of approximately 9.5 million tons, with the estimate excluding capacity currently unavailable at the Yazoo City, Mississippi, complex.
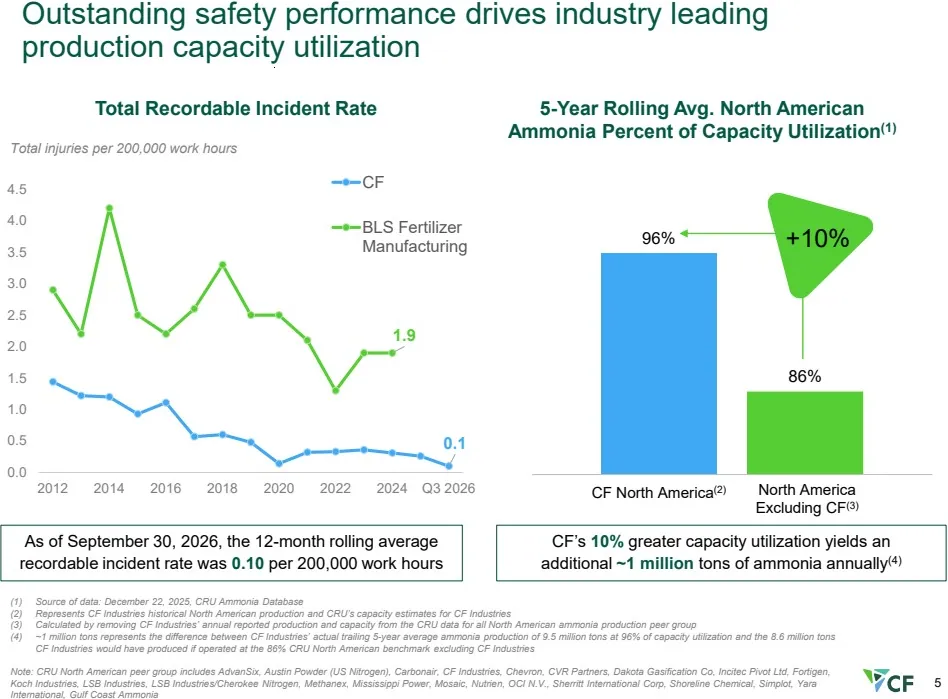
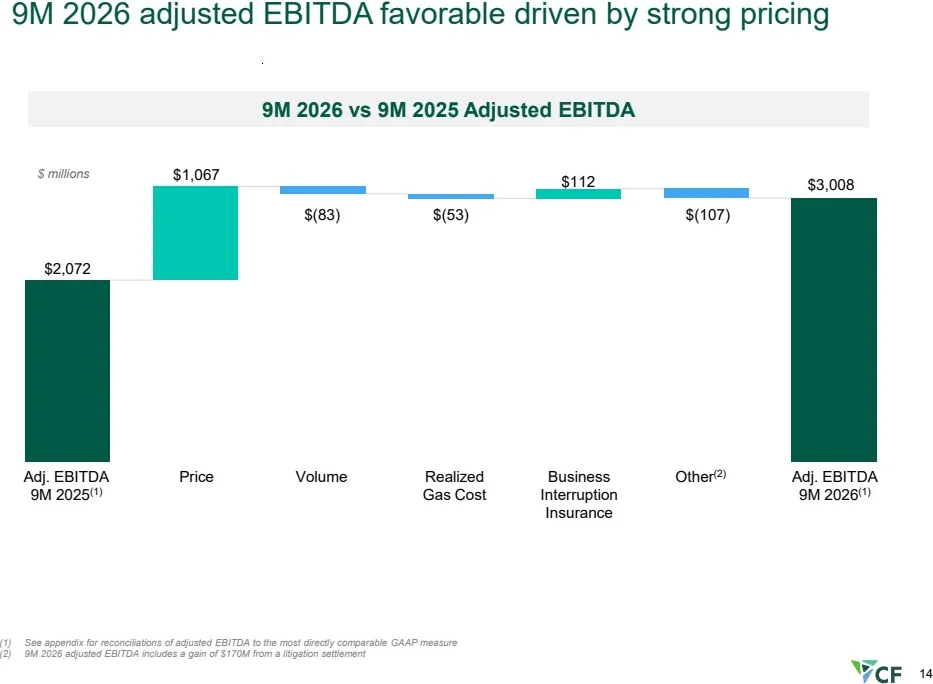
The outage continues to distort the product mix. Nine-month sales volumes were 5% below the prior-year period, mainly because of lower ammonium nitrate, ammonia and UAN sales. Excluding lost Yazoo City availability, CF said volumes were approximately comparable with the prior year for the nine-month period and 13% higher year-on-year in the third quarter.
Blue Point construction adds a long-dated growth bet
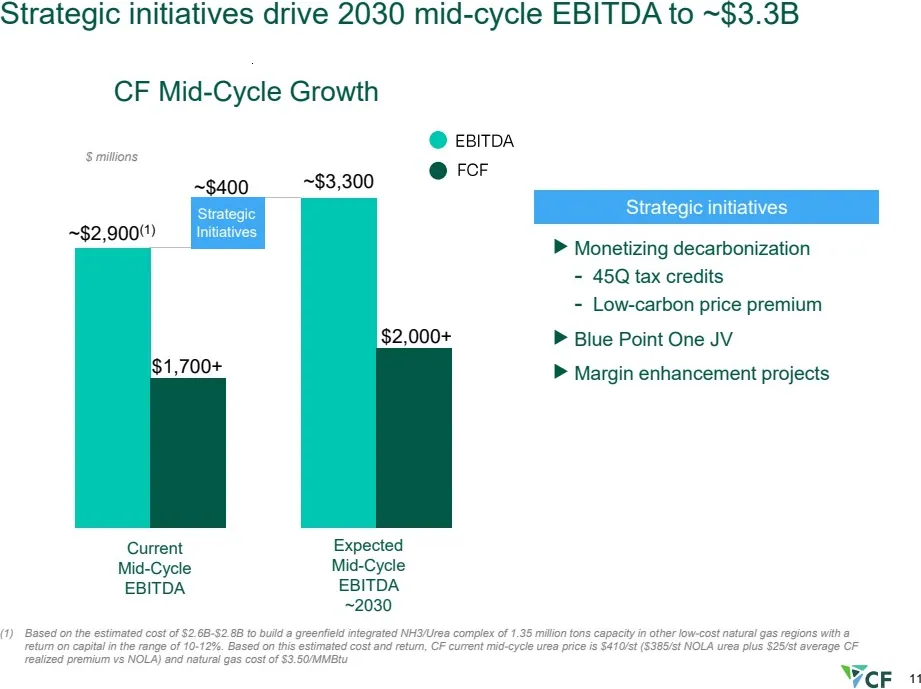
Construction on Blue Point One in Louisiana began in August, moving CF’s low-carbon ammonia plan from development into physical execution. The joint venture with JERA and Mitsui is designed to produce ammonia using autothermal reforming, with captured carbon dioxide dehydrated and compressed for transport and sequestration. CF owns 40%, while JERA owns 35% and Mitsui 25%.
CF expects the ammonia plant to cost approximately US$3.7 billion, including US$500 million of contingency, with production targeted for 2029. It also expects to spend about US$550 million on common facilities at the site. The group’s total 2026 capital expenditure forecast is approximately US$1.3 billion, but the amount funded by CF itself is expected to be about US$950 million after accounting for partner contributions.
Cash returns remain substantial despite project spending
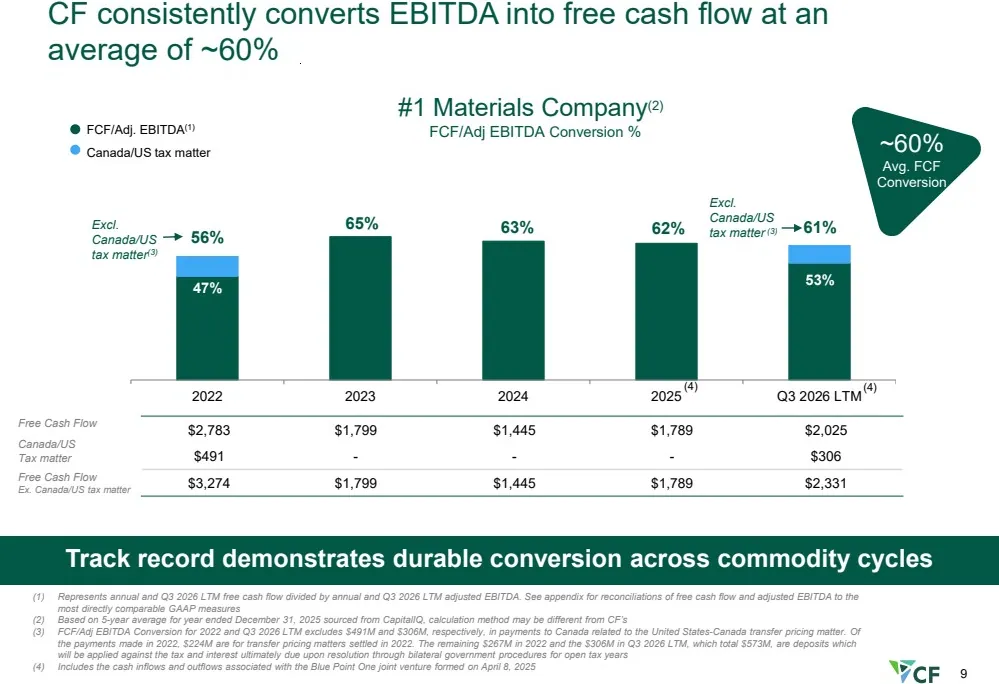
Trailing 12-month operating cash flow was US$3.08 billion and free cash flow was US$2.03 billion, although CF’s definition includes Blue Point joint-venture cash flows and a US$306 million deposit connected with a Canada-US transfer-pricing matter. Excluding that tax-related deposit, the company’s presentation showed free-cash-flow conversion of 61% of adjusted EBITDA, compared with 53% including it.
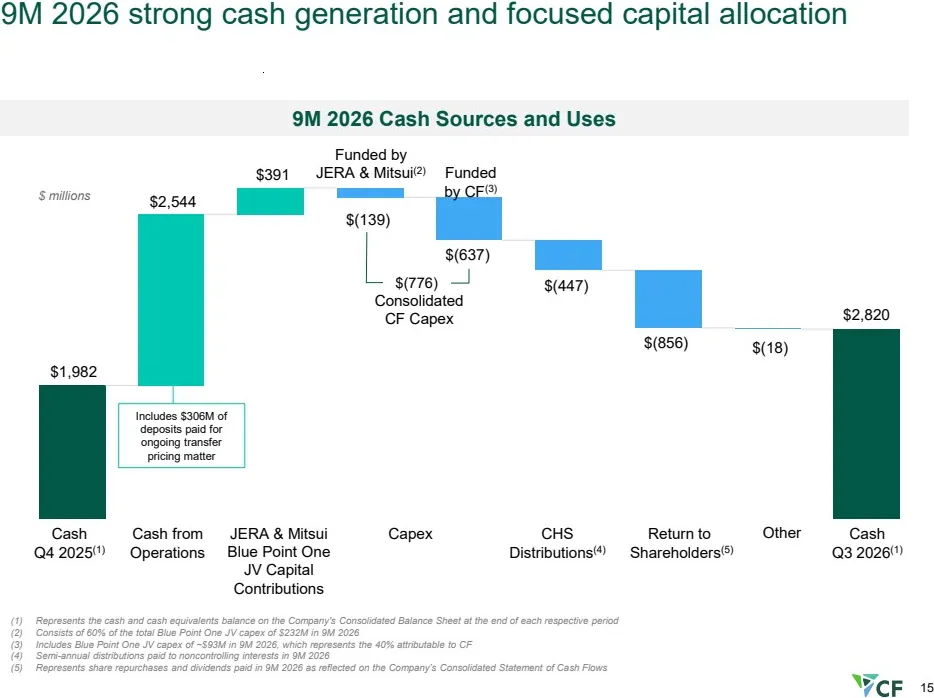
CF repurchased 3.0 million shares for US$367 million during the quarter and 5.2 million shares for US$612 million over the first nine months. About US$1.11 billion remains under the current US$2 billion authorisation, while the board has also declared a quarterly dividend of US$0.60 per share.
Nitrogen outlook rests on constrained global supply
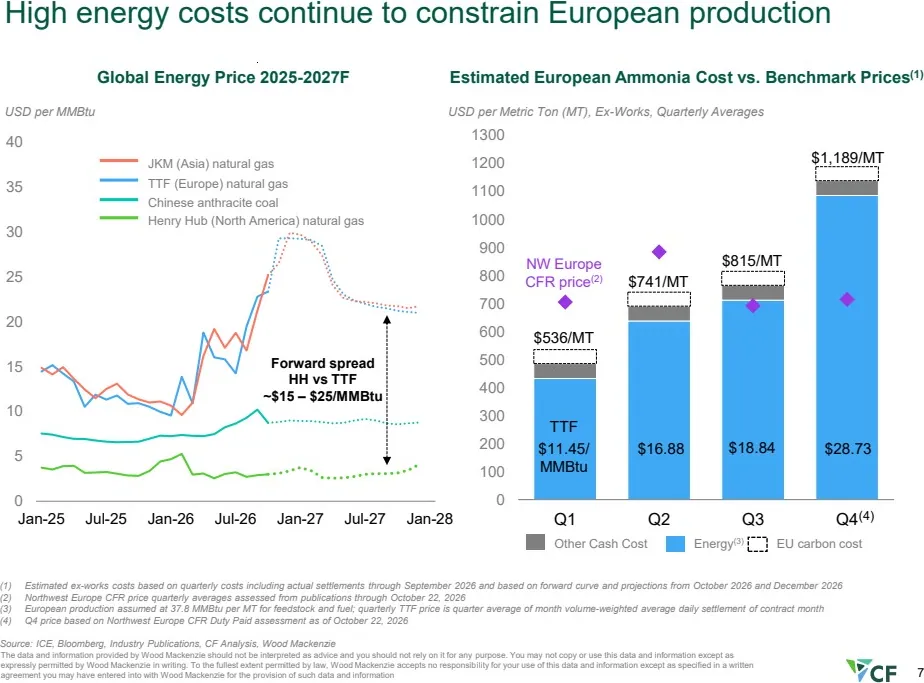
Management said nitrogen demand rebounded in North America, India, South America and Europe during the quarter after a slowdown late in the second quarter. It expects the market to remain constructive for low-cost North American producers, citing constrained supply, low channel inventories and production curtailments in Europe and Trinidad. Those claims are management’s assessment rather than an independent market forecast, and nitrogen remains exposed to commodity pricing, energy costs and geopolitical disruption.
The nearer operational catalyst is Yazoo City, which CF expects to restore during the first half of 2027. A separate carbon capture and sequestration project there remains scheduled for 2028. The more consequential test may arrive later: whether Blue Point can stay within its cost estimate and reach production in 2029 while the company continues returning capital to shareholders.
Get NYSE:CF news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
CF has momentum from pricing and utilisation, but the next phase depends on executing Blue Point and restoring Yazoo City without eroding cash returns.
Questions in the middle?
- Can nitrogen prices remain elevated if Chinese exports increase and disrupted Middle Eastern and Russian supply normalises?
- Will Blue Point One remain within its approximately US$3.7 billion plant cost as construction advances towards 2029 production?
- How quickly can Yazoo City return to service, and what final restoration costs will insurance cover?
Sources
2-
Results of Operations and Financial Condition (opens in a new tab)Official market announcement. SEC filing · CF Industries Holdings, Inc. · 4 Nov 2026 · sec.gov
-
Results of Operations and Financial Condition (opens in a new tab)Official market announcement. SEC filing · CF Industries Holdings, Inc. · 4 Nov 2026 · sec.gov