Eversource guides to US$4.62-US$4.70 recurring EPS for 2026

Eversource Energy narrowed its 2026 recurring earnings guidance after third-quarter GAAP profit fell, while a $26.5 billion investment plan and unresolved regulatory exposures shape the utility’s next phase. The guidance midpoint rose to US$4.66 per share despite lower year-to-date reported earnings.
- Third-quarter GAAP earnings fell 6% to US$346.0 million
- 2026 recurring EPS guidance narrowed to US$4.62-US$4.70
- Nine-month profit absorbed US$319.3 million in identified charges
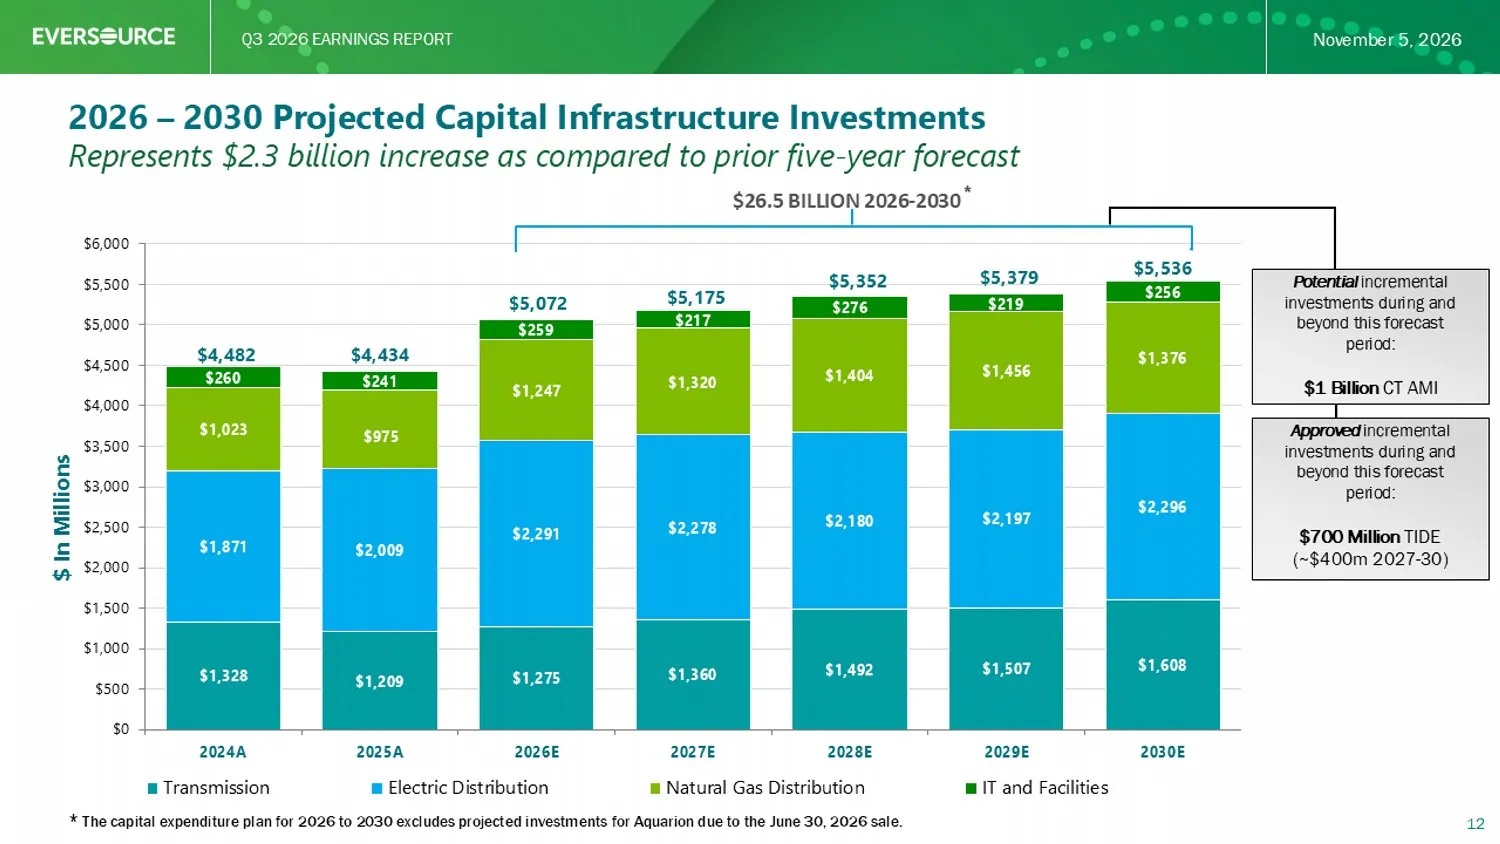
- US$26.5 billion capital plan runs through 2030
- FERC refund appeal remains unresolved, with payments due by May 2027
 Add us as a preferred source on Google
Eversource Energy (NYSE:ES) lifted the midpoint of its 2026 recurring earnings guidance even as third-quarter profit declined and its nine-month result was hit by a series of large regulatory and transaction-related charges. The New England utility reported GAAP earnings of US$346.0 million, or US$0.92 per diluted share, for the three months ended September 30, down from US$367.5 million, or US$0.99 per share, a year earlier.
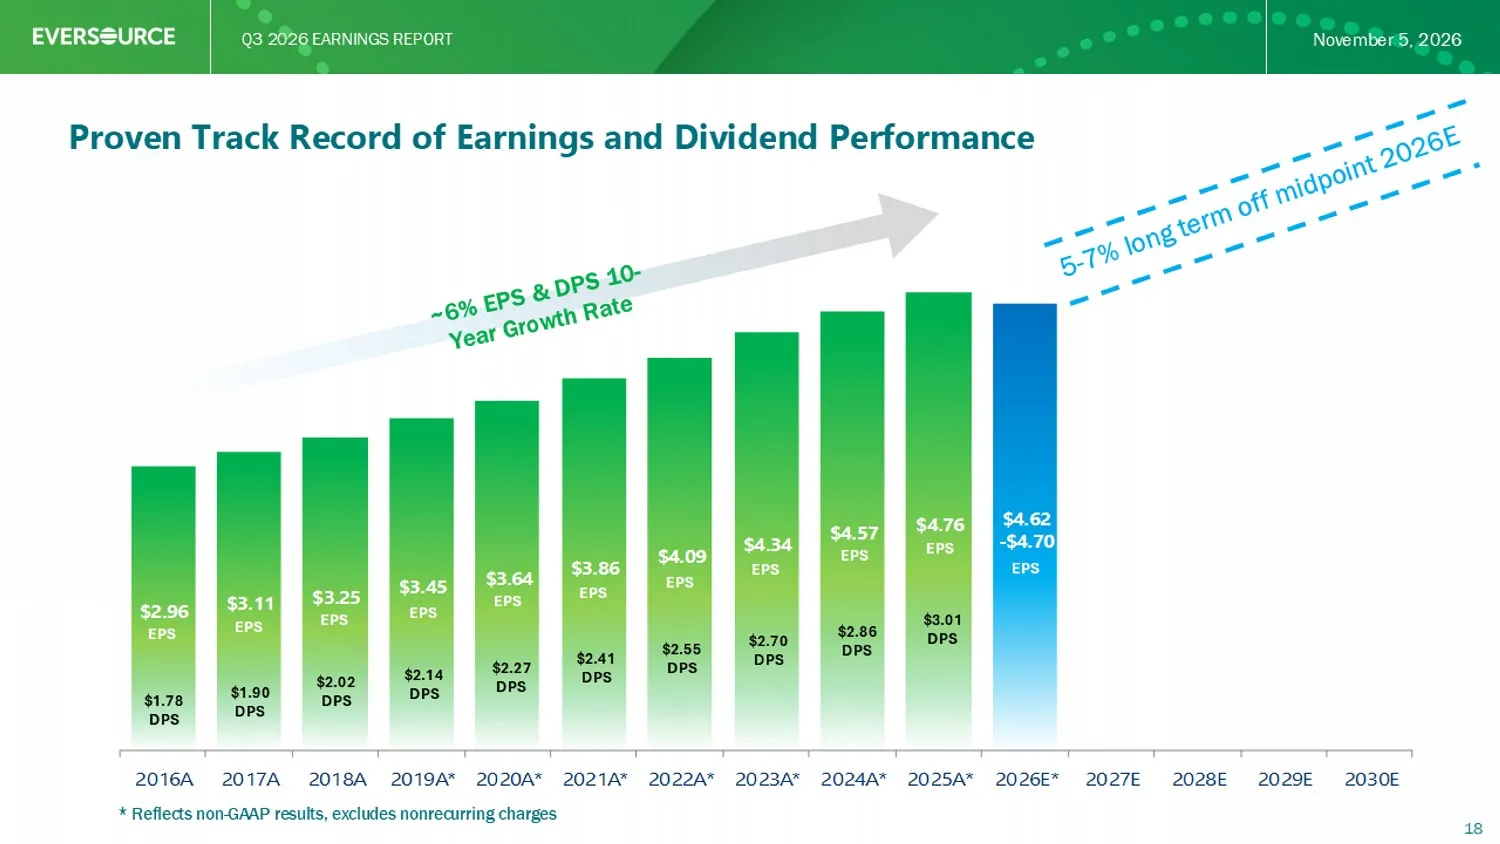
The more closely managed non-GAAP measure also weakened: recurring earnings per share fell to US$0.92 from US$1.19 in the prior-year quarter, with no adjustments recorded in the latest period. For the first nine months, recurring EPS was US$3.52, compared with US$3.64 in 2025. Eversource nevertheless narrowed its full-year recurring EPS range to US$4.62-US$4.70 and raised the midpoint to US$4.66, from earlier guidance of US$4.52-US$4.72.
Three Charges Reshape Nine-Month GAAP Earnings
Reported nine-month earnings fell to US$1.01 billion, or US$2.67 per share, from US$1.27 billion, or US$3.44 per share. The result included a US$111.4 million after-tax charge from the sale of Aquarion Water Company, a US$164.0 million charge linked to higher expected future payments connected with the 2024 offshore wind divestiture, and a US$43.9 million estimated refund charge following the Federal Energy Regulatory Commission’s reduction in the allowed transmission return on equity to 9.57%.
Those items are excluded from Eversource’s recurring figures, but they are not irrelevant to shareholders: they represent a completed disposal, a higher expected offshore wind obligation and a regulatory ruling with potential cash consequences. The company says the charges do not reflect ongoing operating performance, while its reported accounts show how materially they have affected the year to date.
Distribution Pressure Offsets Infrastructure Investment
Electric transmission earnings, excluding the FERC refund charge, slipped to US$182.0 million in the quarter from US$185.5 million. The company attributed the movement to the lower allowed return and higher interest expense, partly offset by continued investment in the transmission network. Electric distribution earnings fell more sharply, to US$200.9 million from US$221.6 million, after storm-cost disallowances, depreciation, interest and property taxes outweighed higher Massachusetts and New Hampshire base-rate revenue.
Natural gas distribution posted a quarterly loss of US$43.4 million, compared with a US$16.8 million loss a year earlier. Eversource pointed to a seasonal rate-design change affecting Massachusetts revenue recovery and higher depreciation. On a nine-month basis, however, the segment earned US$281.6 million, up from US$236.9 million, helped by rate increases in Massachusetts and Connecticut. The water business contributed no third-quarter earnings after Aquarion was sold on June 30.
Capital Plan Meets Regulatory and Funding Tests
Eversource is planning US$26.5 billion of infrastructure investment from 2026 to 2030, including transmission, electric distribution, gas distribution and technology projects. The company says the plan is US$2.3 billion larger than its previous five-year forecast, with a further US$1.7 billion of incremental opportunities identified. It also highlighted the US$700 million TIDE transmission project, a potential US$1 billion Connecticut advanced-metering investment and the Revolution Wind project’s completion as elements of its longer-term strategy.
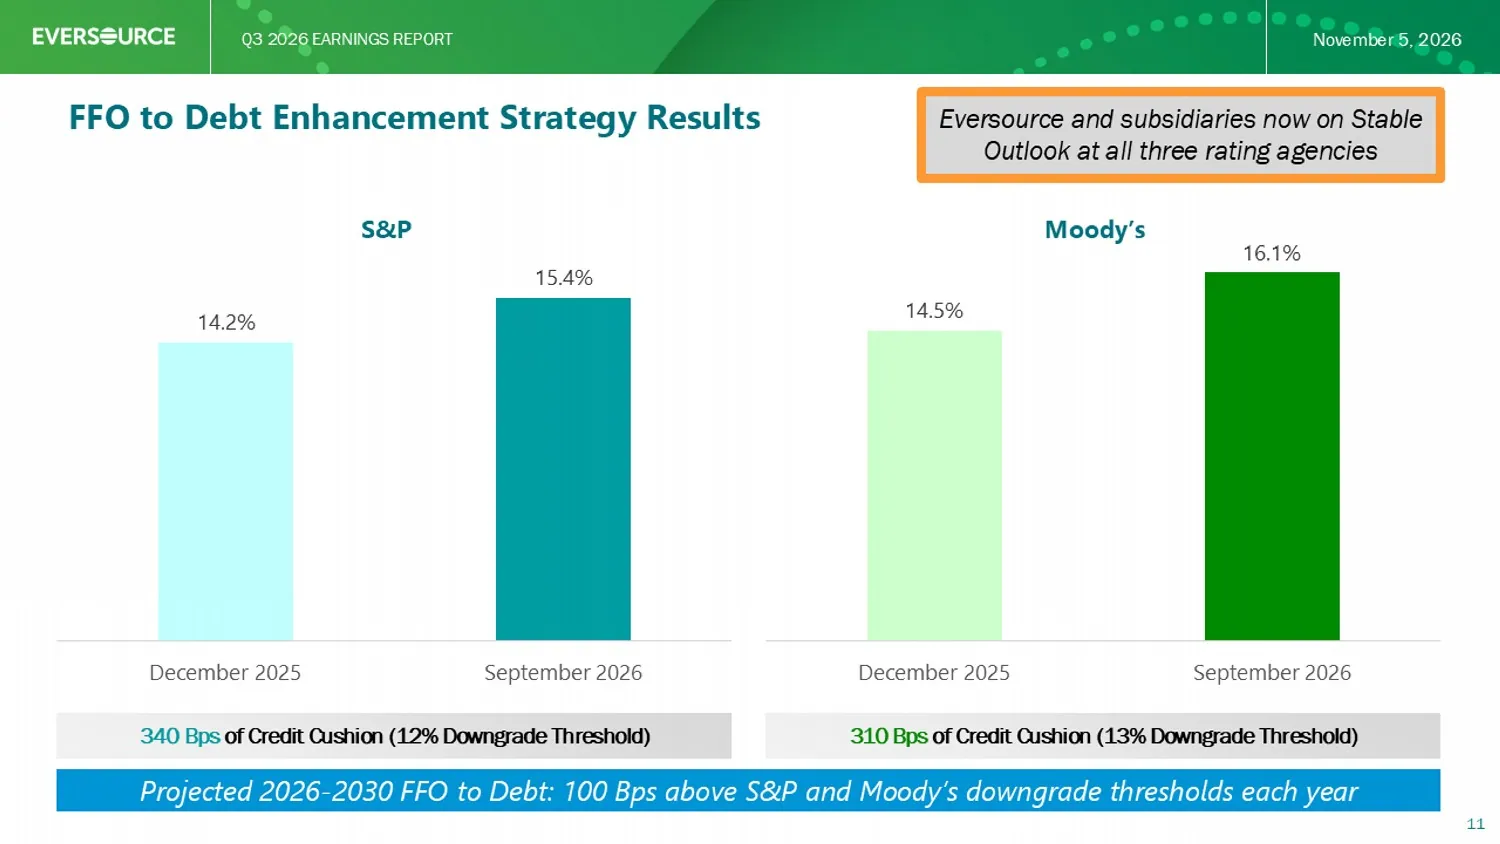
The financing backdrop has improved but remains central to that ambition. Eversource said its funds-from-operations-to-debt ratios rose to 14.2% under S&P’s measure and 15.4% under Moody’s at September, with both rating agencies’ downgrade cushions above their stated thresholds. The presentation also shows continued reliance on debt and equity markets, including a US$1.2 billion at-the-market equity programme and upcoming parent debt maturities in 2027.
FERC Refund Appeal Keeps Regulatory Risk Alive
The FERC dispute remains the most visible unresolved earnings and cash-flow issue. Eversource has appealed the 9.57% transmission return decision to the US Court of Appeals for the District of Columbia Circuit; the court expedited the appeal but denied a stay. The company’s presentation says refunds are due by May 2027, while a separate filing seeks a prospective 11.39% return, with a new rate expected to take effect on November 30.
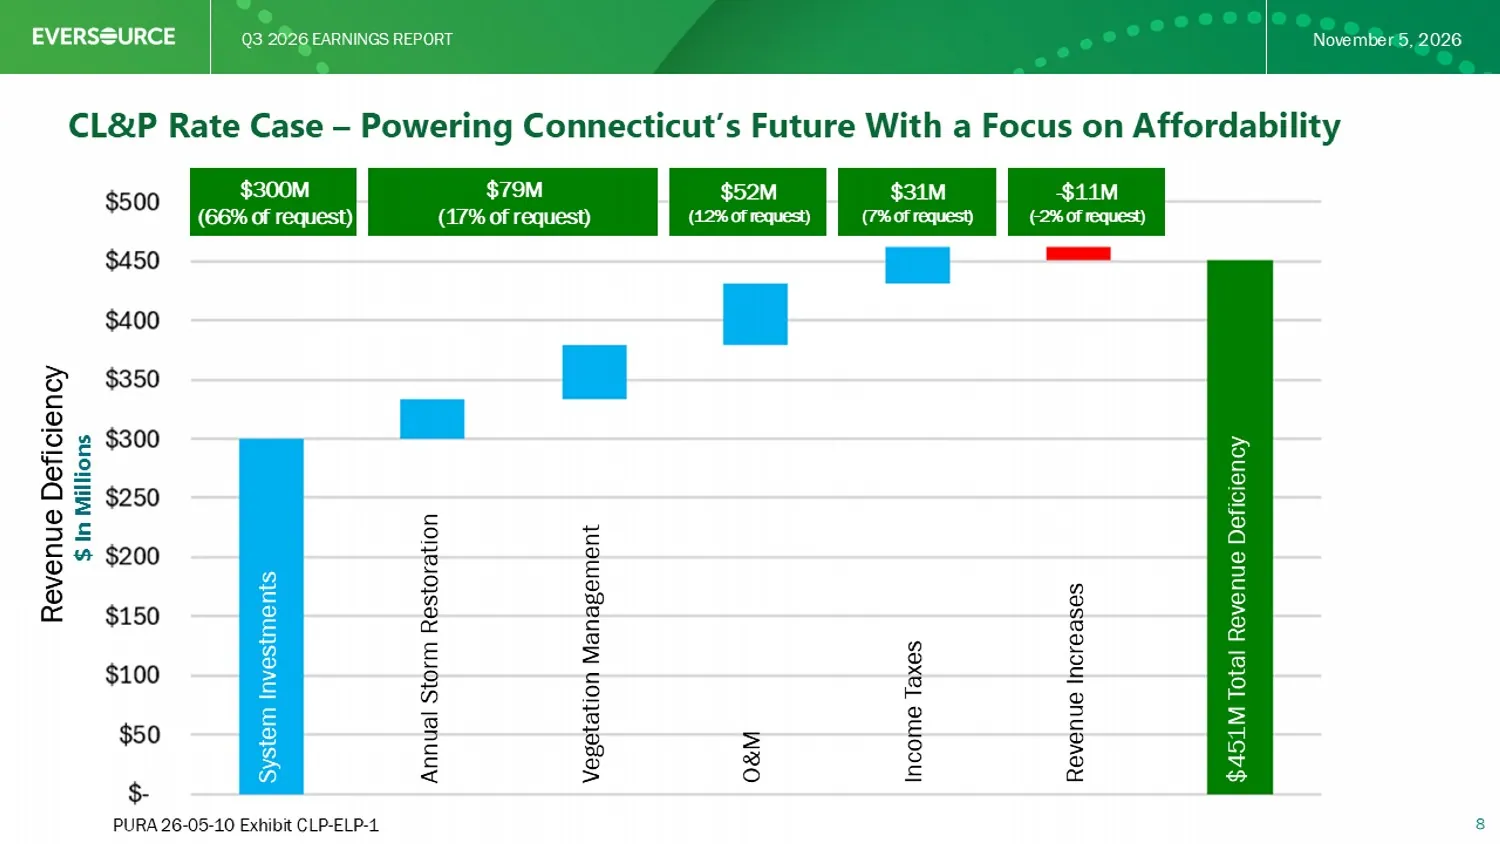
Other catalysts sit on a similarly regulatory timetable: Connecticut storm-cost securitisation is targeted for mid-2027 or early 2028, and rates from the CL&P case are expected to take effect in July 2027. The immediate question is whether those outcomes can support the enlarged capital programme without eroding the credit headroom Eversource has rebuilt.
Get NYSE:ES news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The higher guidance midpoint offers some support, but the investment case still depends on regulatory outcomes converting planned infrastructure spending into durable earnings while FERC and offshore wind liabilities remain unsettled.
Questions in the middle?
- How much of the FERC refund exposure will ultimately become a cash payment after the appeal and prospective ROE proceedings?
- Can the US$26.5 billion capital programme be funded while Eversource preserves its stated credit cushions and limits equity dilution?
- Will the CL&P rate case and storm-cost securitisation deliver the timing and recovery assumed in the company’s 2027-2030 growth outlook?
Sources
1-
Results of Operations and Financial Condition; Regulation FD Disclosure (opens in a new tab)Official market announcement. SEC filing · Eversource Energy · 4 Nov 2026 · sec.gov