Iron Mountain’s data centre pipeline lifts record quarter and dividend

Iron Mountain delivered record third-quarter revenue and AFFO, raised its 2026 outlook and lifted its quarterly dividend by 15%. Data centre leasing and asset lifecycle management are driving the company’s faster-growing businesses, although expansion is demanding substantial capital.
- US$1.99 billion record quarterly revenue, up 13.5%
- AFFO rose 16.6% to US$458.4 million
- 137 MW of data centre leases signed year to date
- Full-year 2026 guidance raised across key measures
- Quarterly dividend increased 15% to US$0.993 per share
 Add us as a preferred source on Google
Data centre leasing has become the sharpest edge of Iron Mountain Incorporated (NYSE:IRM), which signed 102 megawatts of new leases in the third quarter and 137 MW in the first nine months of 2026. The leasing push helped the company produce record quarterly revenue of US$1.99 billion, while management raised its full-year guidance and approved a 15% dividend increase.
Record revenue and AFFO growth
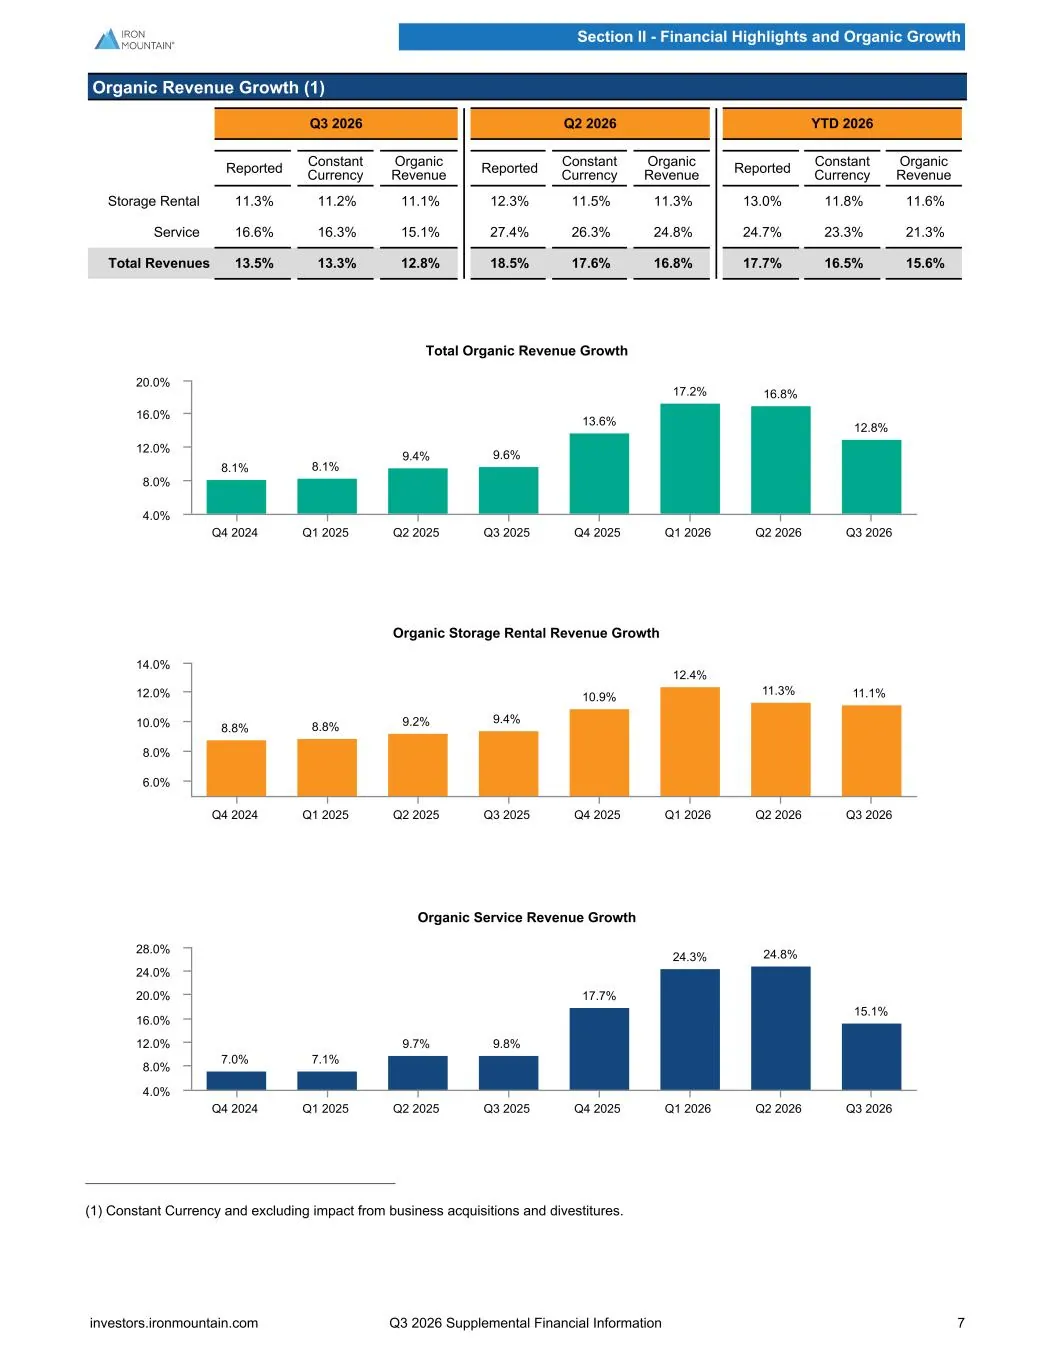
Third-quarter revenue increased 13.5% from a year earlier, with storage rental revenue up 11.3% to US$1.15 billion and service revenue up 16.6% to US$841.1 million. GAAP net income rose 49.4% to US$128.9 million, while diluted GAAP earnings per share increased to US$0.41 from US$0.28.
Iron Mountain’s non-GAAP measures also moved higher. Adjusted EBITDA climbed 13.3% to US$748.0 million, with the margin holding at 37.6%, while adjusted funds from operations, or AFFO, rose 16.6% to US$458.4 million, or US$1.53 per share. Normalised FFO per share increased 12.9% to US$1.05. The company presents these measures as supplements to GAAP results rather than replacements for net income or operating cash flow.
Data centres lead the growth portfolio
The Global Data Center business reported revenue growth of 34% to US$273.6 million, with Adjusted EBITDA rising to US$154.0 million and its margin expanding to 56.3% from 52.6% a year earlier. The operating portfolio stood at 544.6 MW, 97.2% leased, while total potential capacity reached 1,373.6 MW including capacity under construction and held for development.
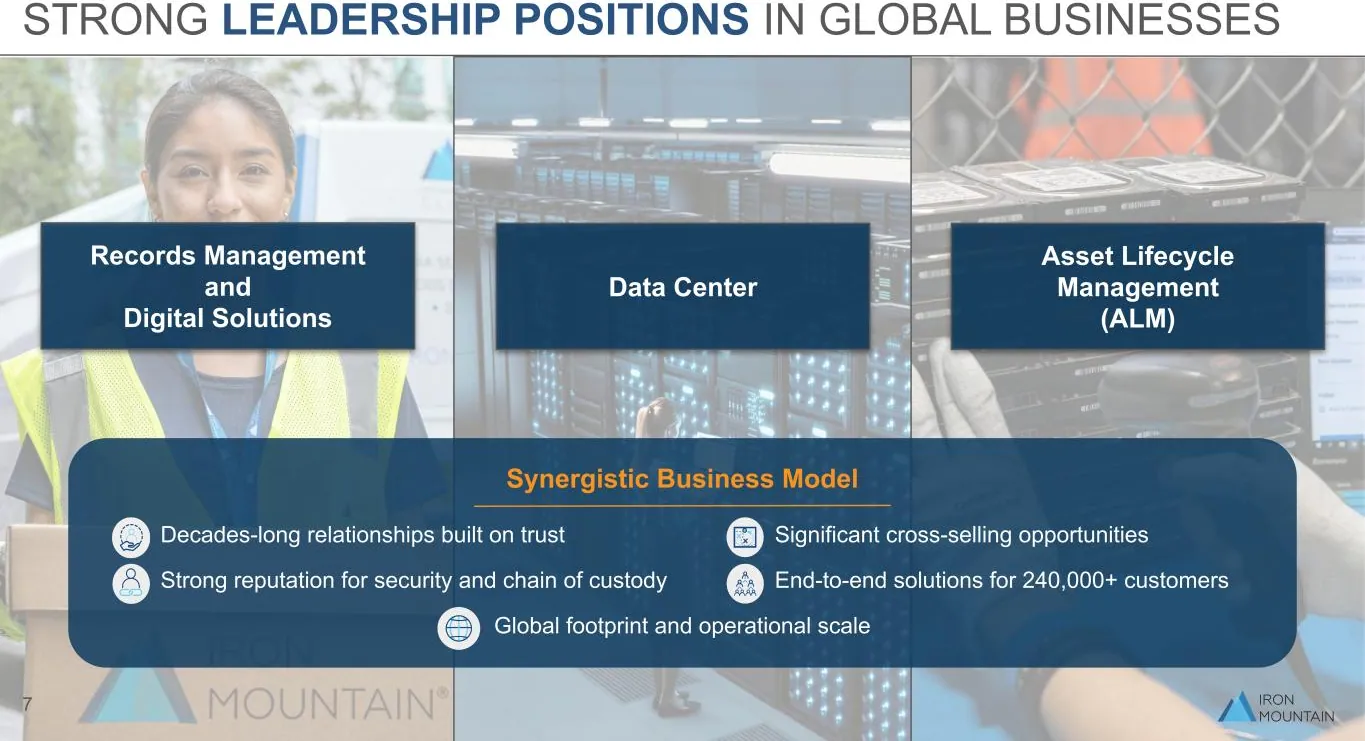
Asset lifecycle management and digital solutions were also part of the growth story. The company said its Corporate and Other segment, which includes ALM, generated US$283.9 million of quarterly revenue, up 34.5%, while presentation materials reported ALM revenue growth of 43% on a reported basis and 38% organically. Global Records and Information Management remained the earnings base, producing US$1.43 billion of revenue and US$630.0 million of Adjusted EBITDA.
Raised 2026 targets and larger dividend
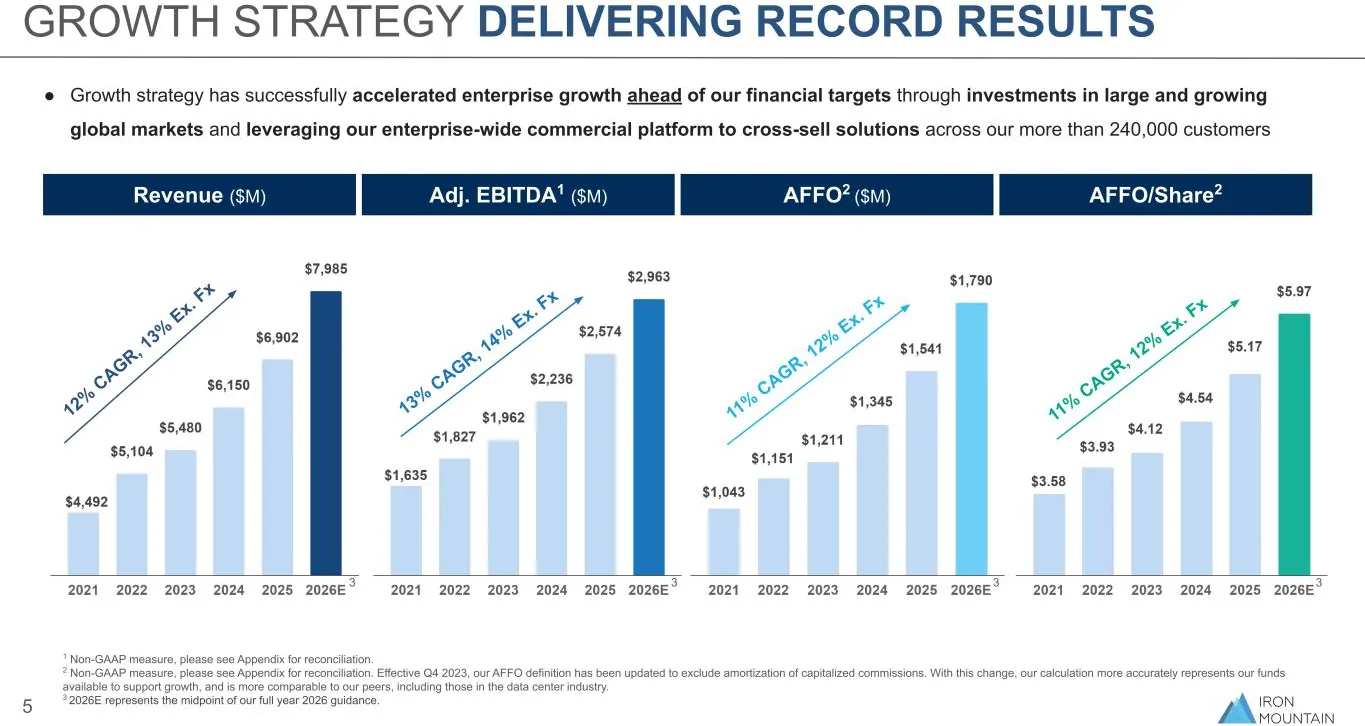
Iron Mountain now expects full-year revenue of US$7.95 billion to US$8.02 billion, Adjusted EBITDA of US$2.948 billion to US$2.978 billion, AFFO of US$1.78 billion to US$1.80 billion and AFFO per share of US$5.94 to US$6.00. The company’s fourth-quarter targets call for approximately US$2.03 billion of revenue, US$780 million of Adjusted EBITDA and US$473 million of AFFO. These guidance measures are non-GAAP and were not reconciled to GAAP in the release.
The board declared a fourth-quarter dividend of US$0.993 per share, up from US$0.86 in the preceding quarters. The increase takes the trailing-twelve-month AFFO payout ratio to 59.2% based on the supplemental data, leaving a stated cash-flow cushion, though the company is simultaneously committing heavily to expansion.
Capital spending and leverage remain the trade-off
Iron Mountain spent US$544.7 million on growth capital expenditure in the quarter, including US$464.0 million on data centres. Total cash paid for growth and recurring capital expenditure was US$618.0 million, up 18.0% year on year. At September 30, net lease-adjusted leverage was 4.8 times, within the company’s stated 4.5-times to 5.5-times target range, while total debt stood at roughly US$18.0 billion net of cash.
The immediate question is less whether demand exists than how efficiently the company converts its leasing pipeline into operating cash flow. Iron Mountain has 317.1 MW under construction and a further 511.9 MW held for development, with total expected investment of US$3.47 billion for listed development projects. The next results will show whether new capacity, pricing and cross-selling can keep outrunning the capital required to build it.
Get NYSE:IRM news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The raised outlook and dividend are supported by strong operating momentum, but data centre execution and capital discipline will determine how much of that growth reaches shareholders.
Questions in the middle?
- Can the 137 MW of signed year-to-date leases translate into the forecast data centre revenue growth as new capacity comes online?
- Will the US$3.47 billion development pipeline remain compatible with leverage of 4.5 to 5.5 times?
- Can ALM and digital solutions continue growing rapidly without eroding the margins of the established records business?
Sources
1-
Results of Operations and Financial Condition (opens in a new tab)Official market announcement. SEC filing · Iron Mountain Incorporated · 5 Nov 2026 · sec.gov