Alfabs expands mining hire range with $2 million pump acquisition

3 min read
12:32pm on Friday 6th of November, 2026 AEDT ~12pm, 6th Nov, 26
Alfabs Australia will pay $2.0 million upfront for J&J Vac’s underground mining pump assets, with a further $2.0 million available if it manufactures and hires or sells 25 additional units. The deal adds eight pumps, OEM rights and four transferred customer orders while the company continues its debt restructuring process.
- $2.0 million upfront acquisition of J&J Vac pump assets
- Eight UVU pumps and OEM manufacturing rights
- Four additional pump orders to transfer to Alfabs
- Up to $2.0 million in contingent consideration
- Settlement expected during November 2026, subject to conditions
 Add us as a preferred source on Google
Eight-Pump Acquisition Adds Hire-Ready Assets
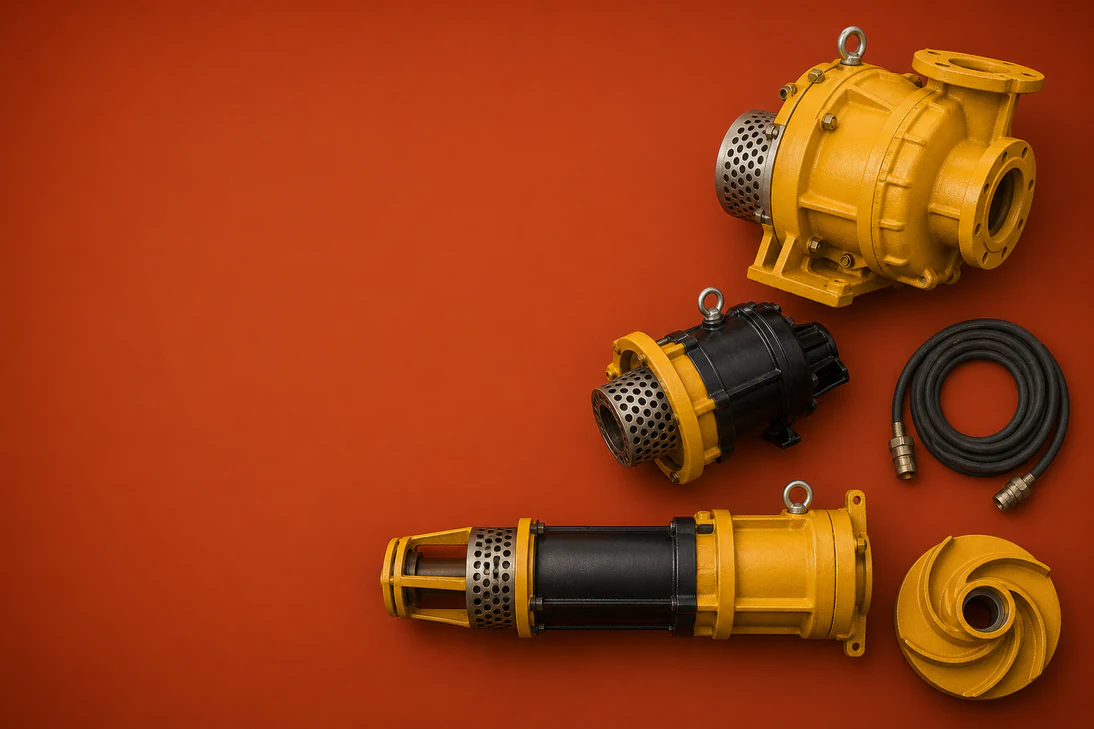
Alfabs Australia Limited (ASX:AAL) is buying its way into a new underground mining equipment line, agreeing to acquire the pump business assets of J&J Vac for $2.0 million upfront. The package includes eight UVU pumps, the right to manufacture the units as original equipment manufacturer, and four additional customer orders that will transfer to Alfabs at completion.
The transaction also carries an earn-out style component: Alfabs will pay $80,000 for each additional pump it manufactures and then hires or sells, capped at 25 pumps. That puts the maximum contingent consideration at $2.0 million, taking the potential total consideration to $4.0 million.
Pump Revenue to Sit Inside Existing Hire Operation
J&J’s UVU and MGUVU pumps are used to manage liquid and semi-solid material underground, principally in the New South Wales underground coal market. Alfabs said it had validated the pump performance internally and with existing end users, while describing the acquired units as hire-ready assets expected to contribute revenue and EBITDA from day one.
The company plans to fold the business into its existing hire operation, using established customer relationships, workshop capacity and technical expertise without adding overheads. OEM status also creates a potential aftermarket stream through spare parts, maintenance and servicing. The four transferred orders provide an immediate manufacturing workload, with J&J to provide transitional support.
Cash and Debt Facilities Fund the Expansion
Alfabs will fund the upfront payment from existing cash and debt facilities. The company said the acquisition is not expected to materially affect its balance sheet or previously communicated capital management priorities, although completion remains subject to customary conditions and is expected during November 2026.
The purchase lands while Alfabs is still pursuing its FY26 debt restructuring plan, a process previously described as a condition for any dividend restart. Alfabs said due diligence on Phase II of the restructure is well advanced, but the board has not yet reinstated the dividend.
Utilisation and Manufacturing Will Test the Thesis
The attraction of the deal is less the initial fleet count than the chance to combine equipment hire with manufacturing and aftermarket work across Alfabs’ underground mining customer base in New South Wales and Queensland. The filing does not disclose J&J’s historical revenue or EBITDA, however, leaving future utilisation, order conversion and the timing of further pump builds as the practical measures of whether the bolt-on delivers its expected returns.
Get ASX:AAL news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The acquisition gives Alfabs a new hire and manufacturing avenue, but its investment case now depends on completion, pump utilisation and progress on the still-pending debt restructure.
Questions in the middle?
- Will the four transferred orders convert into completed pump sales on the expected timetable?
- How quickly can Alfabs build utilisation across the eight acquired pumps and any additional units?
- When will Phase II debt restructuring be completed, and will it clear the path for dividend reinstatement?
Sources
1-
Alfabs acquires J&J Vac Pty Ltd pump business assets (opens in a new tab)Official market announcement. Alfabs Australia Limited · 6 Nov 2026 · alfabs.com.au