Lindsay Australia Finds Its Next Growth Phase After Crossing $1 Billion

6 min read
11:36am on Friday 6th of November, 2026 AEDT ~11am, 6th Nov, 26
Lindsay Australia has crossed $1 billion in annual revenue for the first time, with underlying EBIT up 37.7% to $60.4 million. The logistics group is now turning from major network investment to extracting returns, even as softer freight volumes and lower horticultural yields cloud FY27.
- FY26 revenue rose 26.2% to $1.072 billion, with underlying EBIT up 37.7% to $60.4 million
- Full-year SRT Logistics integration delivered $1.5 million of cost synergies and $5 million of redeployed capital
- Five-year Primary Connect contract is expanding Lindsay into secondary freight across 40 Woolworths stores
- FY27 capital investment is expected to reach approximately $57 million, with leverage potentially above target temporarily
- Management flagged softer freight volumes and lower citrus and avocado yields in the first half of FY27
 Add us as a preferred source on Google
Revenue Clears $1 Billion As Earnings Reach A Record
Lindsay Australia Limited (ASX:LAU) has reached a milestone that would have seemed less routine when the company was still a sub-$1 billion operator: group revenue exceeded $1 billion in FY26, rising 26.2% to $1.072 billion. Underlying EBIT climbed 37.7% to $60.4 million, while reported net profit increased 31.5% to $22.9 million.
The result was supported by the first full-year contribution from SRT Logistics and organic growth across Transport and Rural. Underlying earnings per share rose 10% to 7.6 cents, while the board declared a fully franked final dividend of 1.7 cents a share, taking the full-year distribution to 3.8 cents, unchanged from FY25. Net leverage ended at 1.92 times, down from 2.23 times at the half year and within Lindsay’s target range of 1.0 to 2.0 times.
The figures complete a substantial investment cycle. Lindsay says it has invested more than $250 million in fleet and property over five years, including more than $90 million in long-life rail assets. The strategic question has now shifted from how quickly the network can be built to how much operating leverage can be extracted from the assets already in place.
SRT Integration Delivers Scale And Geographic Balance
Transport revenue rose 32.9% to $763 million, with underlying EBIT up 25.9% to $77.4 million. Tasmania contributed 19% of Transport revenue, improving geographic balance and reducing seasonality after the full-year inclusion of SRT.
Management said the integration was executed to plan, with the company meeting its EPS accretion targets, redeploying $5 million of capital and realising $1.5 million in cost synergies. The integration has also widened Lindsay’s customer and service reach, although margins remain under pressure from competitive pricing, smaller order sizes and flat volumes. The company’s earlier SRT integration program had already expanded its national refrigerated logistics network, making FY26 the first period in which the acquisition contributed for a full year.
Lindsay added 25 high-productivity vehicle combinations during FY26. These combinations can carry 44 to 46 pallets, compared with 34 for a standard B-double using the same prime mover and driver, and now account for more than 13% of road kilometres travelled. Perth and Adelaide facility upgrades have also improved the company’s ability to receive and dispatch the larger combinations, including during rail interruptions on the East-West corridor.
Primary Connect Rollout Opens Secondary Freight Market
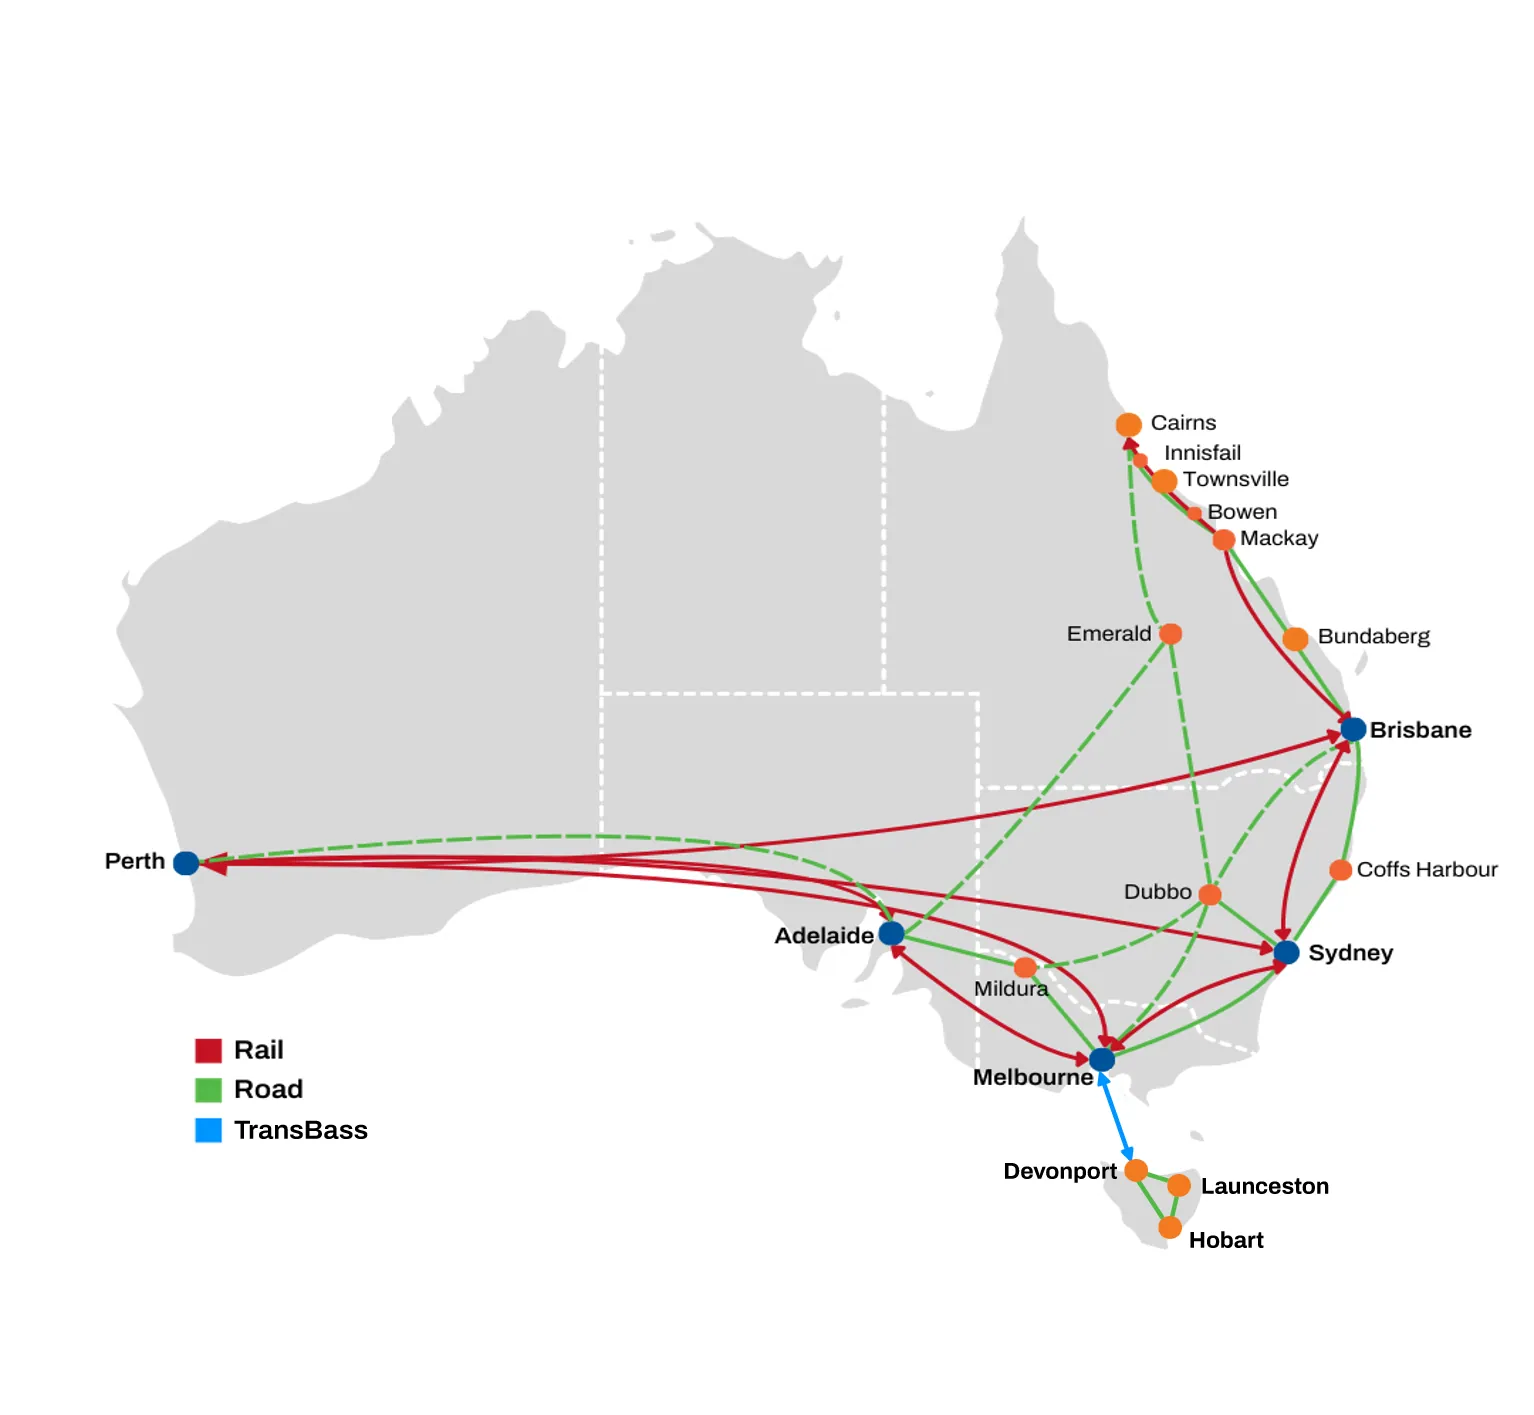
The next leg of the strategy is less about adding another depot than entering a market Lindsay has not traditionally served. Its five-year Primary Connect contract covers 40 Woolworths stores between Mackay and Cairns, with deliveries already operating from Mackay, Bowen and Townsville. Cairns is scheduled to commence in February 2027, while the final Big W volumes are expected in July 2027.
The presentation identifies the contract as a secondary freight expansion with returns above Lindsay’s 15% return-on-invested-capital hurdle. It is also the most immediate test of whether the enlarged network can produce additional earnings without reopening the capital-heavy expansion cycle. The rollout follows the company’s earlier North Queensland freight contract, which was linked to Woolworths stores and a planned investment in fleet and depot upgrades.
FY27 Begins With Softer Volumes And Higher Capital Needs
Management’s FY27 commentary is notably less buoyant on volumes. Consecutive interest-rate increases and cost-of-living pressures are weighing on consumer confidence, while customers are reporting greater price sensitivity and moderating spending. Freight volumes are lower than last year, with reduced citrus and avocado yields adding a seasonal drag across both Transport and Rural in the first half.
Rural nevertheless delivered another strong FY26, with revenue up 15.3% to $190.8 million and underlying EBIT up 22.8% to $12.2 million. Lindsay expects growing conditions to remain favourable in irrigated regions, although input costs are still elevated and volumes outside citrus and avocado are expected to be broadly in line with last year.
Capital investment is forecast at approximately $57 million in FY27, including $20 million of contracted Primary Connect growth capital weighted towards the first half. Lindsay says leverage may temporarily exceed the top of its target range, while also targeting net leverage below two times by 30 June 2027 and approximately 1.8 times in the AGM presentation. That makes the rollout’s timing, capital discipline and early operating performance more consequential than the headline revenue opportunity alone.
Get ASX:LAU news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
FY26 shows what the completed network can deliver; FY27 will test whether new freight volumes and higher asset utilisation can offset softer conditions without pushing leverage too far.
Questions in the middle?
- How quickly will the Primary Connect rollout convert contracted volumes into earnings and cash flow?
- Can Lindsay preserve margins while freight customers become more price-sensitive?
- Will lower citrus and avocado yields prove a temporary seasonal headwind or expose a broader volume slowdown?
Sources
1-
AGM Presentation and slides (opens in a new tab)Official market announcement. Lindsay Australia Limited · 6 Nov 2026 · asx.com.au