Estrella reveals a US$1.45 billion case for Timor-Leste limestone

Estrella Resources has outlined a potentially large limestone export business in Timor-Leste, with a 25 Mtpa base case carrying a US$1.453 billion after-tax NPV10 and 46% IRR. The headline economics are preliminary, however, with no Ore Reserve, binding offtake, project funding or key operating approvals yet in place.
- US$1.453 billion after-tax, pre-financing NPV10 at 25 Mtpa
- US$476 million Stage 1 and Stage 2 capital, with US$363 million peak funding
- 8 Mtpa starter case targets first revenue in Q3 2028, subject to FID
- 533 Mt JORC Resource includes 274 Mt Indicated and 259 Mt Inferred
- Funding, binding sales, approvals and port costs remain critical gates
 Add us as a preferred source on Google
Werumata delivers a sizeable preliminary project case
Estrella Resources Limited (ASX:ESR) has placed a US$1.45 billion project valuation on the table for its Werumata Limestone Project in Timor-Leste, but the number comes from a conceptual study rather than a construction-ready mine plan. The 25 million-tonne-per-year base case forecasts an after-tax, pre-financing NPV10 of US$1.453 billion, a 46% IRR and a 3.5-year payback over a 20-year mine life.
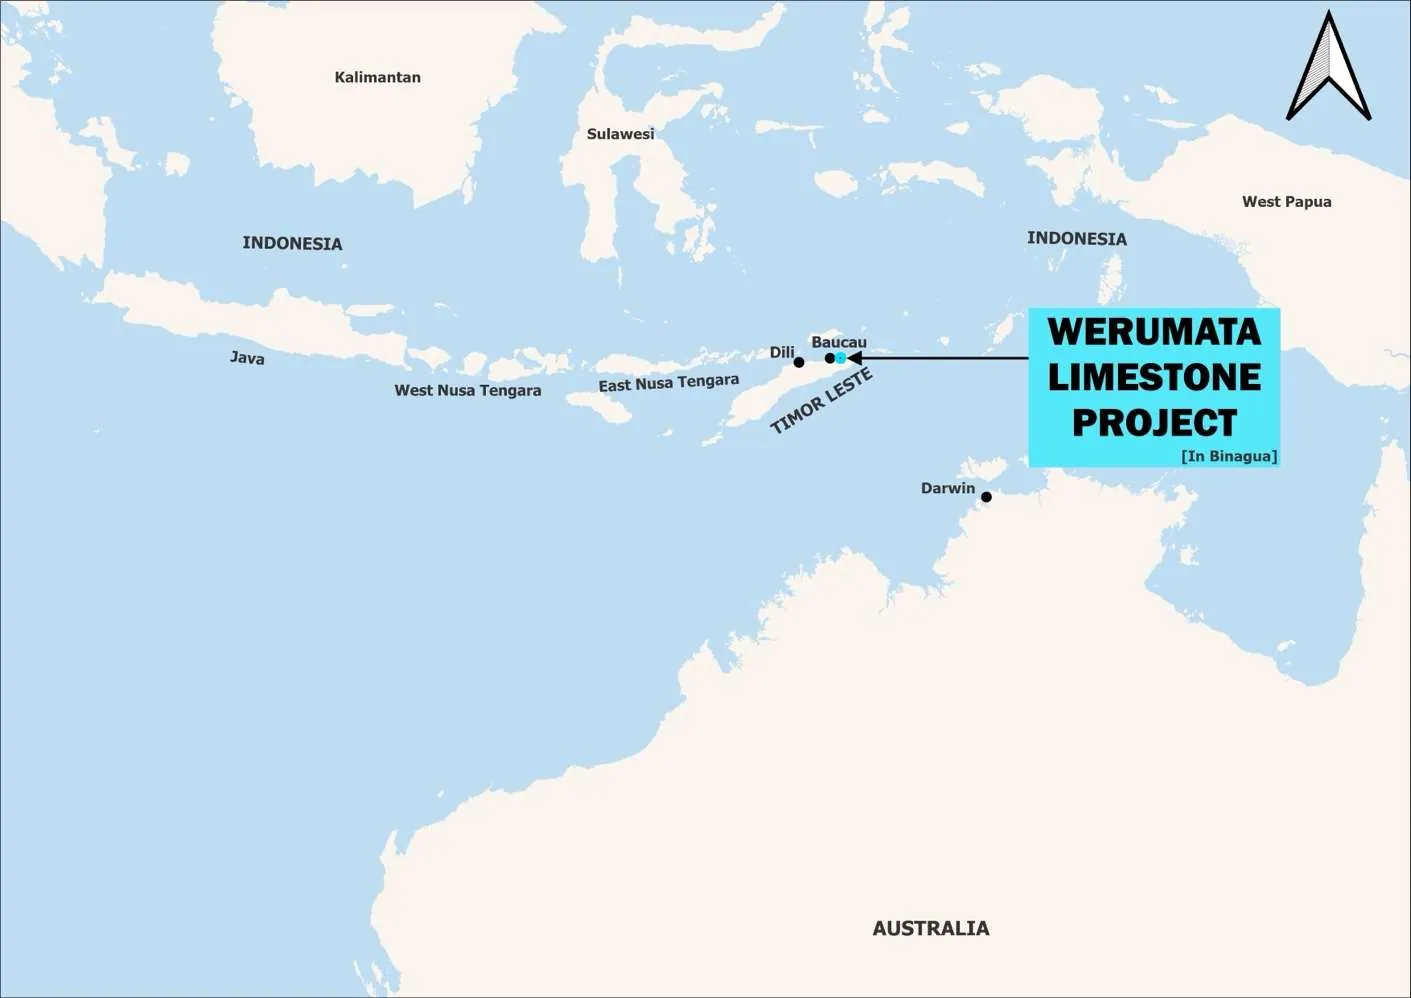
The proposed operation would begin with an approximately 8 Mtpa starter plant before expanding to 25 Mtpa through additional export berths. Stage 1 is estimated to require US$117 million of capital and is intended to reach first production and revenue in about Q3 2028, assuming a Final Investment Decision in the fourth quarter of 2027. Stage 3, which could lift capacity to 50 Mtpa or more, remains an option rather than part of the base-case economics.
Low operating costs meet a price-sensitive revenue model
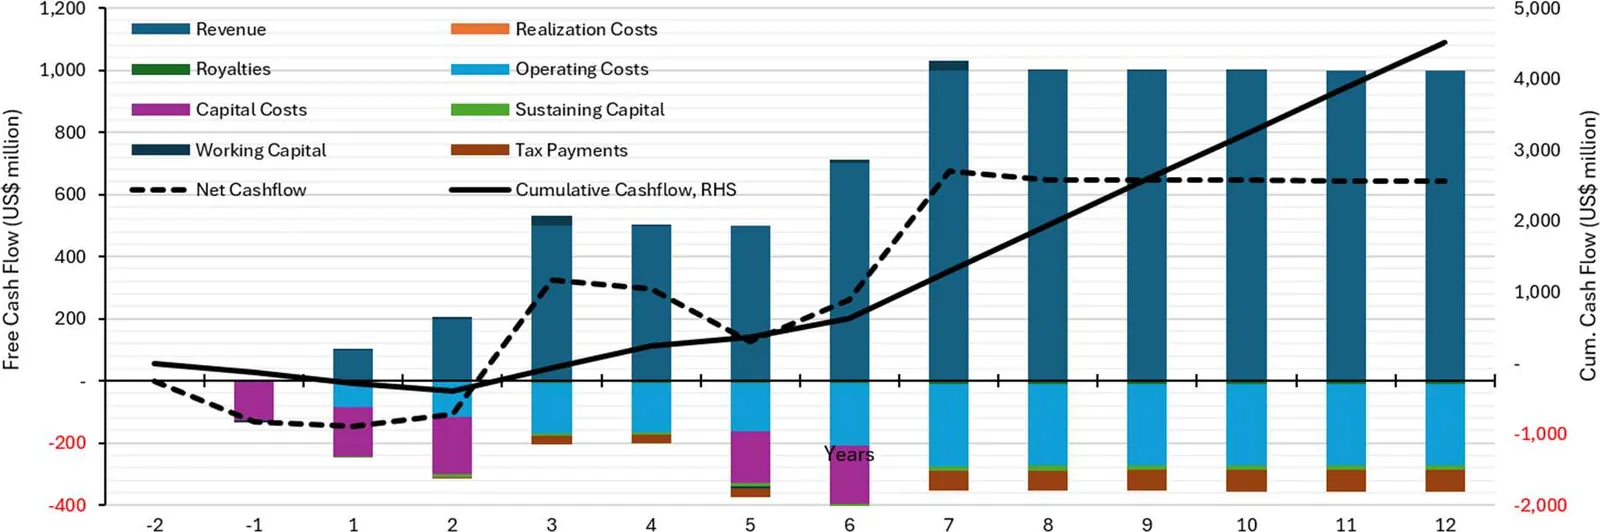
The study estimates life-of-mine operating costs of US$7.89 per tonne FOB against an assumed realised price of US$20/t. At full base-case production, typical annual revenue is forecast at US$500 million and EBITDA at US$306 million. Total Stage 1 and Stage 2 capital is estimated at US$476 million, while peak funding is lower at US$363 million because some Stage 2 spending is assumed to be funded from Stage 1 cash flow.
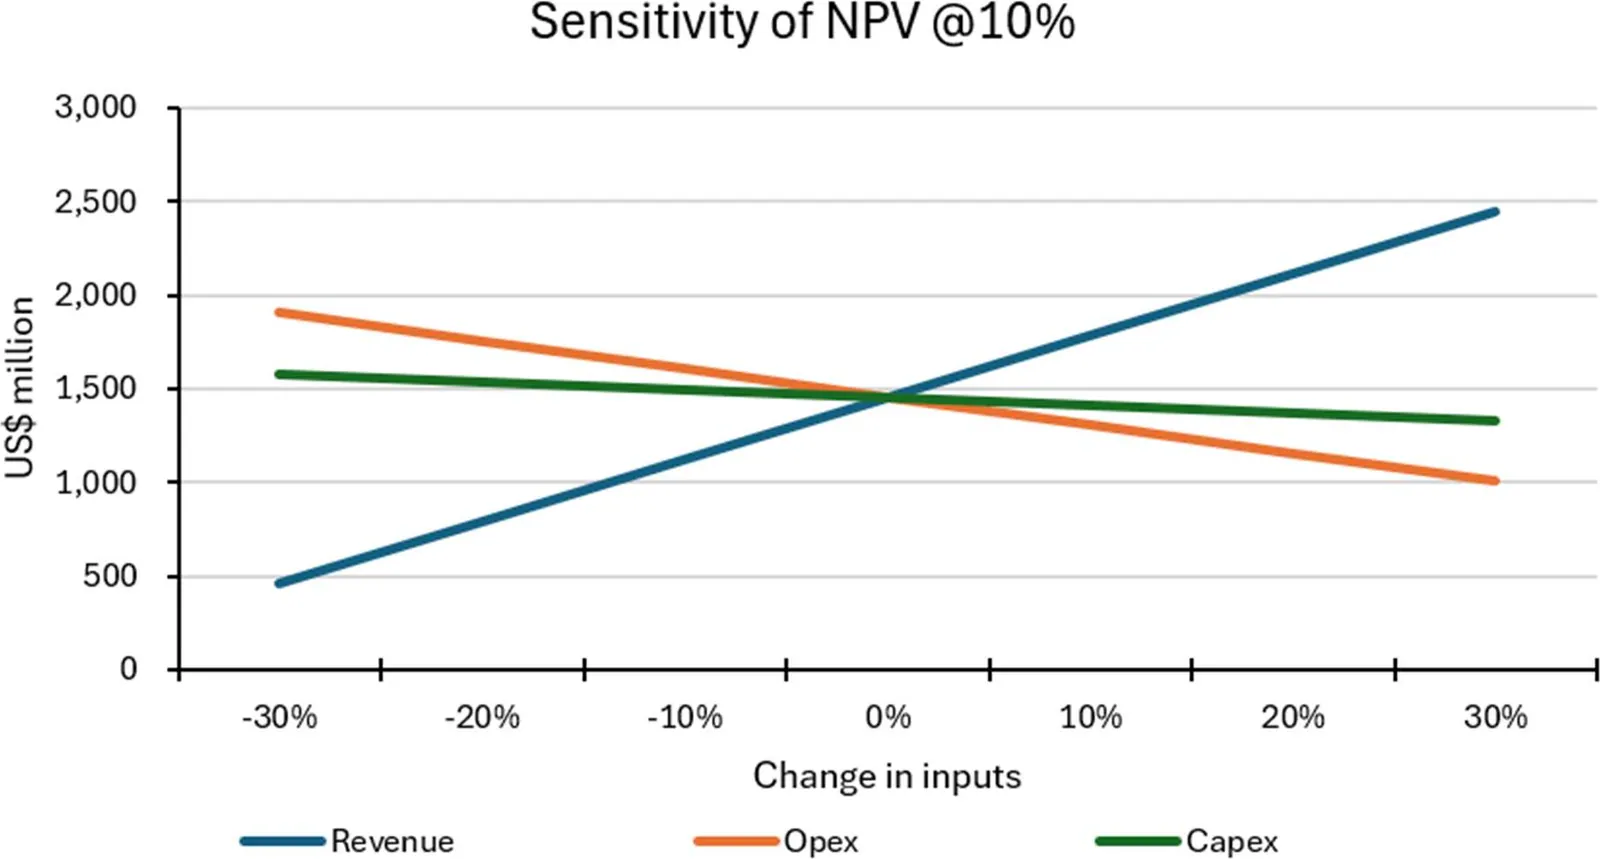
Price, rather than the headline resource size, is the central commercial variable. At US$15/t FOB, the base case falls to a US$622 million NPV10 and 26% IRR. The 8 Mtpa starter case remains above Estrella's stated 20% IRR threshold at that price, but only marginally, with an estimated 21% IRR and US$120 million NPV10. Those sensitivities make the eventual product mix, customer contracts and realised pricing more consequential than a simple comparison of tonnes in the ground.
Resource confidence has improved, but the mine schedule remains exposed
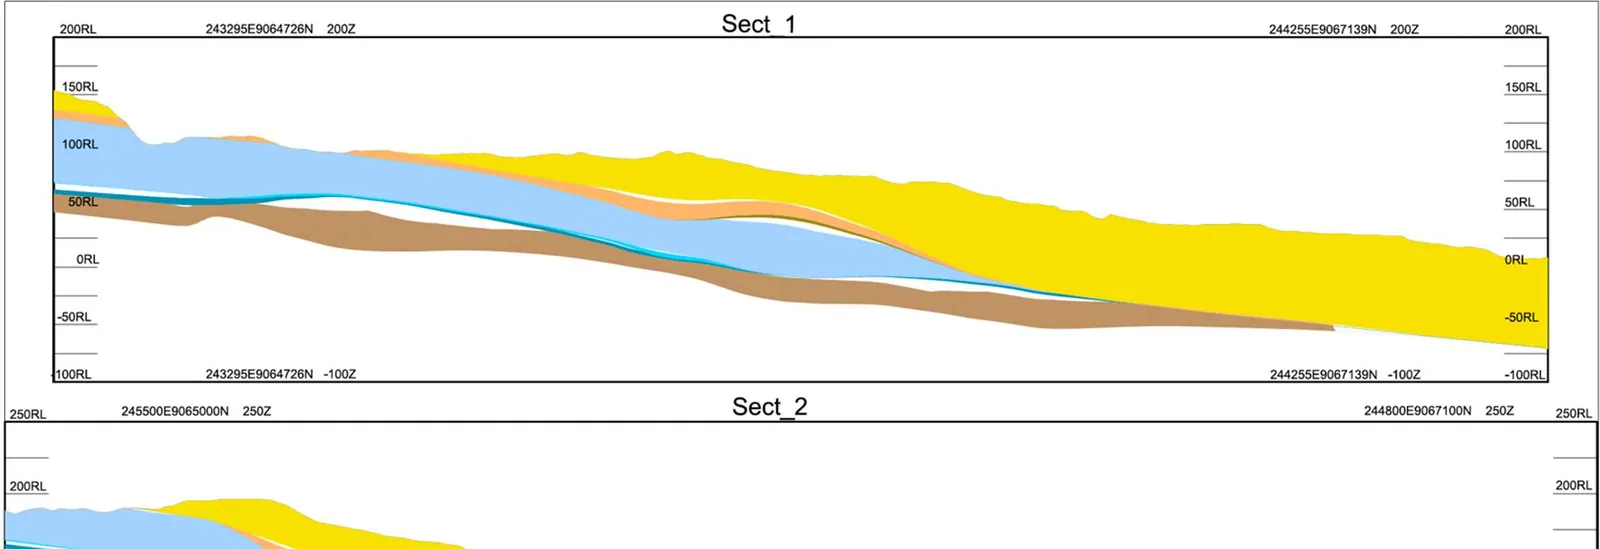
Werumata is supported by a 533 Mt JORC (2012) Mineral Resource, comprising 274 Mt Indicated and 259 Mt Inferred. The resource contains 391 Mt of higher-quality Product 1 limestone, with about 70% of that product classified as Indicated. The latest 274Mt Indicated resource upgrade increased confidence in the premium portion of the deposit, although the total resource includes no Measured material and no Ore Reserve has been declared.
The distinction matters because the mining schedule underpinning the study contains approximately equal amounts of Indicated and Inferred classified material. It is also expressed as 43 mining increments rather than calendar years, so it does not yet provide the level of annual production definition normally associated with a reserve-backed development decision. Infill drilling is planned to lift confidence in the early mining areas, alongside extension drilling and work on the separate Sagadati target, which is excluded from the reported resource and project economics.
Offtake framework is not yet a bankable sales book
Estrella's commercial plan is anchored by a Master Agreement with PT Raka Energi Mandiri for Indonesian customers, particularly the nickel-processing sector's acid-neutralisation market. The agreement's study conditions precedent have been satisfied, but it remains a framework: volumes, pricing and specifications must still be settled under separate sales contracts, and no binding, bankable offtake has been executed.
The company also says it expects non-binding memoranda of understanding covering approximately 8 Mt of product and is in preliminary discussions with other potential customers. That may help establish a route into the Indonesian market, but it does not yet substitute for contracted revenue. The study itself identifies realised price as the variable to which project economics are most sensitive.
Funding and Timor-Leste approvals set the real timetable
Estrella has not secured debt or equity funding for the project. The company estimates a further US$6.55 million, equivalent to A$9.36 million at the study's assumed exchange rate, is required for the next phase of work. That programme is intended to take Werumata from an AACE Class 5 conceptual study to a feasibility-level assessment and includes drilling, port geotechnical and oceanographic work, environmental studies, detailed engineering and offtake development.
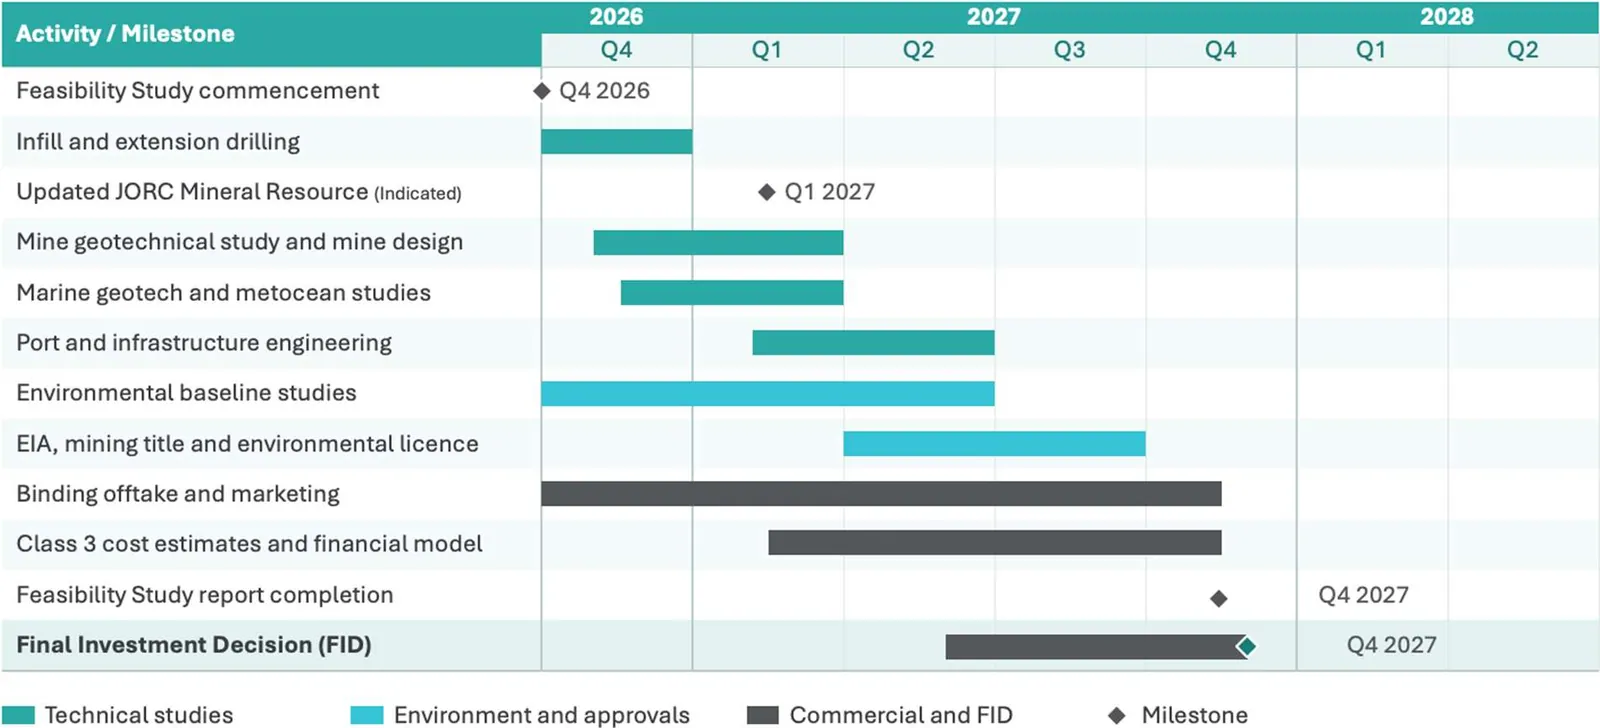
The cost estimate carries an expected accuracy range of roughly -20% to -50% on the low side and +30% to +100% on the high side. Port costs are a particular uncertainty: bathymetry and geotechnical data have not been validated, and the study notes that actual dredging costs could materially exceed the preliminary allowance. The project also requires a mining title, a Category A environmental assessment and licence, land access arrangements, maritime and port approvals, water and fuel approvals, and ultimately financing on terms that may affect existing shareholders.
Managing Director Robert Mencel said the study had put Estrella in a position to advance discussions with the Timor-Leste government and prospective offtakers, while targeting FID in Q4 2027. The next test is less glamorous than the NPV headline: whether drilling, customer contracts, approvals and port investigations can convert a promising conceptual model into a financeable project without allowing the capital and schedule assumptions to drift.
Get ASX:ESR news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Werumata now has a compelling preliminary economic case, but its value will be tested by binding offtake, project funding, port definition and the conversion of Inferred material into a reserve-backed mine plan.
Questions in the middle?
- Can Estrella secure binding Indonesian offtake at or near the US$20/t FOB assumption?
- How will port geotechnical work change the US$476 million capital estimate and the Q4 2027 FID target?
- Can the company fund the feasibility programme and eventual US$363 million peak requirement without material dilution?
Sources
1-
Werumata Limestone Project - Scoping Study (opens in a new tab)Verified company source. Estrella Resources Limited · 12 Nov 2026 · investorhub.estrellaresources.com.au