$223 million EBITDA and 14 cent dividend define GrainCorp’s FY26 result

GrainCorp has swung to a $10.1 million statutory loss after weak grain margins cut earnings, while the board begins searching for CEO Robert Spurway’s successor. The company expects export and crush margins to improve in FY27, but its transformation program remains unfinished and cash has fallen sharply.
- $10.1 million statutory loss and $30.5 million underlying NPAT
- Underlying EBITDA falls 28% to $223 million
- Final dividend holds at 14 cents, with no special dividend
- CEO Robert Spurway to remain during succession search
- FY27 export and crush margins expected to improve
 Add us as a preferred source on Google
Weak grain margins push GrainCorp into the red
GrainCorp Limited (ASX:GNC) has swung to a statutory loss as a global grain glut squeezed margins across its core East Coast Australian network. Net profit after tax fell from $39.9 million to a loss of $10.1 million for FY26, while underlying NPAT dropped 65% to $30.5 million and underlying EBITDA declined 28% to $223 million.
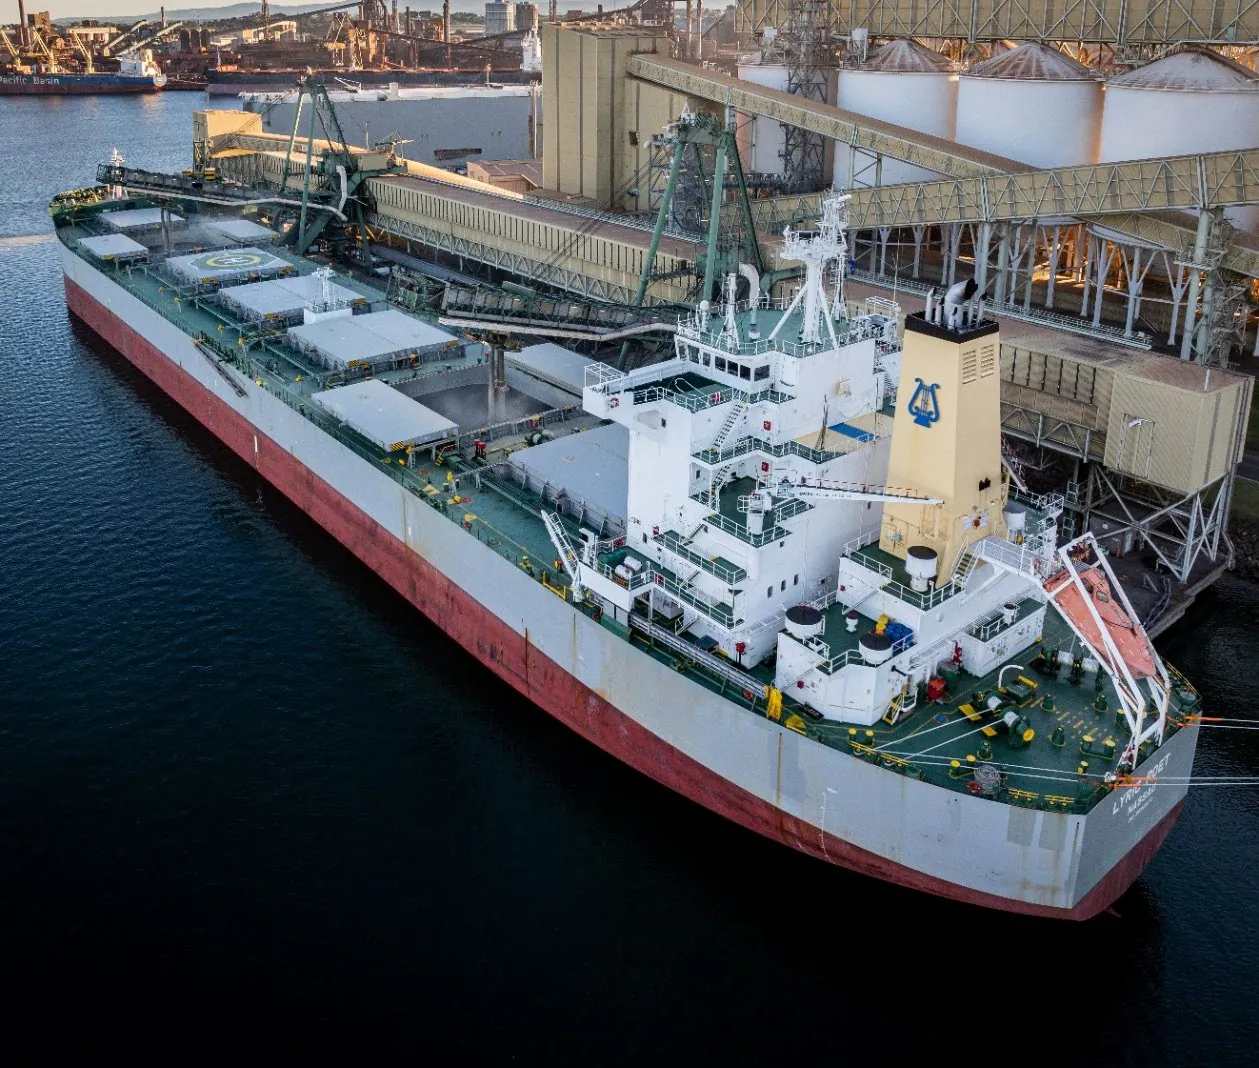
The result was broadly in line with the company’s revised expectations after the February earnings downgrade, which flagged persistent oversupply and weaker grain prices. Revenue eased only 2.4% to $7.13 billion, but the operational squeeze was more visible in volumes: total grain handled fell to 28.6 million tonnes from 31.6 million tonnes, receivals dropped to 12 million tonnes and exports declined to 5.9 million tonnes.
Animal Nutrition provides the brighter line
Agribusiness Underlying EBITDA fell to $156 million from $218 million, with low prices reducing growers’ incentive to sell and pushing East Coast end-to-end margins to multi-year lows. GrainCorp’s international business improved on the back of a record Western Australian crop and 4 million tonnes of contracted grain sales, but margins remained below through-the-cycle levels.
Nutrition and Energy also weakened, with EBITDA falling to $96 million from $117 million. Human Nutrition bore the pressure from lower bulk edible-oil demand and subdued crush margins. Animal Nutrition was the notable exception: sales volumes reached a record 751,000 tonnes, the fifth consecutive year of growth, supported by Australian beef prices and New Zealand dairy demand. Agri-energy recovered strongly in the second half, although full-year volumes still fell to 357,000 tonnes.
Dividend is maintained, but cash buffer narrows
The board declared a fully franked final dividend of 14 cents per share, taking FY26 ordinary dividends to 28 cents. That matches the ordinary dividend from FY25, but there is no special dividend this time after FY25 shareholders received an additional 20 cents per share.
GrainCorp ended the year with core cash of $171 million, down from $321 million, while net debt rose to $426 million from $102 million. The company says the increase partly reflected higher commodity inventory funding, and reported $785 million of committed undrawn facilities. Its $75 million on-market buy-back remains in place, with about $38 million completed by 30 September.
Transformation benefits arrive before the systems overhaul
The transformation program delivered $12 million in annualised early-stage benefits after the company simplified its Agribusiness operating model. Yet the major systems rollout has been pushed into the first half of calendar 2027, with remaining Release 1 spend estimated at $30 million to $35 million. The delay was also a feature of the transformation benefits update, which reported a postponed Nutrition and Energy rollout and deferred second release.
GrainCorp continues to target a $20 million to $30 million run-rate improvement in average earnings through the cycle by the end of FY28. That target now sits alongside a weaker earnings base, added implementation costs and a leadership transition that has no announced successor or completion timetable.
CEO succession adds a second test for FY27
The board and Robert Spurway have agreed to begin a search for the company’s next managing director and CEO. Spurway, who has led GrainCorp for more than six years, will remain in the role during the process. The company highlighted a 201% total shareholder return during his tenure, compared with 110% for the ASX 200 over the stated period, but the FY26 remuneration report records no executive short-term incentives and zero vesting for the FY24 long-term incentive grant.
Management’s immediate operating message is more constructive. ABARES forecasts a 26.6 million tonne East Coast winter crop for 2026-27, with stronger conditions in Victoria and southern New South Wales, while recent rainfall has improved the summer-crop outlook in northern regions. GrainCorp expects export and crush margins to improve from FY26 levels and plans to provide formal FY27 earnings guidance at its February 2027 annual general meeting. The unanswered question is whether better seasonal margins can arrive quickly enough to offset the cash demands of transformation and the uncertainty of a CEO search.
Get ASX:GNC news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
GrainCorp enters FY27 with a more supportive crop and margin setup, but the next CEO, transformation spend and cash conversion remain unresolved variables.
Questions in the middle?
- Can improved FY27 export and crush margins restore earnings before the transformation program reaches full deployment?
- Will the incoming CEO preserve GrainCorp’s diversification strategy or redirect capital towards the core grain network?
- How much of the remaining $30 million to $35 million systems spend will be absorbed before the targeted benefits appear?
Sources
4-
FY26 Appendix 4E and Annual Report (opens in a new tab)Verified company source. Graincorp Limited · 12 Nov 2026 · graincorp.com.au
-
FY26 Results Presentation (opens in a new tab)Verified company source. Graincorp Limited · 12 Nov 2026 · graincorp.com.au
-
GrainCorp announces FY26 results (opens in a new tab)Verified company source. Graincorp Limited · 12 Nov 2026 · graincorp.com.au
-
GrainCorp announces Managing Director & CEO Succession (opens in a new tab)Official market announcement. Graincorp Limited · 12 Nov 2026 · graincorp.com.au