Orica’s earnings mix shifts as digital and chemicals power another record year

Orica delivered its highest earnings in more than 15 years, lifting FY2026 EBIT 7% to A$1.06 billion and increasing its unfranked dividend 12% to 64 cents a share. Strong growth from Digital Solutions and Specialty Mining Chemicals helped offset currency pressure, litigation costs and a softer Indonesian coal market.
- Underlying NPAT up 9% to A$589.7 million
- Digital Solutions and Specialty Mining Chemicals EBIT each rise 25%
- Full-year dividend increases to 64.0 cents per share
- A$325.5 million after-tax hit from significant items
- FY2027 includes A$130 million hydrogen hub construction spend
 Add us as a preferred source on Google
Underlying earnings reach a 15-year high
Orica Limited (ASX:ORI) has put another record earnings year on the board, with EBIT rising 7% to A$1,056.9 million for the year ended 30 September 2026. Underlying net profit after tax increased 9% to A$589.7 million, while earnings per share before significant items rose 13% to 126.8 cents.
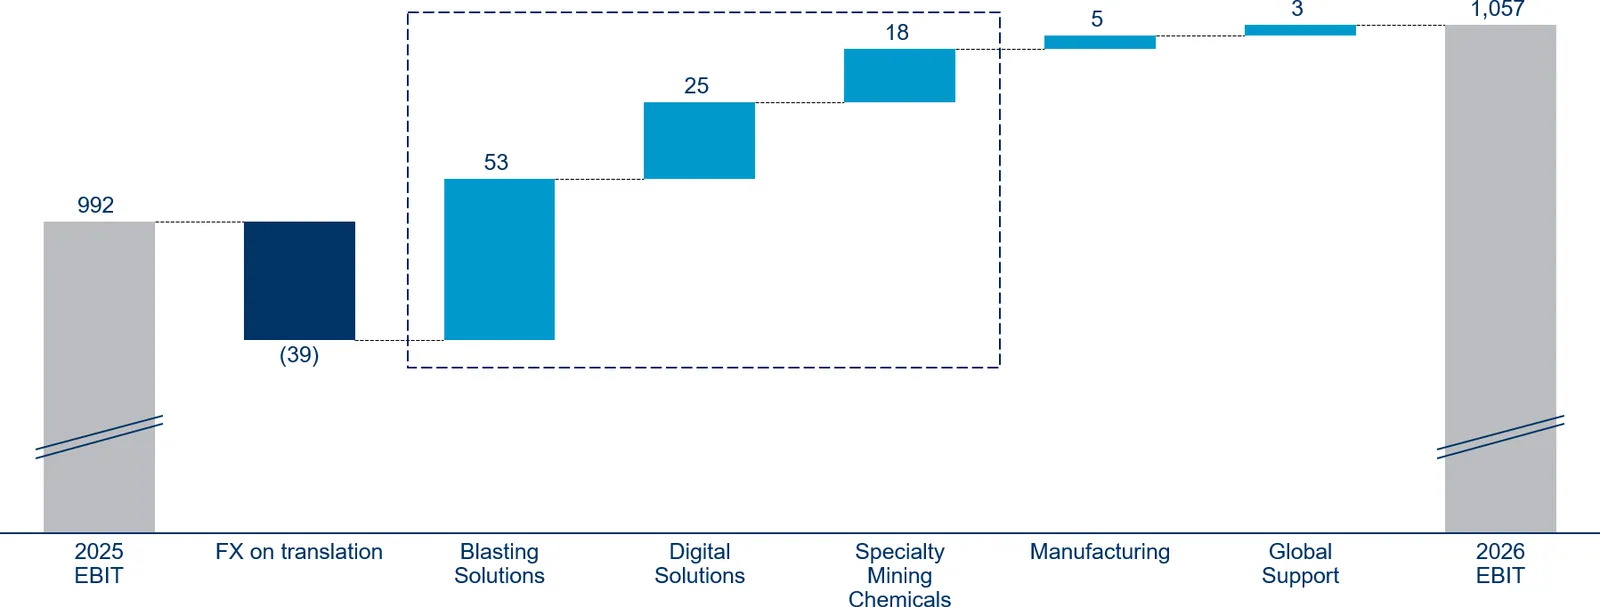
The result came despite a A$39 million translation headwind from a stronger Australian dollar, lower Indonesian coal production and supply disruptions at third-party facilities. Orica said its organisation-wide efficiency program, targeting at least A$100 million in annualised savings by the end of 2027, remains on track after the A$100 million cost program was launched earlier in the year.
Digital and specialty chemicals gain ground
The composition of earnings is changing, even if the headline revenue growth remains modest. Group revenue rose just 1% to A$8.26 billion, but Digital Solutions EBIT jumped 25% to A$115 million and Specialty Mining Chemicals EBIT also climbed 25% to A$126.3 million. Together, the two businesses now contribute nearly 23% of Orica’s earnings.
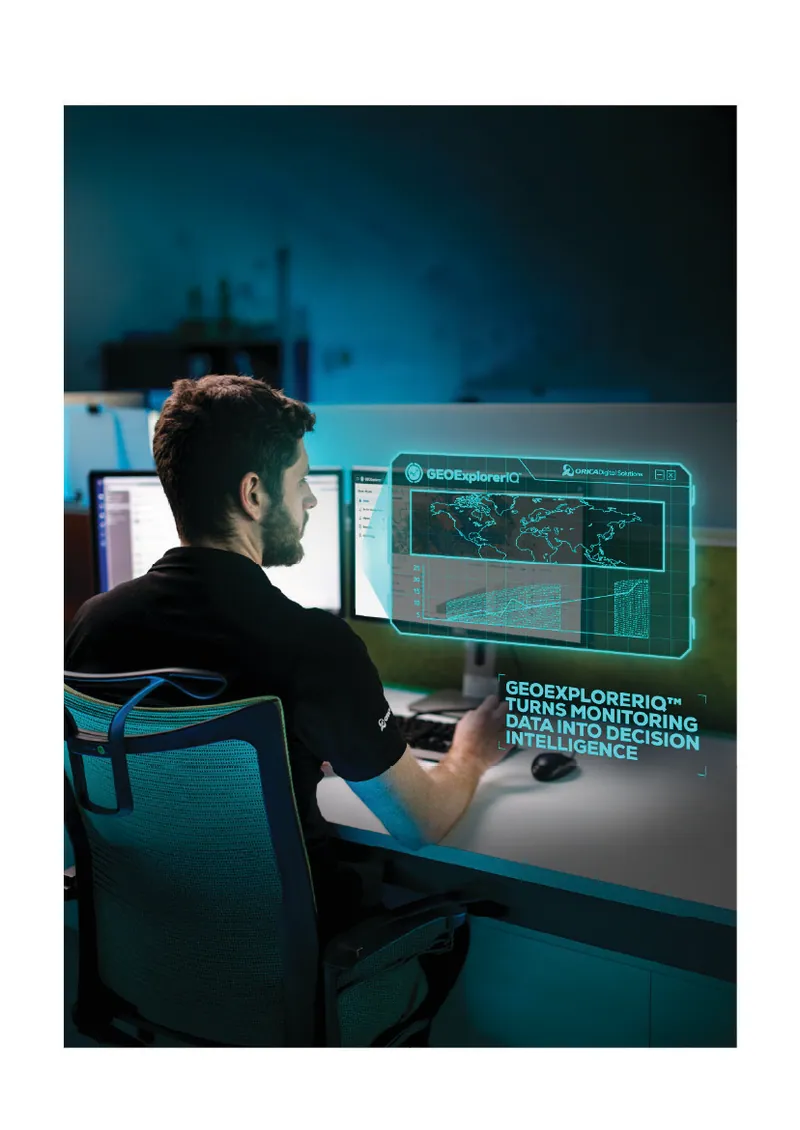
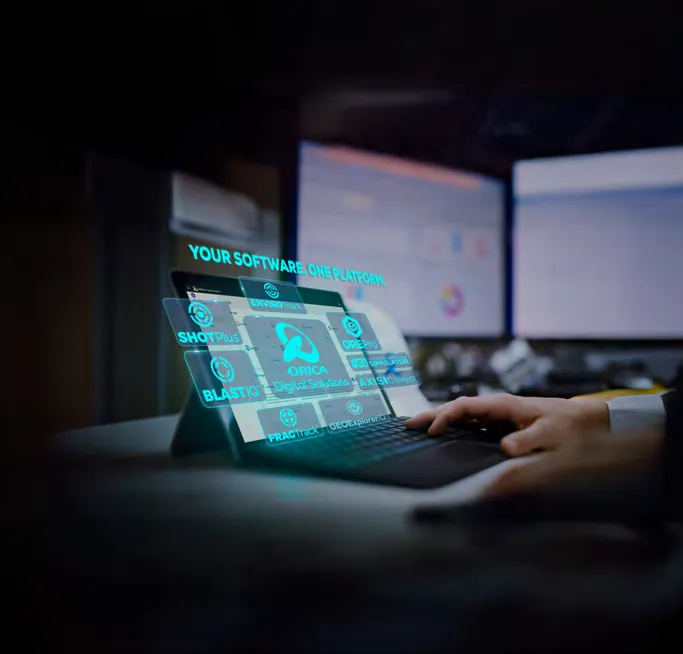
Digital Solutions revenue rose 12%, recurring revenue at year-end increased 14% and customer churn fell from 5.8% to 3.7%. Its EBIT margin expanded from 25.8% to 28.7%. Specialty Mining Chemicals benefited from a 9% increase in sodium cyanide volumes, record production and favourable gold-market conditions. Orica’s core Blasting Solutions business remained the largest contributor, with EBIT up 2% to A$880.9 million.
North American expansion brings scale and cost
North America was the strongest regional performer, with EBIT up 20% to A$254 million. Orica completed its acquisition of the remaining interest in Nelson Brothers’ US explosives business during the second half, taking ownership to 100% and consolidating the business into its results. The transaction expands Orica’s exposure to US quarry and construction markets and adds manufacturing and distribution capability.
The deal follows the Nelson Brothers acquisition, which was announced alongside the resolution of Orica’s CF Industries litigation earlier this year. Danafloat also expanded the Specialty Mining Chemicals portfolio into copper-processing chemistry. Management said both acquisitions are being integrated, but the results include a A$17.7 million pre-tax gain on the Nelson Brothers transaction rather than treating the deal as a clean recurring earnings contribution.
Statutory profit still carries a heavy charge
Statutory NPAT rose 63% to A$264.2 million, a sizeable improvement that nevertheless sits well below the underlying result. Orica booked A$325.5 million of significant items after tax attributable to shareholders, including A$257.1 million of litigation costs and outcomes, A$35.8 million of US supply disruption costs and A$49.3 million of restructuring costs, partly offset by the Nelson Brothers gain.
Net operating cash flow fell to A$758.3 million from A$949.2 million, largely because significant items consumed A$344.2 million of cash and the stronger Australian dollar weighed on reported figures. Net debt excluding leases rose to A$2.15 billion, while leverage increased to 1.46 times, still at the lower end of Orica’s 1.25 to 2.00 times target range. Net finance costs rose 7% to A$214.4 million.
Dividend rises as hydrogen project moves into construction
The board declared an unfranked final dividend of 35.5 cents a share, taking the full-year payout to 64.0 cents, up 12% and equal to a 50% payout ratio on underlying profit. Orica also completed its A$500 million on-market share buy-back, returning capital while funding acquisitions and manufacturing investments.
The Hunter Valley Hydrogen Hub is the larger capital allocation question. Orica reached final investment decision in June and expects to spend about A$130 million on construction in FY2027, net of government grants, alongside ordinary capital expenditure of A$470 million to A$500 million. The 50MW project is expected to support renewable hydrogen production for Kooragang Island’s ammonia operations, but its financial contribution is not expected to arrive immediately.
FY2027 outlook includes turnarounds and higher financing costs
Orica expects continued earnings growth in FY2027 from premium blasting products, Digital Solutions, specialty chemicals and cost savings. That outlook is tempered by planned turnarounds at Kooragang Island, Yarwun and Winnemucca, lower Indonesian thermal coal demand and net finance costs expected to be A$25 million to A$35 million higher than in FY2026.
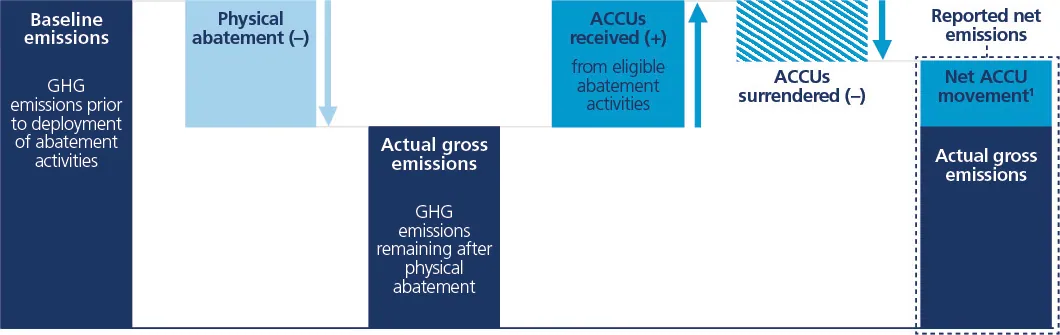
The company also reported a 52% reduction in gross Scope 1 and Scope 2 emissions from its 2019 baseline, while net emissions were down 35% after the effect of Australian Carbon Credit Units. A fatality at a North American customer site remains the most serious blemish in an otherwise strong operating year. The immediate test is whether Orica can convert portfolio diversification, acquired assets and promised cost savings into cash returns while its capital demands rise.
Get ASX:ORI news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Orica enters FY2027 with stronger growth businesses and a fuller acquisition portfolio, but execution across plant turnarounds, hydrogen construction, cost savings and debt-funded investment will determine how much of that promise reaches shareholders.
Questions in the middle?
- Can the Digital Solutions and Specialty Mining Chemicals businesses sustain their mid-teen and high-single-digit growth ambitions as the portfolio expands?
- How quickly will the Nelson Brothers and Danafloat acquisitions add recurring earnings after integration and financing costs?
- Will the Hunter Valley Hydrogen Hub remain within its planned capital envelope as construction begins and Kooragang Island undergoes a major turnaround?
Sources
4-
Orica Full Year Results Compendium 2026 (opens in a new tab)Verified source. Orica Limited · 12 Nov 2026
-
Orica Full Year Results Investor Presentation 2026 (opens in a new tab)Verified source. Orica Limited · 12 Nov 2026
-
Orica Full Year Results 2026 (opens in a new tab)Verified source. Orica Limited · 12 Nov 2026
-
Orica Annual Report 2026 (including Appendix 4E) (opens in a new tab)Verified source. Orica Limited · 12 Nov 2026