Paladin puts A$525 million behind its next uranium growth phase

Paladin Energy has launched a fully underwritten A$525 million equity raising to accelerate its Patterson Lake South uranium project, expand Triple R and repay debt. The placement comes at a 10.3% discount to the last traded price, with retail investors offered a separate, non-underwritten share purchase plan.
- A$474 million ASX institutional placement at A$7.80 a share
- C$50 million TSX bought deal priced at C$7.62 a share
- A$367 million earmarked for PLS development in CY2027 and CY2028
- Further funding for Triple R, Atlas, Saloon East and regional exploration
- Up to A$50 million additional non-underwritten SPP for eligible shareholders
 Add us as a preferred source on Google
A$525 million raise targets PLS construction runway
Paladin Energy Ltd (ASX:PDN, TSX:PDN) is asking institutional investors to fund the next stage of its Canadian uranium ambitions, launching a A$525 million fully underwritten equity raising at A$7.80 a share. The offer price is 10.3% below Paladin’s A$8.70 closing price on 11 November, while the company’s shares were placed into trading halts.
The raising comprises a A$474 million ASX institutional placement and a C$50 million Canadian bought deal, equivalent to about A$51 million. Together, the transactions are expected to issue approximately 67.3 million new shares against 449.4 million shares on issue at 30 September, implying dilution of roughly 15% before any participation in the separate share purchase plan.
PLS receives the bulk of the new capital
Paladin has allocated A$367 million of the institutional and Canadian raising to Patterson Lake South development work during calendar 2027 and 2028. That money is intended to support detailed engineering, procurement, contractor mobilisation, site infrastructure, long-lead processing equipment and underground mine development.
The objective is to protect the project’s development path ahead of the main construction program and maintain the company’s targeted first production date in calendar 2031. Paladin said the raise strengthens its ability to optimise the remaining PLS funding package, but the project is not fully funded by this equity transaction alone. The company’s presentation refers to ongoing discussions with banks, potential offtakers and strategic partners, including conditional, non-binding indicative debt terms.
Exploration spending broadens the PLS proposition
Paladin is also directing A$44 million towards potential resource growth and a mine-life extension at the Triple R deposit, including confidence and extension drilling. A further A$58 million is earmarked for Athabasca Basin exploration, including follow-up work at Atlas and Saloon East and testing of regional targets.
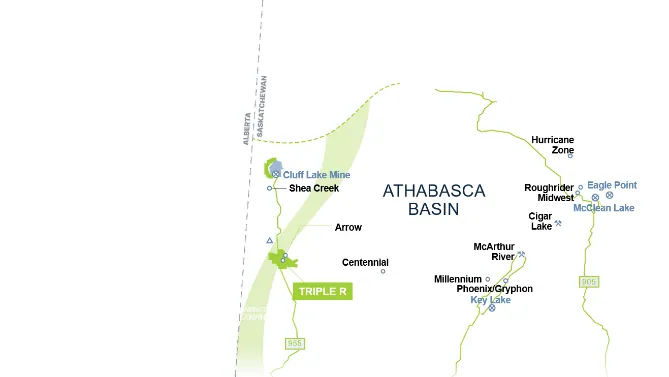
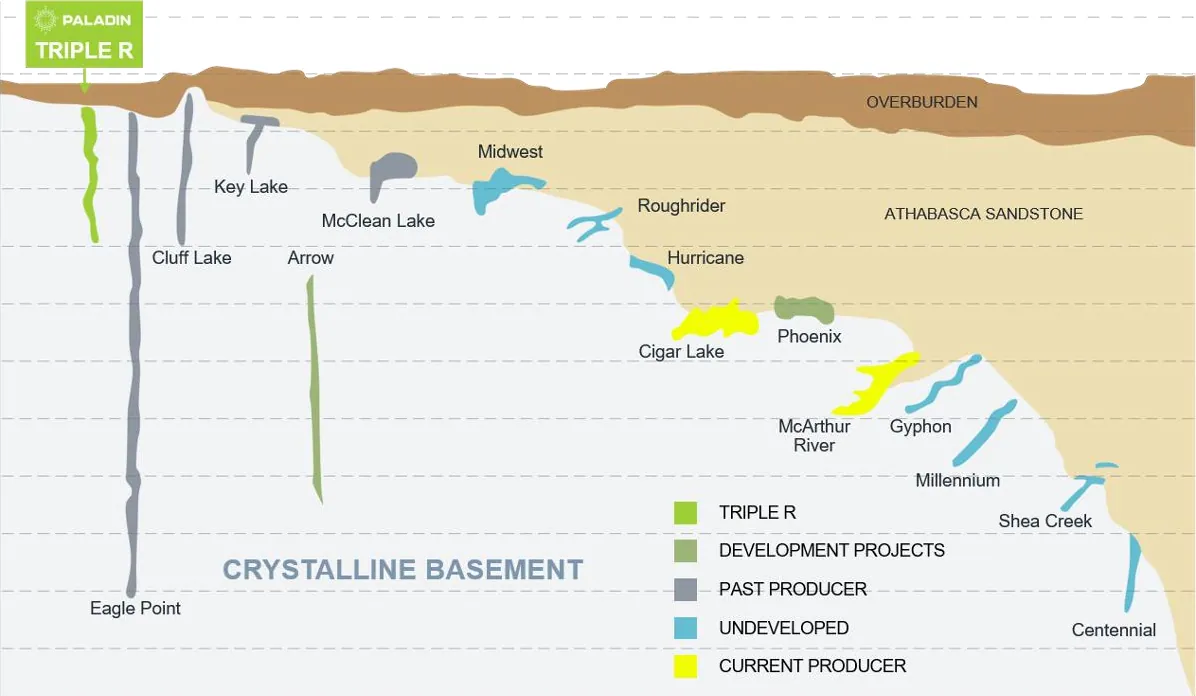
That exploration push builds on the recent Atlas drilling results, which identified a new high-grade uranium zone south of Triple R. The latest presentation describes Atlas and Saloon East as opportunities to convert discoveries into future development targets, while stressing that resource growth and mine-life extension remain potential outcomes rather than established reserves.
Debt repayment improves flexibility but does not remove execution risk
About A$41 million of the funds is assigned to balance sheet flexibility, including repayment of an existing term loan. On Paladin’s pro forma figures, the A$525 million raising would lift cash and cash equivalents from US$209 million to US$570 million before the SPP, while the drawn debt facility is shown at US$28 million before the term-loan repayment described in the use-of-funds schedule.
Eligible shareholders in Australia and New Zealand will be invited to apply for up to A$30,000 of new shares at A$7.80 through a non-underwritten SPP targeting up to A$50 million. The SPP may be scaled back, increased or closed early, so its proceeds should not be treated as guaranteed funding.
Funding arrives alongside permitting and market risks
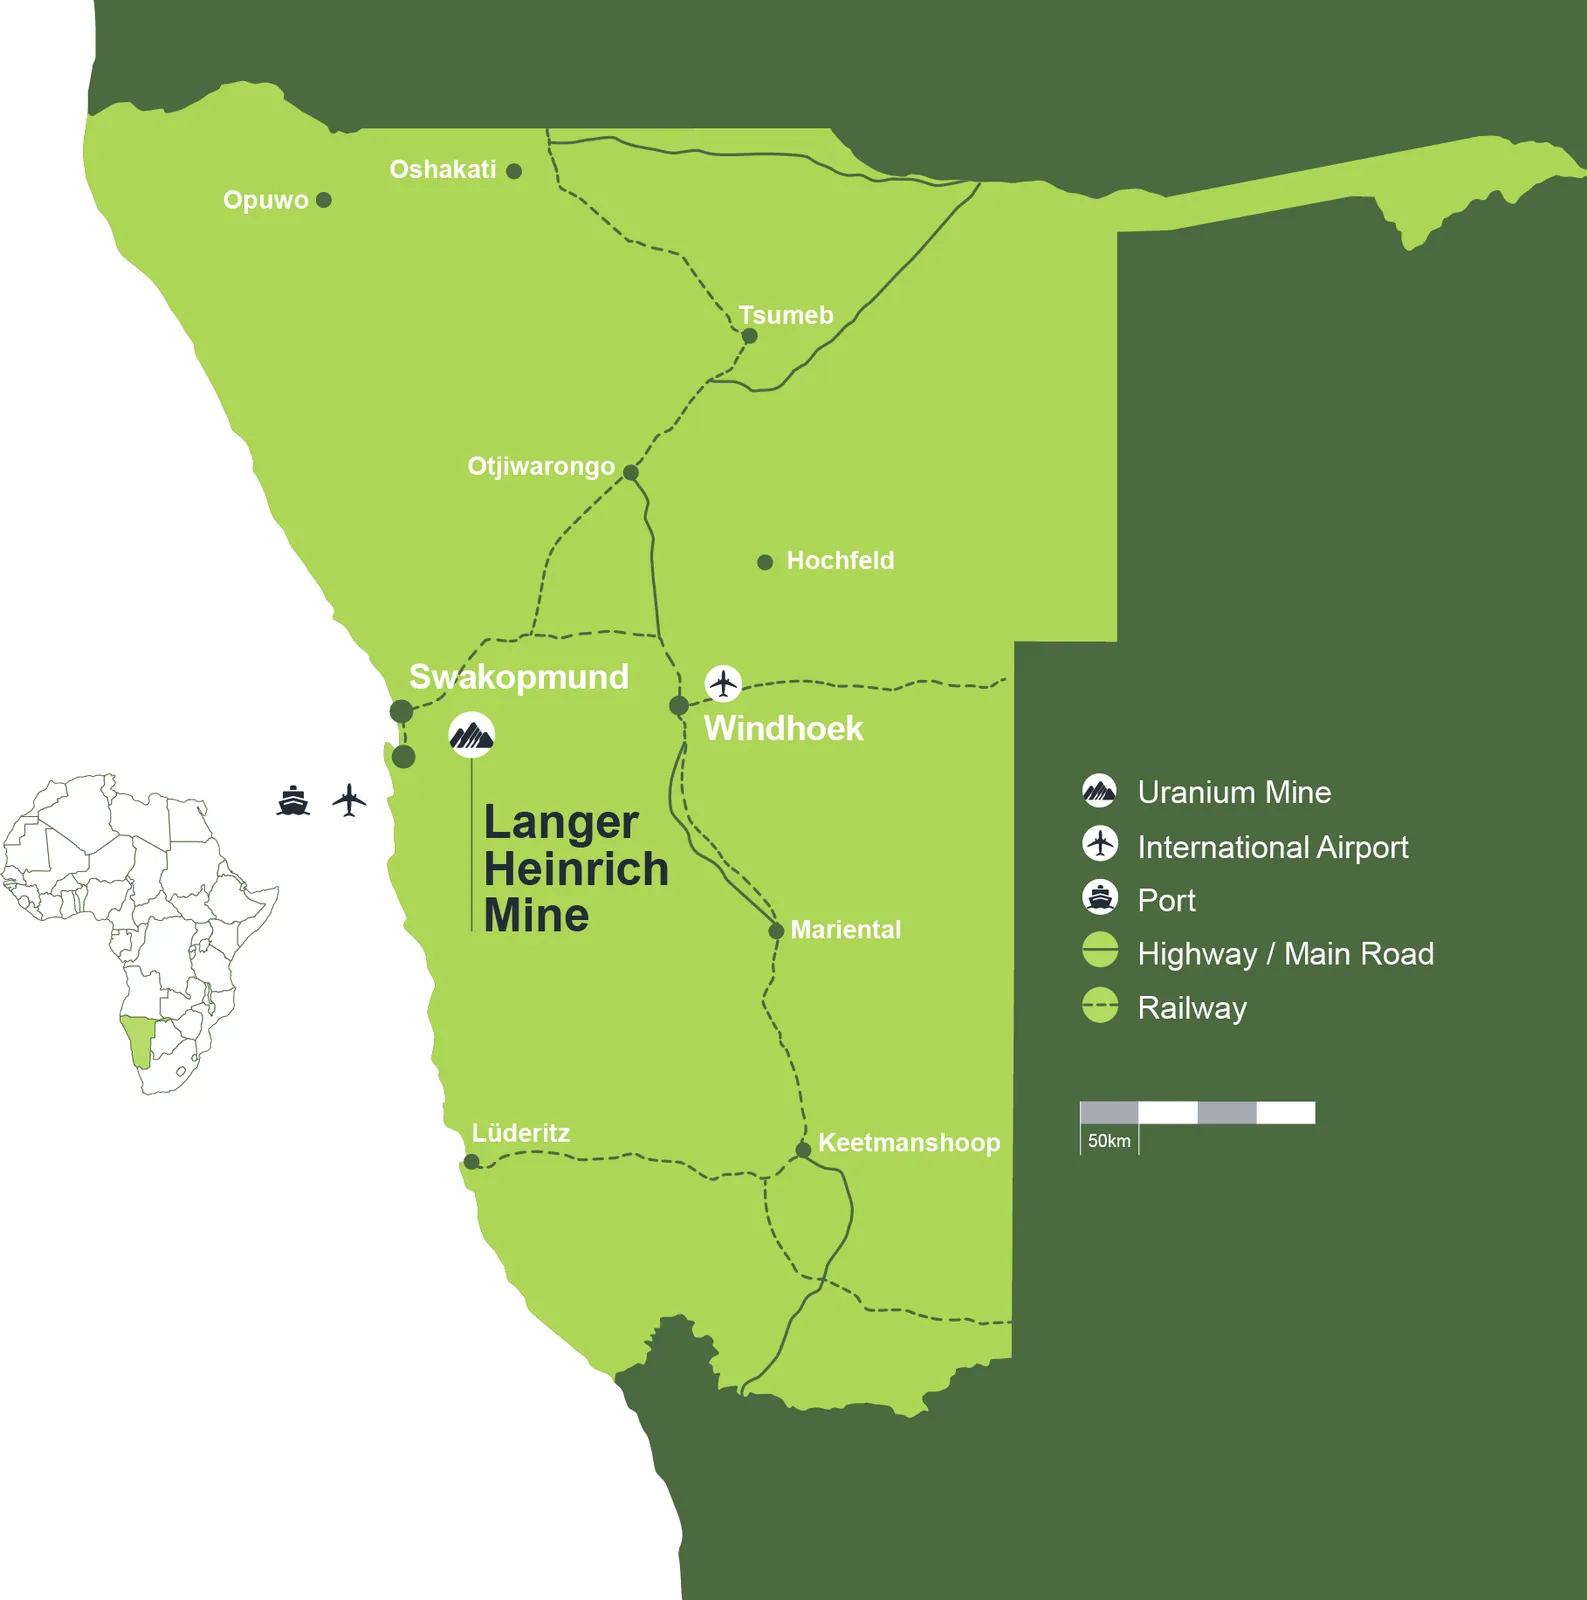
Paladin’s case rests on moving PLS from an advanced development project into construction while continuing to benefit from production at the Langer Heinrich Mine in Namibia. The company maintained its FY2027 Langer Heinrich guidance of 5.1 million to 5.65 million pounds of U3O8, despite deferring a planned kiln shutdown to the second half of the financial year.
The funding does not eliminate the risks identified in the presentation. PLS remains subject to further regulatory approvals, seasonal construction constraints, financing requirements and project execution. Paladin also disclosed that Métis Nation-Saskatchewan has sought judicial review of the provincial environmental approval, while a separate class action concerning historical production guidance remains unresolved. The next hard test is whether the capital can be converted into procurement, site readiness and permitting progress without pushing the 2031 production target further out.
Get ASX:PDN news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The raise gives Paladin a substantially larger runway for PLS, but shareholders now face both immediate dilution and the longer test of whether early works translate into an adequately funded, permitted mine.
Questions in the middle?
- Will the remaining PLS funding package be secured on terms that preserve the project’s economics?
- Can Paladin complete the planned CY2027 and CY2028 work without regulatory or winter-weather delays?
- How much additional resource and mine life will the Triple R, Atlas and Saloon East programs ultimately establish?
Sources
2-
A$525M Fully Underwritten Equity Raising - Presentation (opens in a new tab)Verified source. Paladin Energy Ltd · 12 Nov 2026 · paladinenergy.com
-
A$525M Fully Underwritten Equity Raising (opens in a new tab)Verified source. Paladin Energy Ltd · 12 Nov 2026 · paladinenergy.com