DUG’s software shift lifts revenue and margins in a strong FY27 start

DUG Technology has delivered a sharp start to FY27, with revenue up 49% and contracted revenue reaching US$103.4 million. The shift is increasingly visible in the mix: Multi-Client, Software and HPC now account for 55% of revenue, although Services remains under pressure and recent contract awards are yet to convert fully into cash.
- Revenue rose 49% to US$34.4 million in the first four months of FY27
- Normalised EBITDA increased 86% to US$11.3 million, with margin reaching 33%
- Contracted revenue climbed 52% to US$103.4 million
- Multi-Client, Software and HPC contributed 55% of revenue, versus 14% a year earlier
- Services revenue fell 22%, while Services contracted revenue increased to US$35.8 million
 Add us as a preferred source on Google
Software and HPC drive DUG’s FY27 acceleration
DUG Technology Ltd (ASX:DUG) has started FY27 with a marked change in its revenue engine. Total revenue rose 49% to US$34.4 million in the four months to 31 October, while normalised EBITDA increased 86% to US$11.3 million. The company’s normalised EBITDA margin reached 33%, up from 26.3% a year earlier, although the measure excludes US$2.5 million of third-party cloud computing costs.
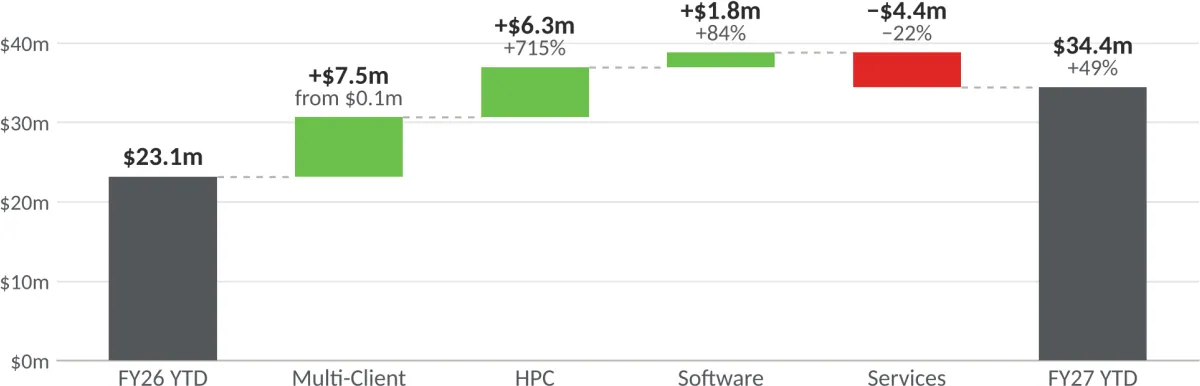
The strongest growth came from the lines DUG is deliberately trying to expand. Multi-Client revenue reached US$7.6 million, compared with US$0.1 million in the same period last year, while Software revenue rose 84% to US$4.0 million and HPC revenue surged 715% to US$7.2 million. Together, Multi-Client, Software and HPC generated 55% of total revenue, up from 14% in FY26 YTD.
US$43 million of new Software and HPC contracts
Contracted revenue stood at US$103.4 million on 12 November, 52% above the US$68.0 million recorded at 30 June. Software and HPC accounted for US$67.6 million of that total, after US$43.0 million in new committed contracts since year-end, including the US$33.7m HPC award announced on 9 November, which covered four years of hosted high-performance computing infrastructure and software.
DUG says it now has 12 Multi-Client projects at varying stages of completion as it builds out the library. The model is still developing, but the early contribution to reported revenue is significant. Contracted revenue is a forward-looking measure of work yet to be recognised across Services, Software and HPC, rather than revenue already collected.
Services revenue falls as customers shift to DUG’s platform
Services revenue declined 22% to US$15.6 million. DUG says some clients that previously bought processing services are instead licensing its software and HPC capacity and running the work themselves, while other processing companies use the same tools to compete for Services projects. In both cases, the company says revenue is moving into Software and HPC rather than disappearing from its offering altogether.
Services contracted revenue nevertheless rose from US$33.6 million at 30 June to US$35.8 million at 12 November. Management expects Services revenue to recover over the rest of FY27, but that expectation will need to be tested by the conversion of the pipeline into active projects and recognised revenue.
Cash investment rises while net debt stays broadly flat
DUG ended the period with US$17.7 million in cash and US$30.4 million of debt, leaving net debt at US$12.7 million compared with US$13.0 million at 30 June. It purchased US$7.0 million of new compute equipment during FY27 YTD using cash. The increase in gross debt also reflects financing arranged after year-end for equipment delivered in the final week of June.
The figures are unaudited, and DUG has not yet received payment under the US$33.7 million award announced on 9 November. The next test is therefore not simply whether contracted revenue continues to grow, but how quickly those commitments become recognised revenue and cash while the company funds further compute investment and reviews its debt profile.
Get ASX:DUG news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
DUG’s growth mix is improving on paper, but execution now turns on converting the US$103.4 million contracted revenue balance into revenue and cash without putting further pressure on debt.
Questions in the middle?
- How quickly will the US$43.0 million of new Software and HPC contracts flow into recognised revenue and operating cash flow?
- Can Services revenue recover as the existing pipeline converts, or will more customers continue shifting work toward Software and HPC capacity?
- What debt-profile changes will DUG make as it continues investing in compute equipment?
Sources
1-
Trading Update-Revenue up 49% and Contracted Revenue up 52% (opens in a new tab)Verified company source. DUG Technology Ltd · 16 Nov 2026 · dug.com