Catapult crosses A$200 million ACV as platform expansion lifts margins

Catapult Sports has pushed Annualized Contract Value beyond A$200 million while lifting Management EBITDA margin to 20% in the first half of FY27. The stronger operating result came alongside a wider statutory loss, reflecting acquisition-related and other non-cash charges.
- ACV rises 25% in constant currency to US$145.2 million
- Management EBITDA climbs 66% to US$16.1 million
- Multi-solution teams increase 51% to 1,567
- Free cash flow reaches US$9.3 million
- Statutory net loss widens to US$19.1 million after acquisition charges
 Add us as a preferred source on Google
ACV passes A$200 million as margins expand
Catapult Sports Ltd (ASX:CAT) has crossed a symbolic threshold in its subscription business, with Annualized Contract Value reaching US$145.2 million, equivalent to A$208 million, at September 30. ACV rose 25% year on year in constant currency, or 18% excluding ACV acquired through Impect, while Management EBITDA increased US$6.4 million to US$16.1 million. That lifted the company’s operating margin to roughly 20%, from 14% a year earlier.
The result gives Catapult a Rule of 40 score of 38% excluding acquired ACV and 45% including it. The metric combines constant-currency ACV growth with Management EBITDA margin. It is a non-IFRS measure and has not been independently audited or reviewed, but the direction is clear: growth accelerated without the operating cost base rising at the same pace.
That progression extends the trajectory reported in the record FY26 revenue results, when Catapult posted US$140.7 million of full-year revenue and Management EBITDA rose 67%. In the latest half, revenue increased 20% in constant currency to US$81.7 million, while SaaS revenue grew 24% to US$69.4 million. Recurring revenue now accounts for 96% of the total.
Cross-selling becomes the second growth engine
Catapult added more than 230 professional teams during the half, taking the customer base to 4,410, up 14% year on year. Average ACV per professional team rose 10% in constant currency to US$31,300, while ACV retention improved to 95.5%, above the company’s 95% target and marking an eleventh consecutive half-year above that level.
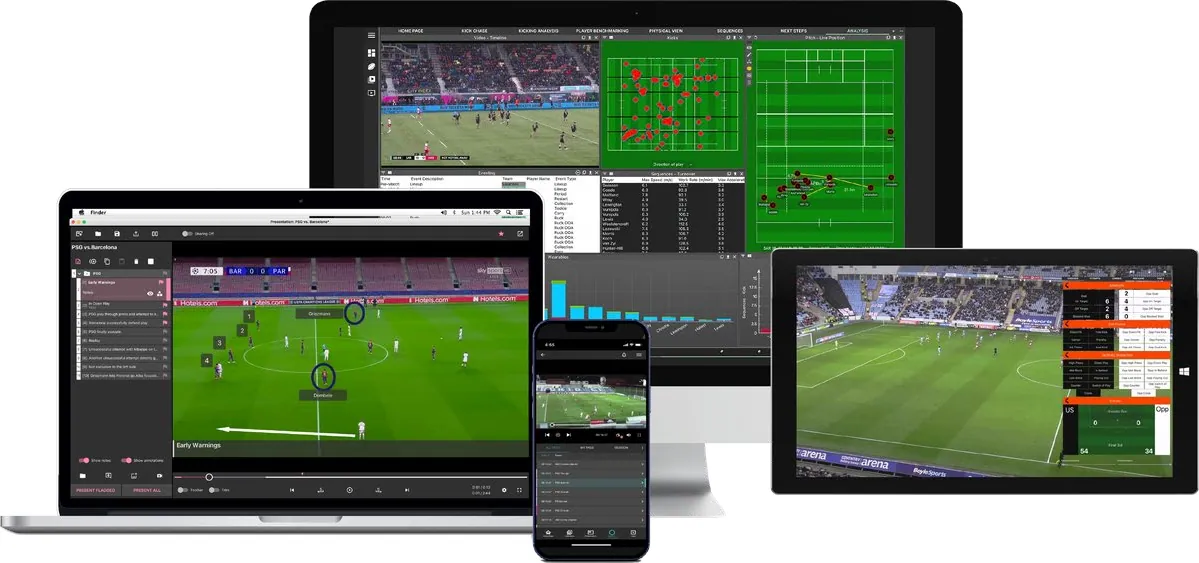
The more revealing number may be product breadth. Multi-solution professional teams increased by 531, or 51%, to 1,567, representing 36% of the base compared with 27% a year earlier. Performance & Health ACV grew 15% to US$90.2 million, while Tactics & Coaching ACV jumped 47% to US$52.1 million, including the contribution from Impect. Excluding acquired ACV, Tactics & Coaching growth accelerated to 23% from 16% in the first half of FY26, the period covered in the 1H FY26 SaaS growth.
Cash generation improves despite a statutory loss
Gross margin reached 80.7%, above Catapult’s 80% target for a first half for the first time, while contribution margin rose to 52.9% from 51.4%. Free cash flow excluding transaction costs came in at US$9.3 million, up from US$8.2 million, taking cash to US$62 million. The company also has an undrawn US$50 million debt facility.
Statutory earnings tell a less flattering story. Catapult reported a net loss of US$19.1 million, compared with US$8.6 million in the prior corresponding half. The company attributed the result to US$13.5 million of acquisition-related charges, primarily deferred Impect purchase consideration that vests with service, US$5.2 million of amortisation on acquired intangibles and US$0.9 million of foreign exchange and other one-off items. Underlying NPAT improved to a loss of US$1.1 million from US$4.1 million, while EBITDA excluding acquisition-related charges rose 56% to US$17.1 million.
Impect launch tests the platform strategy
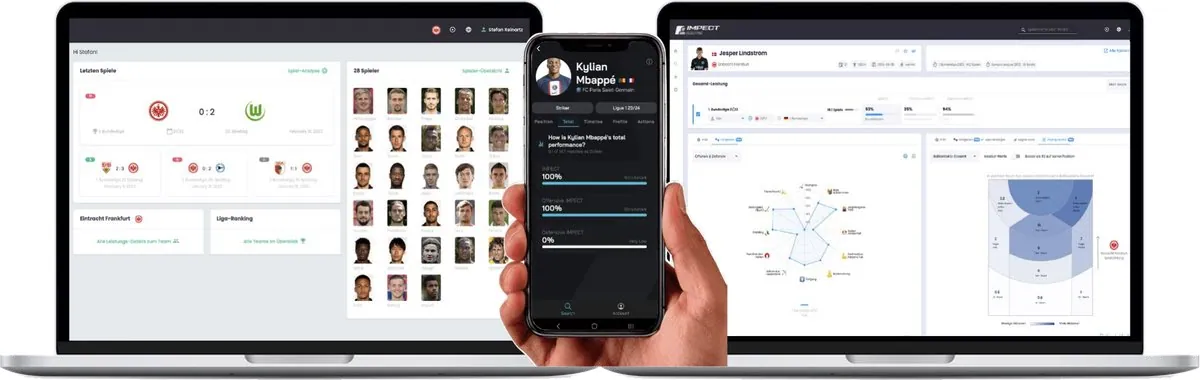
Catapult says more than 50 teams have signed up for a bundled scouting and professional video package since the early launch of Impect Video Scouting. The product combines video from more than 150 competitions with performance data, giving the company another route to sell multiple tools into soccer clubs. Other product work during the half included expanded Perch gym monitoring, upgrades to Vector 8 and Hub Pro, AI-powered RaceWatch analysis and new Focus Live presentation features.
Management expects strong ACV growth with low churn, further improvement in cost margins and higher free cash flow excluding transaction costs during FY27. Those are objectives rather than guarantees. The next test is whether organic ACV growth can hold at its current pace while the new scouting product converts early interest into recurring revenue, and whether the statutory drag from acquisitions continues to recede.
Get ASX:CAT news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Catapult has demonstrated stronger operating leverage, but the investment case still depends on organic growth sustaining momentum as acquisition charges work through the accounts.
Questions in the middle?
- Can the 18% constant-currency ACV growth excluding Impect remain durable through the second half?
- How quickly will Impect Video Scouting convert its early team sign-ups into material recurring revenue?
- Will acquisition-related charges decline enough for statutory earnings to catch up with operating performance?
Sources
2-
1H FY27 Results Presentation (opens in a new tab)Verified company source. Catapult Sports Ltd · 17 Nov 2026 · catapult.com
-
1H FY27 Results Release (opens in a new tab)Verified company source. Catapult Sports Ltd · 17 Nov 2026 · catapult.com