Horizon Gold advances Gum Creek toward its next major funding test

Horizon Gold has reaffirmed the economics of its proposed Gum Creek restart while moving early works, plant tendering and project finance toward a targeted Q2 2027 final investment decision. The project remains highly capital-intensive, with funding not yet committed and the production case partly reliant on resources outside the Ore Reserve.
- A$350 million pre-production capital requirement
- 880koz recovered gold targeted over 10 years
- A$1.307 billion NPV5 and 53.1% IRR reaffirmed
- Project finance process underway with Orimco advising
- Q2 2027 final investment decision targeted
 Add us as a preferred source on Google
Horizon Gold Limited (ASX:HRN) is putting a proposed A$350 million funding requirement at the centre of its path to restart the Gum Creek Gold Project, with a final investment decision targeted for the second quarter of 2027. The company’s November AGM presentation largely reaffirms the July feasibility study rather than introducing a new economic case, but it sets out a development program that is beginning to move from study work towards financing, tendering and approvals.
Project Finance Moves Into Competitive Process
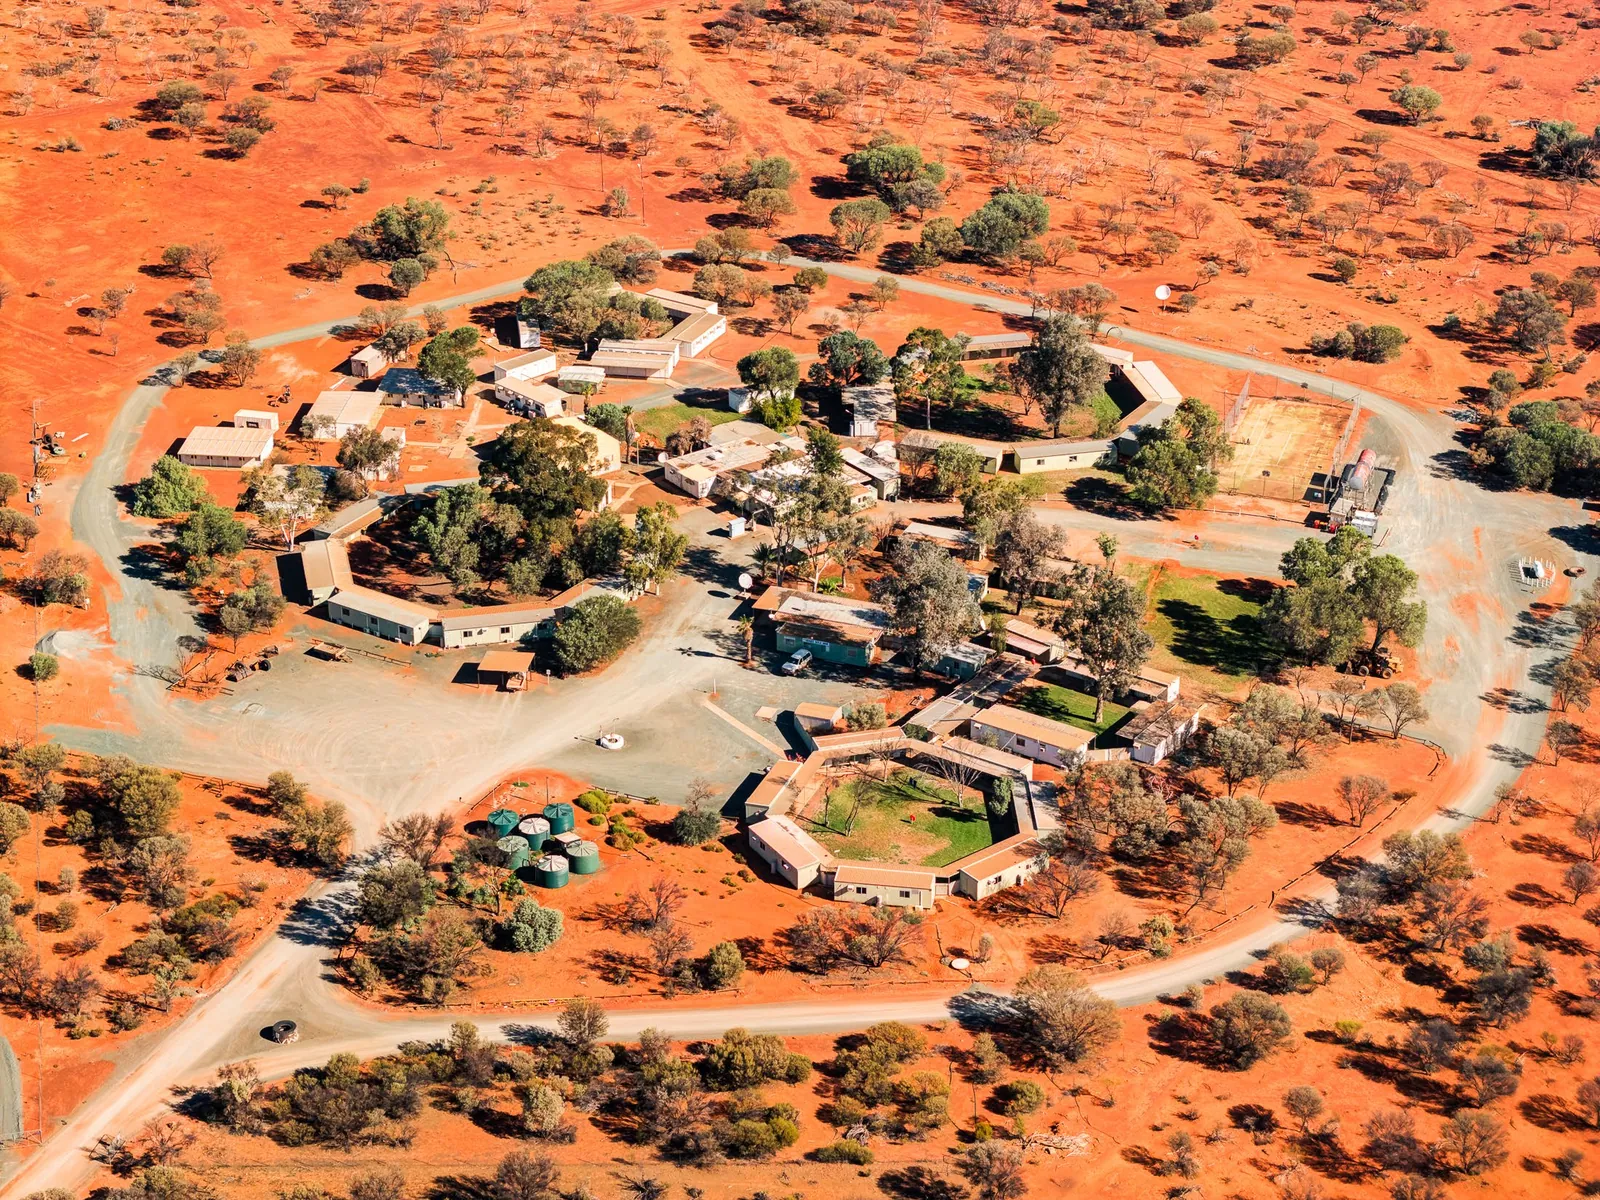
Horizon has appointed Orimco as project finance adviser and says expressions of interest have been received from Australian and global mining financiers. Independent technical, environmental and legal experts have also been appointed. Early works include tendering for an accommodation-village expansion, while tendering for the proposed 2.4 million-tonne-a-year process plant has begun, with a contractor appointment expected in the second quarter of 2027.
The funding hurdle is substantial relative to Horizon’s stated cash balance of A$16.95 million at 30 September 2026. The company had no debt at that date, but says there is no certainty it will raise the required capital when needed, or that any funding would be available without dilution or other effects on existing shareholders. That financing risk was also central to the Gum Creek funding warning raised in the company’s annual-report coverage.
July DFS Economics Remain the Development Case
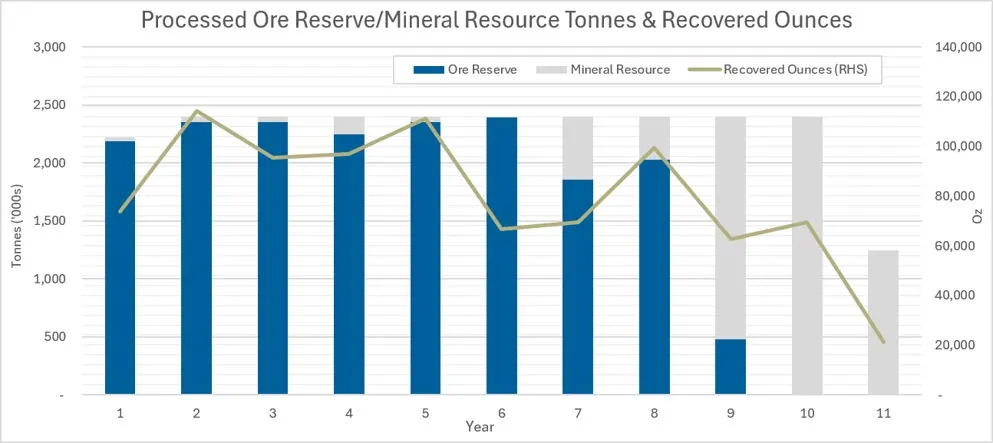
The presentation repeats a 10-year production target of 880,000 ounces of recovered gold, including average production of 98,000 ounces a year in the first five years. The July 2026 DFS figures point to an NPV5 of A$1.307 billion, a 53.1% internal rate of return, life-of-mine free cash flow of A$1.854 billion and an all-in sustaining cost of A$2,995 an ounce. First gold remains scheduled for the second half of 2028, subject to funding, approvals, construction and operating performance.
The planned open-pit operation is based on mining 25.1 million tonnes at 1.19 grams per tonne for 962,000 mined ounces, with 880,000 ounces expected to be recovered. The Ore Reserve is smaller at 18.2 million tonnes grading 1.24 grams per tonne for 728,000 ounces, and is based on a A$4,500 gold-price assumption for pit optimisation and cut-off calculations.
Exploration and Underground Resources Sit Outside the DFS
Horizon is presenting Gum Creek as more than a single open-pit restart. Free-milling underground resources at Swan, Swift and Kingfisher total 416,000 ounces at 3.6 grams per tonne, while the Wilsons underground sulphide resource contains 400,000 ounces at 4.31 grams per tonne. Those resources are outside the current DFS mine plan and therefore represent potential expansion rather than committed production.

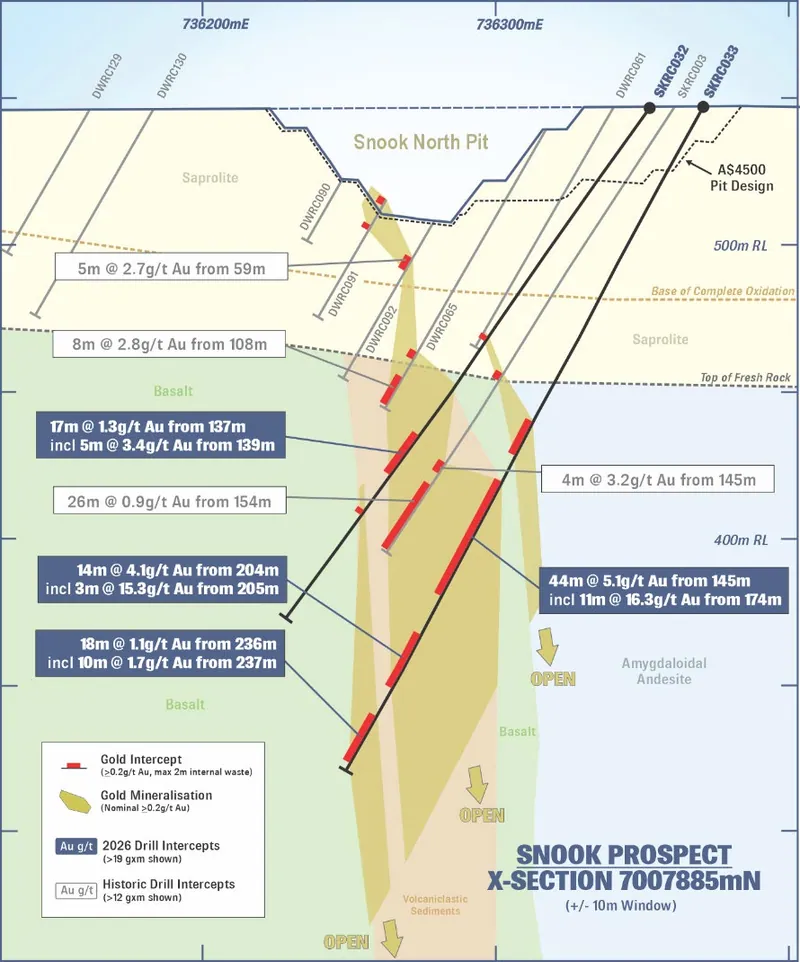
Exploration is continuing across the 80-kilometre greenstone belt. Drilling at Kingfisher and Swan is aimed at extending known mineralisation, while Howards and Snook are being tested for resource growth. The program follows Snook drilling results that included a 44-metre intersection grading 5.08 grams per tonne, although exploration results remain separate from the current Ore Reserve and production schedule.
Production Target Carries Resource Qualification
Horizon says 76% of the production target is underpinned by Probable Ore Reserves, 18% by Indicated Resource ounces outside the Ore Reserve and 6% by Inferred Resources. The first five years are more firmly supported, with approximately 97% of ounces attributed to Probable Ore Reserves and 3% to Inferred Resources. The company says the Inferred component is not a determining factor in project viability, but acknowledges that it carries a low level of geological confidence and may not be converted through further work.
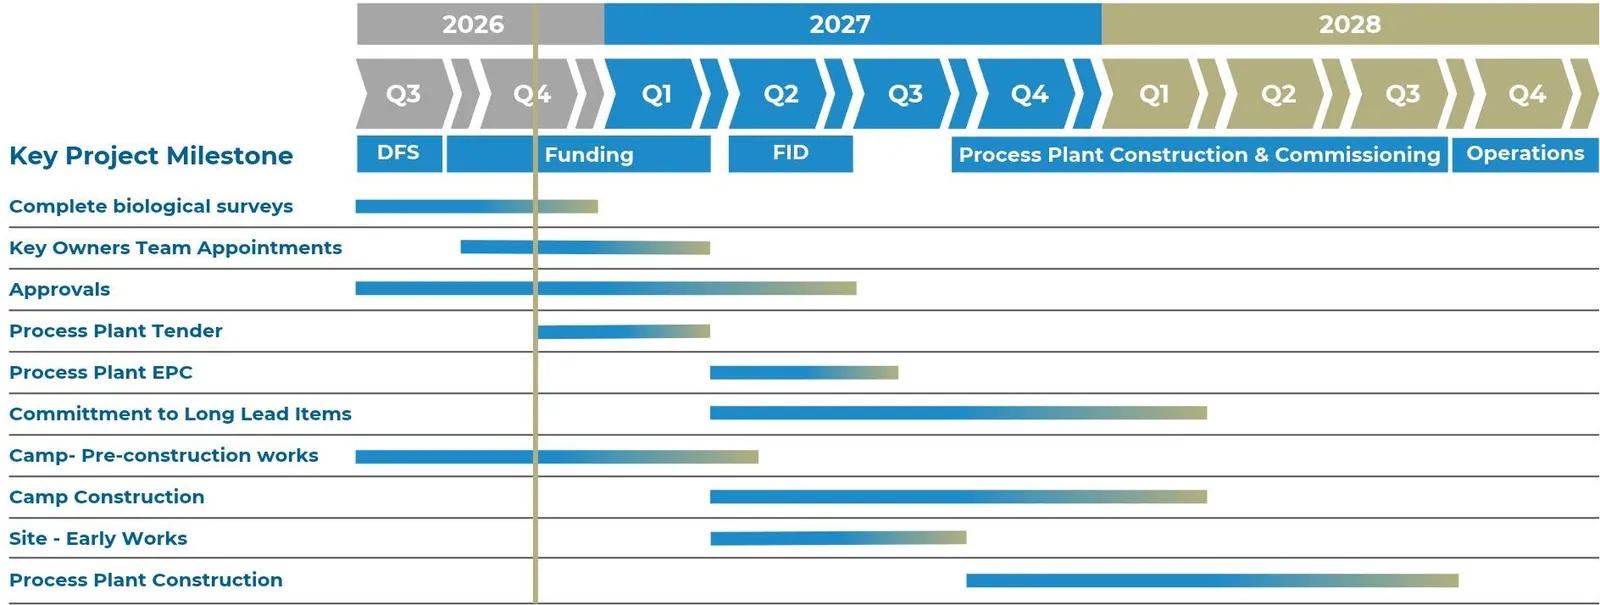
The next material test is therefore not another headline resource number. It is whether Horizon can convert a positive DFS into committed finance, approvals and a construction decision without changing the assumptions behind the production target. The targeted Q2 2027 FID will bring those questions into sharper focus.
Get ASX:HRN news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Gum Creek has a sizeable economic case on paper, but the next value-defining milestone is committed project finance rather than further repetition of the DFS metrics.
Questions in the middle?
- Can Horizon secure the A$350 million required for development on terms that limit dilution to existing shareholders?
- Will approvals, plant contracting and early works remain aligned with the targeted Q2 2027 final investment decision?
- How much of the underground and sulphide resource can ultimately be converted into an operating plan or reserve?
Sources
1-
Managing Director's AGM Presentation (opens in a new tab)Verified company source. Horizon Gold Limited · 19 Nov 2026 · horizongold.com.au