Lowe’s sales momentum earns a higher fiscal 2026 forecast

Lowe’s lifted its fiscal 2026 sales and comparable-sales forecasts after third-quarter sales rose 9.3%, but lower margins and a US$250 million tariff refund complicate the earnings picture. Online, Pro and home-services growth provided the operational momentum behind the quarter.
- US$22.8 billion in third-quarter sales, up 9.3%
- Comparable sales increased 1.8% for a sixth consecutive positive quarter
- Adjusted diluted EPS reached US$3.10, including a US$0.34 tariff-refund benefit
- Full-year sales outlook raised to approximately US$92.5 billion
- Operating-margin guidance trimmed to 11.1% and adjusted margin to 11.5%
 Add us as a preferred source on Google
A US$250 million tariff refund helped Lowe’s Companies, Inc. (NYSE:LOW) clear a higher earnings bar in its fiscal third quarter, while the home-improvement retailer also raised its full-year sales forecast. Lowe’s reported US$22.8 billion in sales for the quarter ended October 30, up 9.3% from a year earlier, with comparable sales increasing 1.8%.
The result marked Lowe’s sixth consecutive quarter of positive comparable sales. Online sales rose 17.4%, while the company pointed to continued strength in its Pro and home-services businesses. Chief executive Marvin Ellison said the performance reflected the resilience of the company’s “Total Home” strategy, which also includes its MyLowe’s Rewards programme and efforts to improve fulfilment, assortment and in-stock levels.
Tariff Refund Boosts Reported Earnings
Net earnings rose to US$1.7 billion from US$1.6 billion, while diluted earnings per share increased to US$2.98 from US$2.88. Adjusted diluted EPS, a non-GAAP measure, was US$3.10, up 1.3% from US$3.06 a year earlier after excluding acquisition-related intangible-asset amortisation.
Both reported and adjusted EPS included a US$0.34 benefit from refunds linked to the International Emergency Economic Powers Act, or IEEPA. Lowe’s said the refunds had a positive pre-tax impact of approximately US$250 million. That makes the headline earnings improvement less straightforward to assess as a measure of recurring trading performance, particularly because the filing does not provide market-consensus estimates.
Sales Forecast Raised While Margins Narrow
Lowe’s lifted its fiscal 2026 sales outlook to approximately US$92.5 billion from US$92.0 billion and now expects comparable sales to rise about 0.5%, compared with its previous expectation of a flat result. The company retained its diluted EPS forecast at approximately US$11.75 and its adjusted diluted EPS forecast at US$12.25.
The trade-off is visible in the margin guidance. Full-year operating margin was reduced to approximately 11.1% from 11.2%, while adjusted operating margin was trimmed to 11.5% from 11.6%. In the quarter, gross margin fell 124 basis points to 32.95%, and reported operating margin declined to 11.32% from 11.92% a year earlier. Lowe’s attributed the outlook update to results from the first three quarters, current demand trends and cost pressures, without quantifying each factor separately.
Growth Channels Carry the Strategy
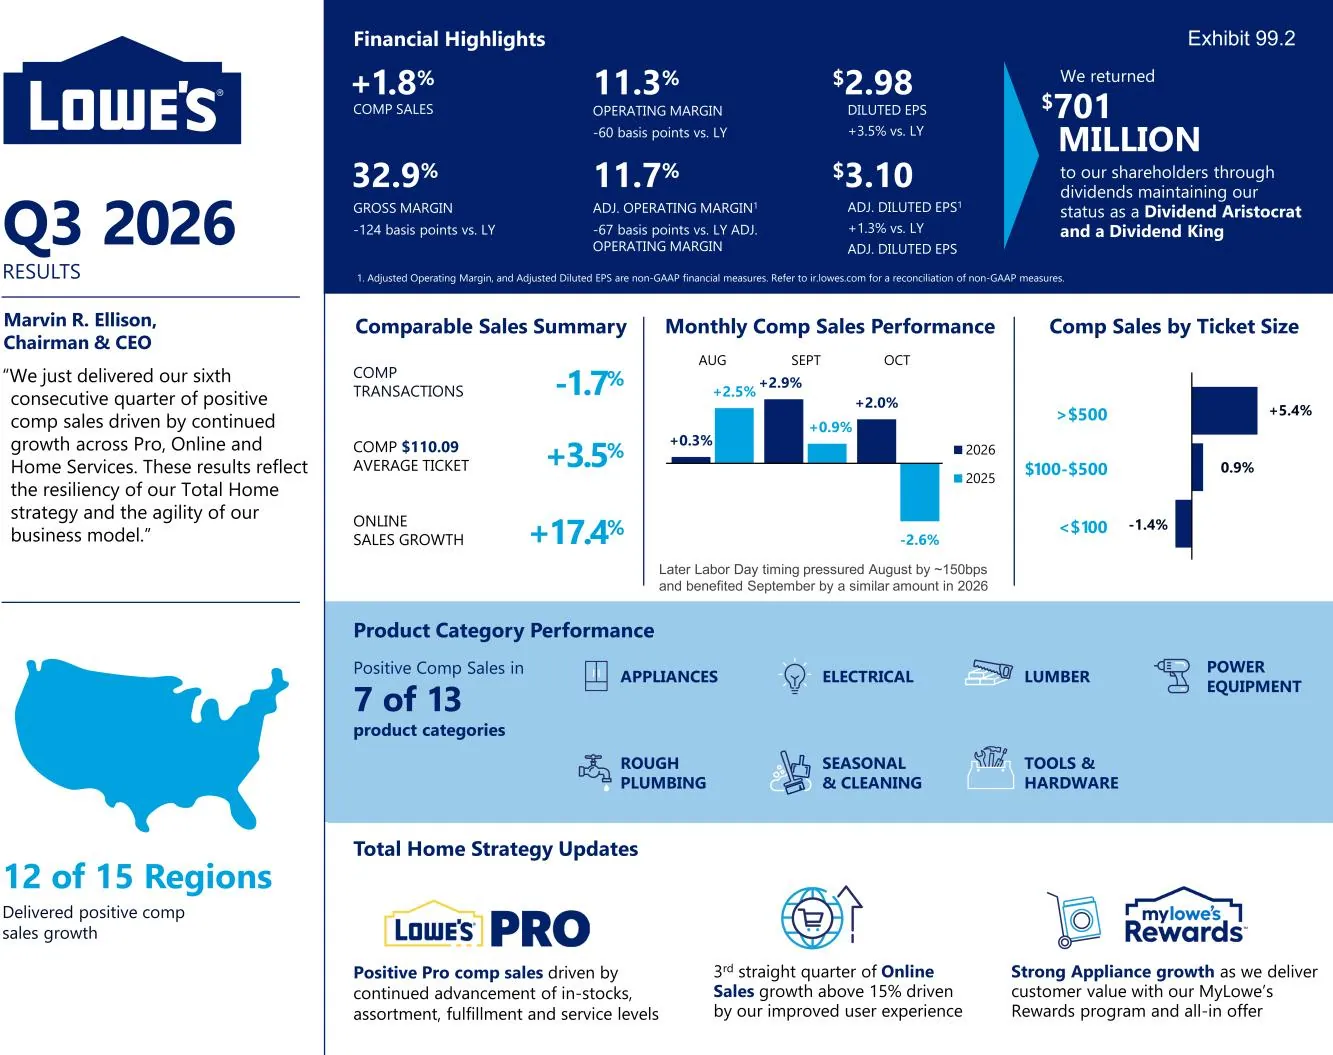
The quarter’s sales mix offered several signs of traction beyond the modest comparable-sales increase. Twelve of 15 regions delivered positive comparable-sales growth, seven of 13 product categories were positive, and online sales recorded a third consecutive quarter of growth above 15%, according to the company’s results presentation. Appliance sales were described as strong, while Pro sales benefited from progress in availability, range, fulfilment and service.
Lowe’s returned US$701 million to shareholders through dividends during the quarter and paid US$2.05 billion in dividends over the first nine months. It also spent US$368 million on share repurchases in the nine-month period, while capital expenditure reached US$1.66 billion. Cash and equivalents stood at US$3.43 billion at October 30, compared with US$621 million a year earlier, although long-term debt remained substantial at US$34.48 billion excluding current maturities.
The immediate tension is clear: Lowe’s is producing sales growth across several strategic channels and has nudged up its annual revenue expectations, but margins are moving in the opposite direction and a sizeable one-off refund supported quarterly EPS. The December analyst and investor conference should provide a sharper test of whether the company can convert its online, Pro and home-services momentum into durable profit growth after the tariff benefit fades.
Get NYSE:LOW news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Lowe’s has raised the top line, but the next test is whether operating margins can stabilise without further help from the tariff refund.
Questions in the middle?
- How much of the fiscal 2026 EPS outlook depends on the US$0.34-per-share tariff-refund benefit?
- Can online, Pro and home-services growth offset the pressure visible in gross and operating margins?
- Will the December investor conference produce new detail on Lowe’s acquisition integration and longer-term growth plans?
Sources
1-
Results of Operations and Financial Condition (opens in a new tab)Official market announcement. SEC filing · Lowe's Companies, Inc. · 18 Nov 2026 · sec.gov