My Food Bag turns stronger cash flow into debt-free growth capacity

My Food Bag lifted first-half EBITDA 11.4% and repaid its remaining bank debt, giving the NZX-listed meal-kit company room to keep paying dividends. But softer trading in the opening seven weeks of the second half leaves its full-year growth forecast dependent on a recovery in demand.
- Revenue increased 4.3% to NZ$89.0 million
- EBITDA rose 11.4% to NZ$8.0 million
- Free cash flow of NZ$5.8 million cleared all bank debt
- Fully imputed interim dividend of 0.90 cents per share declared
- Early second-half trading softened, but full-year revenue growth remains expected
 Add us as a preferred source on Google
Debt repayment strengthens My Food Bag's balance sheet
My Food Bag Group Limited (NZX:MFB) has reached a useful financial milestone: it generated enough free cash flow in the first half to repay all remaining bank debt while still declaring an interim dividend. Free cash flow rose to NZ$5.8 million from NZ$3.1 million a year earlier, leaving NZ$1.0 million of cash and no borrowings at 30 September.
The balance sheet is not entirely unencumbered. My Food Bag still has NZ$15 million of undrawn facilities, including a NZ$10 million revolving credit facility and a NZ$5 million overdraft facility. But the shift from NZ$1.9 million of net debt at the end of March to net cash marks a material change in the company's financial flexibility.
Revenue and margins improve despite stable customer numbers
Revenue increased 4.3% to NZ$89.0 million in the six months ended 30 September, while EBITDA, a non-GAAP measure, rose 11.4% to NZ$8.0 million. Net profit after tax edged up 4.7% to NZ$3.0 million.
The performance was driven less by a surge in customers than by better economics from the existing base. Active customers were broadly unchanged at 61,000, but average order value rose to NZ$135.60 from NZ$130.90 and order frequency increased to 5.7 from 5.6. Retained customers represented 61.3% of active customers, up from 60.5%, according to the company.
Gross margin improved to 21.3% from 20.8%, despite food price inflation and fuel cost pressure. My Food Bag attributed the improvement to supply chain efficiencies, direct sourcing, recipe optimisation, packaging changes and tighter workforce management. The comparative period's production depreciation and amortisation figures were reclassified, with no impact on prior-year net profit.
Standalone strategy moves from review to execution
The result gives financial substance to the company's strategic review outcome, which confirmed that My Food Bag would remain listed on the NZX and focus on organic growth, margin improvement and disciplined capital allocation. The board has declared a fully imputed interim dividend of 0.90 cents per share and is targeting total ordinary dividends equal to 70% to 90% of full-year NPAT.
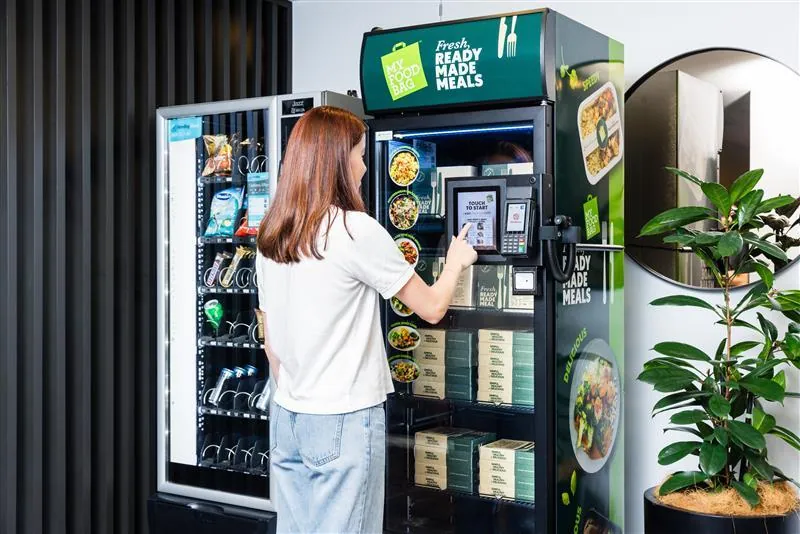
Growth initiatives extend beyond the traditional subscription box. My Food Bag has expanded meal customisation, launched Fresh Start Healthy Ready Made meals, developed its one-off Shop to more than 40 products and progressed a vending-machine pilot for offices, apartments and hotels. It also launched a Foodie Rewards pilot, with a wider rollout to be considered in 2027.
Softer second-half start puts revenue outlook under scrutiny
The clean first-half numbers come with a less comfortable forward indicator. Trading in the first seven weeks of the second half has softened and is broadly in line with the prior year. My Food Bag nevertheless continues to expect full-year revenue growth, while warning that the timing of Easter means there will be fewer normal trading weeks in the fourth quarter.
The company has also forecast FY27 capital expenditure of approximately NZ$3.2 million to NZ$3.6 million. The immediate question is whether higher order values, retention and new product channels can offset a customer market that is showing less momentum. Chair Tony Carter is retiring after 19 November, with Mark Powell appointed as his successor, adding a governance transition as the standalone strategy enters its next phase.
Get NZX:MFB news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
My Food Bag enters the second half with no bank debt and a dividend framework, but the next test is converting stable customer numbers into renewed demand before Easter distorts the annual comparison.
Questions in the middle?
- Can higher average order values and retention offset softer second-half trading?
- How quickly will Ready Made, Shop and partnership channels contribute meaningful revenue?
- Will the targeted 70% to 90% payout range remain covered if full-year demand stays subdued?
Sources
3-
MFB Results Presentation - FY27 H1 (opens in a new tab)Official market announcement. My Food Bag Group Limited · 19 Nov 2026 · investors.myfoodbag.co.nz
-
MFB Interim Report - FY27 H1 (opens in a new tab)Official market announcement. My Food Bag Group Limited · 19 Nov 2026 · investors.myfoodbag.co.nz
-
MFB Media Release - FY27 H1 (opens in a new tab)Official market announcement. My Food Bag Group Limited · 19 Nov 2026 · investors.myfoodbag.co.nz