Shriro backs Everdure Lagoon launch after FY26 profit surge

6 min read
1:37pm on Wednesday 18th of November, 2026 AEDT ~1pm, 18th Nov, 26
Shriro Holdings delivered a sharp FY26 profit increase, but is guiding to lower EBITDA in FY27 as it funds the launch of its Everdure Lagoon BBQ range and absorbs normalised calculator sales. The debt-free group says its balance sheet still gives it room to invest, return capital and pursue acquisitions.
- FY26 revenue rose 7.5% to A$111.0 million
- EBITDA increased 21.6% to A$18.6 million
- FY27 EBITDA guidance set at A$12 million to A$15 million
- Everdure Lagoon launches in Australia for the 2026/27 summer
- A$15.1 million returned to shareholders during FY26
 Add us as a preferred source on Google
FY27 guidance falls below a stronger FY26
Shriro Holdings Limited (ASX:SHM) is heading into FY27 with a paradox familiar to consumer brands: the business has just delivered one of its strongest years, but expects earnings to step back as it spends on the next product cycle. Management guided to EBITDA of A$12 million to A$15 million for FY27, below the A$18.6 million recorded in FY26.
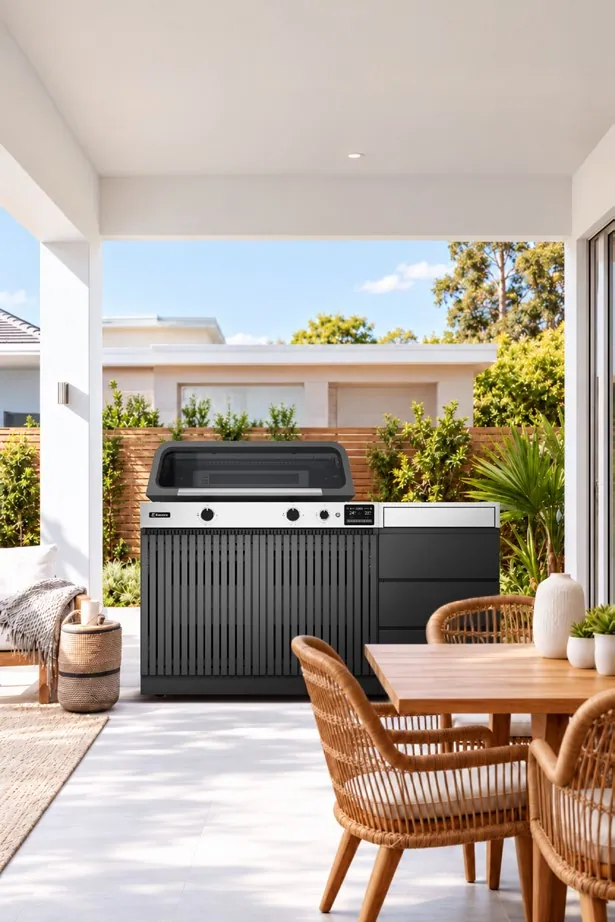
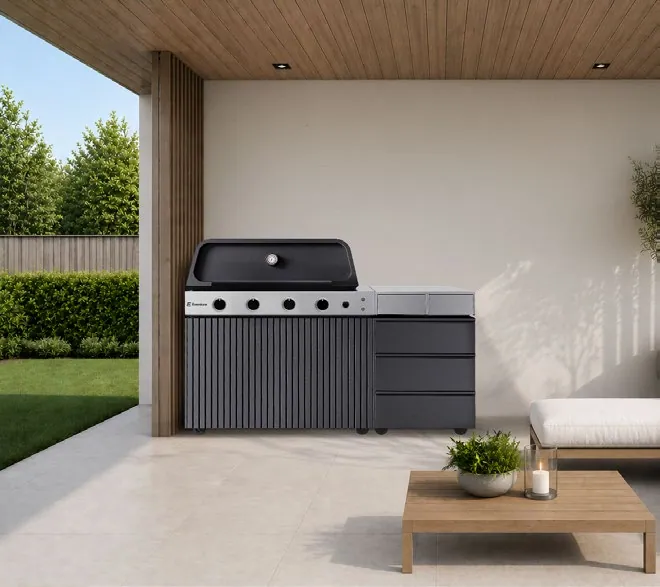
The company attributed the lower outlook to increased marketing investment for the Everdure Lagoon BBQ launch and the normalisation of calculator sales after a timing benefit in FY26. The guidance is a range rather than a detailed earnings forecast, leaving the success of the product rollout and the durability of demand central to the year ahead.
Revenue and profit accelerate in FY26
Shriro’s FY26 numbers were considerably stronger than its top-line growth alone suggests. Revenue increased 7.5% to A$111.0 million, while EBITDA rose 21.6% to A$18.6 million and net profit after tax jumped 44% to A$10.8 million. Earnings per share climbed 75% to 14.7 cents.
The result was supported by growth in BBQ products, calculators and exports, alongside a recovery in seasonal product sales. Export revenue increased 36.4%, with the company pointing to rising demand for Everdure products. Operating expenses rose just 0.3%, below inflation, while the gross margin held at 45%.
The presentation restated the FY26 results and guidance, which had previously detailed the same A$111 million revenue result, A$10.8 million NPAT and A$12 million to A$15 million FY27 EBITDA range.
Everdure Lagoon becomes the key product test
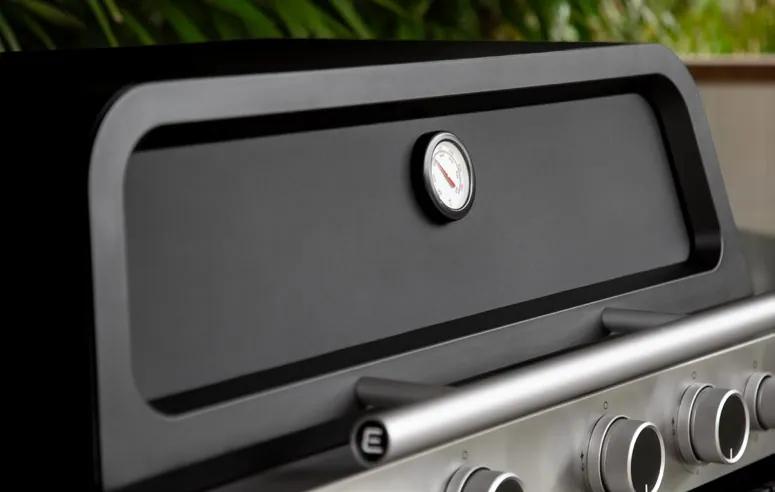
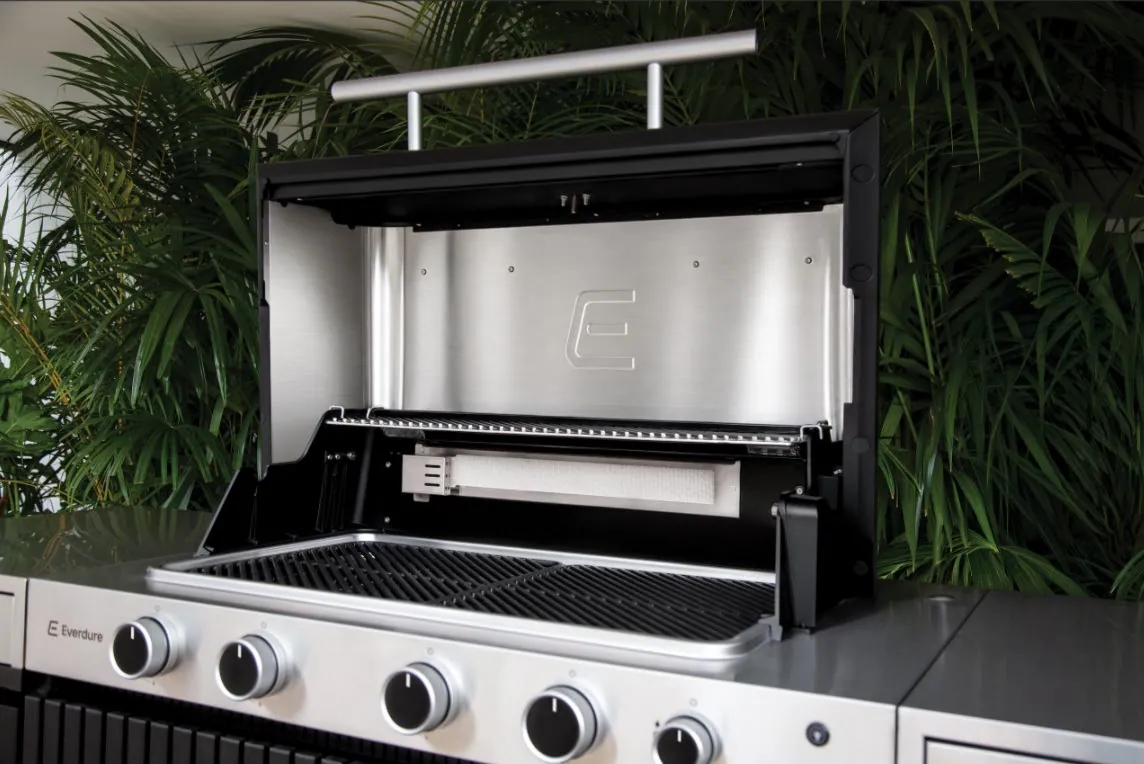
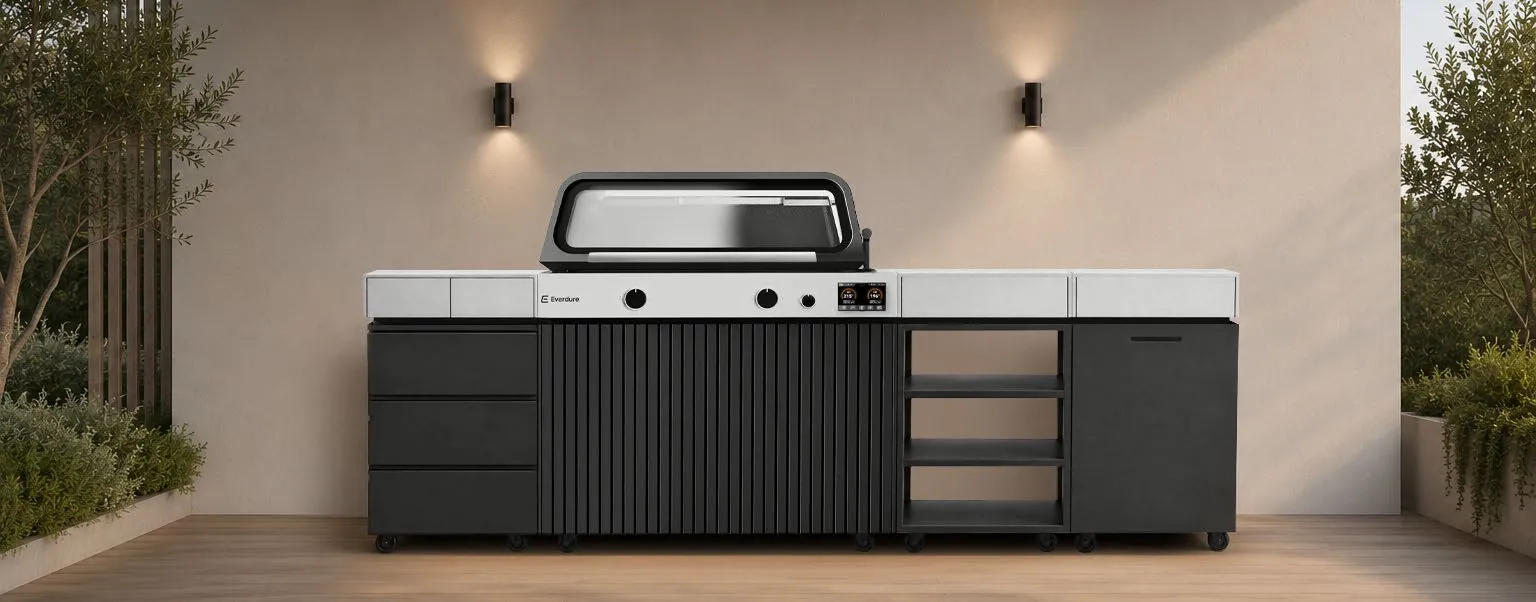
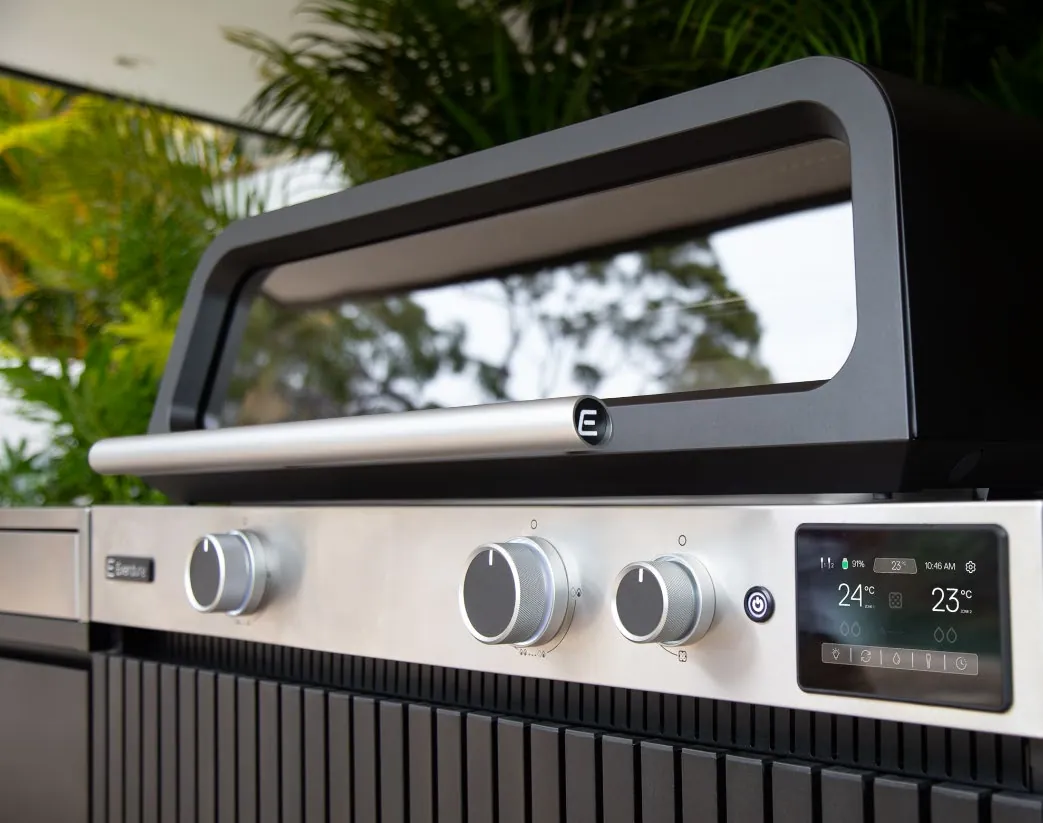
The Lagoon collection is scheduled to launch in Australia during the 2026/27 summer, followed by introductions in Europe, the United Kingdom and the United States ahead of the Northern Hemisphere summer in 2027. The range includes the Lagoon and Lagoon Pro BBQs, modular carts and accessories, with features including dual-burner control on the Pro model, integrated rotisserie and a connected display with customisation options.
Shriro said the launch was delayed, but described the product platform as an opportunity for FY27 and beyond. The company’s stated capital-light model relies on product development and brand ownership, while international distributors handle inventory, debtors, aftercare and local marketing. That structure may limit Shriro’s working-capital requirements, but the near-term earnings outcome will still depend on how effectively the new range converts marketing spend into sales.
Debt-free balance sheet supports capital returns
Shriro ended FY26 with A$9.1 million of cash at 30 June and reported A$17.3 million at 31 July, with no debt. During FY26, it returned A$15.1 million to shareholders through A$3.8 million of fully franked dividends and A$11.3 million of share buy-backs. Since its 2015 IPO, the company says it has generated A$172 million in cash, including A$81.4 million in dividends, a A$17.8 million capital return and A$26.3 million in buy-backs.
That shareholder-return strategy has been a recurring feature of Shriro’s capital allocation, including the March off-market buy-back, which was announced at up to A$15 million. The board said it would continue assessing capital-management initiatives while also considering selective acquisitions and investment in new products.
ERP project completes as portfolio narrows
The company also completed its three-year ERP implementation on time and within budget, and plans to use the platform to pursue further operational efficiencies and improve decision-making. Shriro has exited its New Zealand Lixil distribution agreement, including the American Standard and Grohe brands, after a strategic review.
For FY27, management’s stated priorities are the Everdure Lagoon rollout, export growth, new product development, e-commerce investment and targeted acquisitions. The tension is straightforward: the group has financial flexibility and a growing export engine, but its next earnings step depends on replacing a favourable calculator timing effect while funding a more ambitious BBQ launch.
Get ASX:SHM news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
The key test is whether Everdure Lagoon can turn FY27’s planned marketing outlay into sustained international growth before the balance sheet’s flexibility is called on for acquisitions or further returns.
Questions in the middle?
- Can the Everdure Lagoon launch offset the normalisation of calculator sales?
- How much of the A$12 million to A$15 million EBITDA range will be absorbed by marketing and rollout costs?
- Will Shriro prioritise further buy-backs, acquisitions or product investment with A$17.3 million of cash and no debt?
Sources
1-
AGM Chair's Address and CEO Presentation (opens in a new tab)Official market announcement. Shriro Holdings Limited · 18 Nov 2026 · shriro.com.au