FirstEnergy unlocks bigger growth plan with West Virginia generation approval

West Virginia regulators have approved FirstEnergy’s planned Maidsville gas and solar project, prompting a larger investment programme and higher long-term earnings growth target. The expansion also raises the company’s expected equity financing needs by US$800 million.
- Approval for 1,200 MW Maidsville combined-cycle gas facility and 70 MW of solar
- 2026-2030 capital plan increased from US$36 billion to US$38 billion
- Long-term Core EPS growth target raised to 7%-9% CAGR
- Equity or equity-like financing need increased to US$2.8 billion
- New surcharge designed to recover construction-period financing costs
 Add us as a preferred source on Google
FirstEnergy Corp. (NYSE:FE) has received West Virginia approval to build a 1,200 megawatt combined-cycle gas plant and 70 megawatts of utility-scale solar, turning a regulatory decision into a larger growth plan for the US utility. The company lifted its 2026-2030 capital programme from US$36 billion to US$38 billion and raised its long-term Core Earnings per share growth target to a 7%-9% compound annual rate, with management targeting the upper half of that range.
Maidsville approval adds generation and construction cost recovery
The Public Service Commission of West Virginia’s 17 November order granted Monongahela Power and Potomac Edison certificates to construct the Maidsville Energy Center. The project is expected to include a 1,200 MW gas facility at Maidsville, alongside 70 MW of solar across three West Virginia sites, with the gas plant targeted for operation by 31 December 2031 and the solar projects scheduled between 2027 and 2030.
The order also approved a new generation surcharge intended to provide cash recovery of financing costs while the projects are being developed and built. FirstEnergy says the surcharge would transition to recovery through base rates once assets enter service and are approved through a base-rate case. The filing does not remove the usual execution variables: gas and engineering, procurement and construction contracts are expected in the fourth quarter of 2026, site preparation is planned for the first quarter of 2027, and the project remains subject to construction, cost and financing risks.
US$38 billion plan pushes rate base growth higher
FirstEnergy’s revised plan now implies an 11.1% rate-base compound annual growth rate, up from 10.4% previously. The company’s presentation allocates US$19 billion to transmission, US$9 billion to infrastructure renewal, US$6 billion to grid modernisation, US$2 billion to new generation and US$1.2 billion to energy efficiency. It also says transmission investment is expected to rise by at least 25% from the previous US$19 billion plan, partly reflecting network upgrades and connections for large customers.
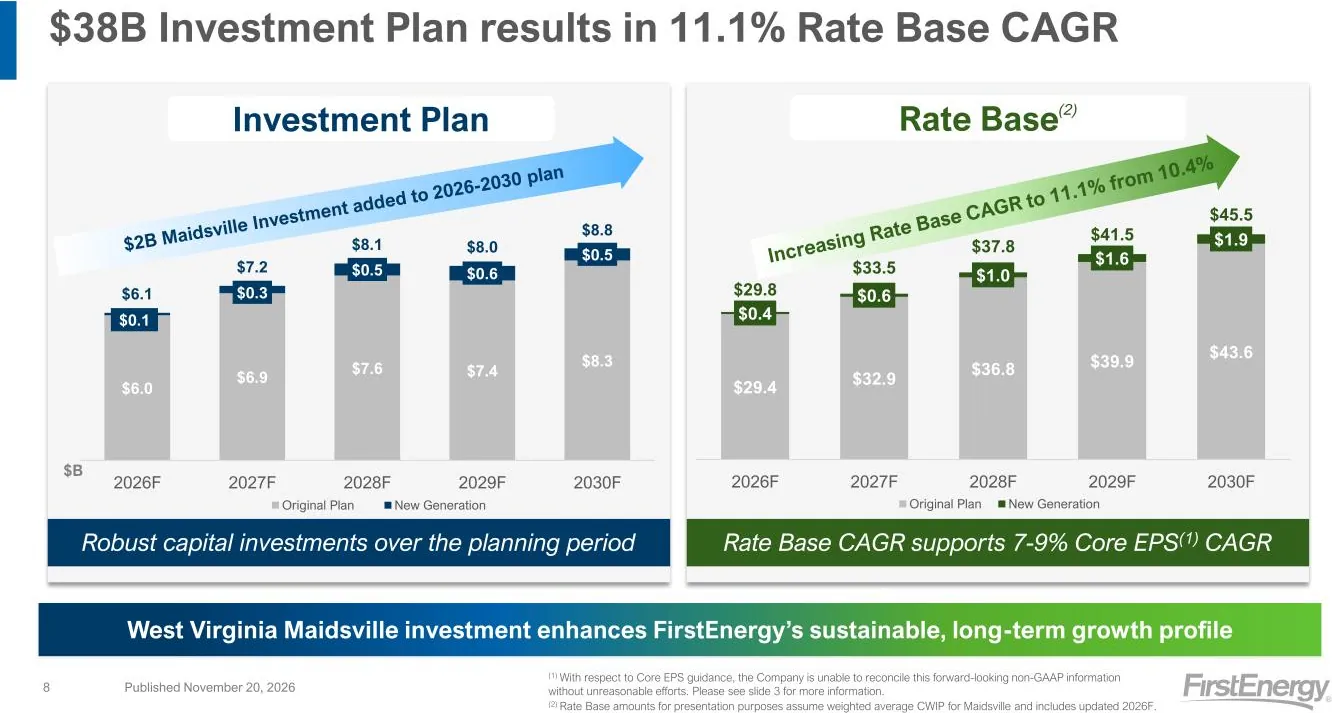
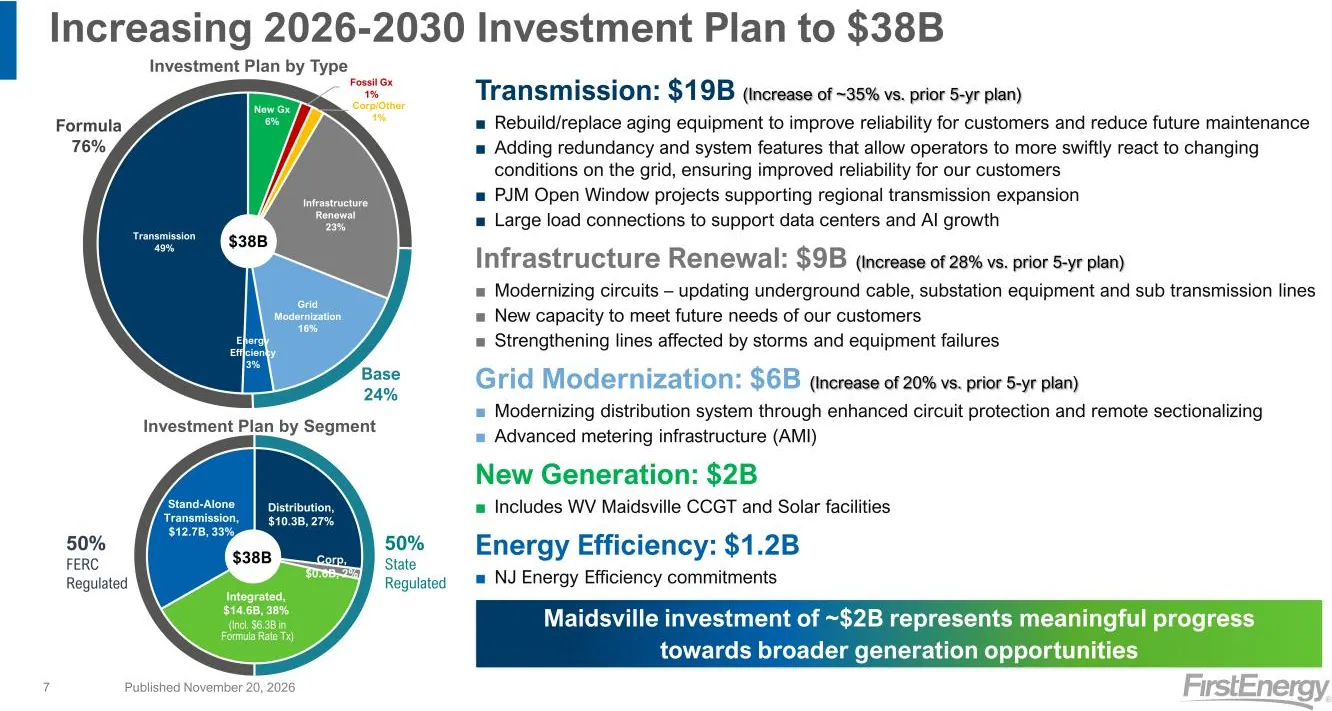
The figures are forward-looking rather than reported earnings. Core EPS and its 7%-9% growth rate are non-GAAP measures, and FirstEnergy says it cannot reconcile the projections to the comparable GAAP measures without unreasonable effort because future special items are difficult to predict. The project’s presentation gives a US$2.7 billion total estimate for the combined gas and solar developments, while the 2026-2030 plan adds approximately US$2 billion of investment, a distinction that matters when assessing the scale of the revision.
Higher growth target comes with more equity funding
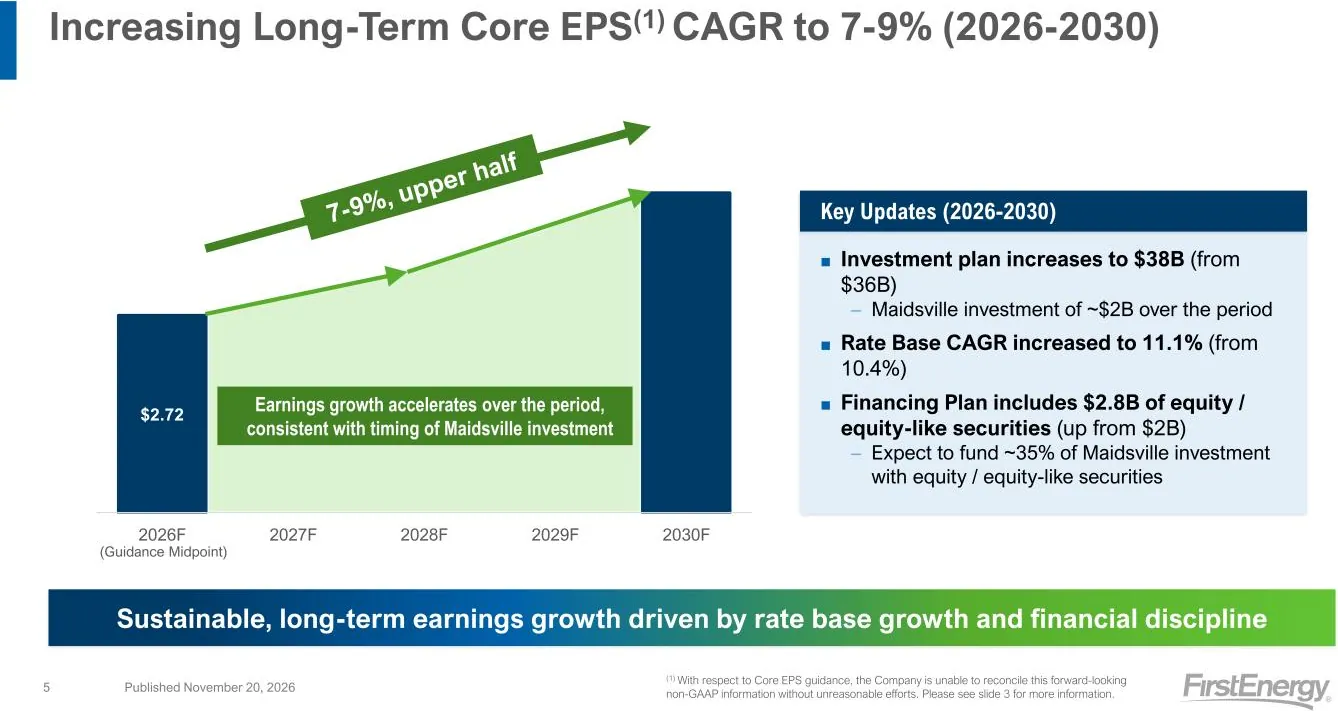
FirstEnergy expects to fund about 35% of the Maidsville investment with equity or equity-like securities, lifting anticipated equity financing needs for 2026-2030 from US$2.0 billion to US$2.8 billion. The company is also seeking Department of Energy approval for lower-cost project financing and says a guaranteed loan could generate customer savings of about US$217 million for each US$1 billion financed over 30 years, although that financing has not been approved in the announcement.
That is the central trade-off in the updated plan: a larger regulated asset base and a higher earnings-growth ambition, alongside greater capital requirements and potential shareholder dilution or dilution-like funding. The next meaningful evidence will come from the project contracts, the initial surcharge filing, DOE financing decision and the annual construction cost updates beginning in January.
Get NYSE:FE news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
Maidsville gives FirstEnergy a stronger regulated-growth pathway, but the upgraded earnings target now depends on disciplined construction and a larger equity funding programme.
Questions in the middle?
- Will the Department of Energy approve the proposed low-cost financing, and on what terms?
- How will FirstEnergy structure the additional US$800 million of equity or equity-like financing?
- Can Maidsville remain on schedule and within its estimated cost as contracts and site work begin?
Sources
1-
Regulation FD Disclosure; Other Events (opens in a new tab)Official market announcement. SEC filing · FirstEnergy Corp. · 20 Nov 2026 · sec.gov