FSA Group sets $600m lending target after strong FY2026 growth

FSA Group delivered a sharp FY2026 earnings increase as car loans and asset finance expanded, while setting a target of more than $600 million in annual originations. The lender also flagged rising impairment costs and pledged an 8.00 cent per share dividend for FY2027.
- Profit before tax rises 48% to $23.9 million
- Loan pools reach $1.075 billion after 18% growth
- Car loans and asset finance drive origination expansion
- Impairment expense increases to $16.5 million
- FY2027 dividend target rises to 8.00 cents per share
 Add us as a preferred source on Google
Profit growth accelerates as lending volumes expand
FSA Group Limited (ASX:FSA) is aiming to push annual loan originations beyond $600 million after reporting a 48% increase in FY2026 profit before tax to $23.9 million. Operating income rose 27% to $81.3 million, while profit after tax attributable to members reached $14.1 million and basic earnings per share increased to 11.8 cents.
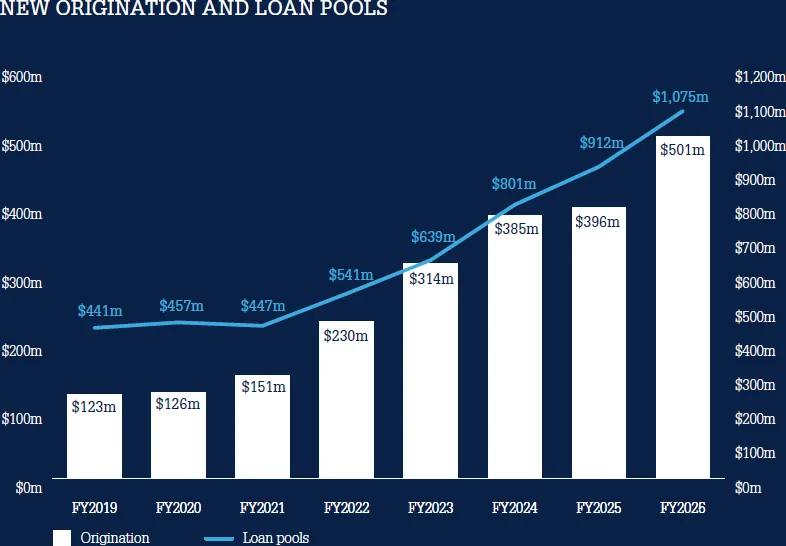
The result was powered by a larger lending book and a stronger net margin. Loan pools grew 18% to $1.075 billion, originations rose 26% to $501 million and net finance income increased 31% to $74.8 million. Net margin improved from 49% to 54%, helping the business generate operating leverage as it expanded.
Car loans and asset finance carry the expansion
Car loans and asset finance supplied most of the momentum. Car-loan originations increased 50% to $150 million, lifting the division’s loan pool to $267 million, while asset-finance originations rose 31% to $249 million and its pool reached $437 million.
Asset finance produced the largest earnings increase, with profit before tax rising 148% to $11.4 million. Car-loan profit before tax climbed 30% to $10.4 million. Home lending remained profitable but contracted in scale, with originations falling to $96 million and its loan pool declining to $362 million. Unsecured personal loans remain in a pilot phase and generated a $1.4 million loss before tax.
The growth strategy builds on an earlier automation-led loan-pool target from FSA Group, which had previously outlined a pathway towards a $1.3 billion loan pool. The company now says automation, broker adoption and available funding will determine whether it can move beyond the current $501 million origination base.
Credit costs rise alongside the loan book
The earnings improvement came with a more expensive credit environment. Total impairment expense rose from $11.6 million to $16.5 million, while reported losses increased from $5.5 million to $9.5 million. Arrears of more than 30 days rose in car loans from 3.21% to 3.74% and in asset finance from 3.59% to 3.76%; home-loan arrears eased to 4.17% from 5.14%.
FSA Group attributed arrears pressure to cost-of-living and interest-rate pressures. The presentation also says 66% of the loan pool was fixed-rate at FY2026, with about 71% of fixed-rate loans hedged in the outlook period. That leaves credit performance, funding costs and the effectiveness of arrears management as important tests of whether volume growth converts into sustained earnings.
Securitisation adds funding capacity
Funding capacity has expanded alongside the lending book. FSA Group disclosed a $200 million November 2026 asset-backed securities transaction, following the $200 million ABS transaction priced in October. Its facilities include warehouse funding from Westpac for home and personal loans, a separate asset-finance warehouse, and securitised funding with institutional investors.
The company said its personal-loan warehouse limit increased from $85 million to $125 million in July 2026, while the asset-finance limit rose from $200 million to $260 million in August. The facilities are supported by mezzanine non-recourse funding from institutional fund managers, although the presentation does not provide FY2027 profit-before-tax guidance.
FY2027 targets combine growth with a higher dividend
For FY2027, FSA Group expects continued growth in originations and loan pools, led by car loans and asset finance. It plans further investment in automation and its offshore office, while continuing an on-market buy-back when opportunities arise.
The company’s stated dividend target is 8.00 cents per share, up from 7.00 cents in each of the previous two financial years. The immediate question is whether FSA Group can preserve its improved margin and credit performance while scaling towards a $1.3 billion loan pool in a market still affected by household cost pressures and interest-rate sensitivity.
Get ASX:FSA news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
FSA Group has built useful momentum, but the next leg depends on converting larger loan pools into earnings without allowing impairment costs and arrears to accelerate faster than revenue.
Questions in the middle?
- Can originations rise above $600 million without materially weakening credit quality?
- Will higher funding capacity support growth at margins that remain near FY2026 levels?
- Can car-loan and asset-finance expansion offset rising impairment costs and the drag from unsecured personal loans?
Sources
1-
AGM Presentation 2026 (opens in a new tab)Official market announcement. Fsa Group Limited · 20 Nov 2026 · fsagroup.com.au