ALS mining surge powers stronger profit despite Life Sciences weakness

4 min read
8:29am on Monday 23rd of November, 2026 AEDT ~8am, 23rd Nov, 26
ALS has delivered a sharp lift in underlying earnings and dividend growth, powered by a 30.4% organic surge in Minerals. But the result also exposes a weaker side of the portfolio, with Life Sciences growth expectations cut to about 3% for FY27.
- Underlying NPAT up 23.6% to A$214.6 million
- Commodities organic revenue growth of 24.5%
- Life Sciences EBIT down 12.6% as Pharma weakens
- Interim dividend increased 20.1% to 23.3 cents per share
- FY27 Life Sciences growth target reduced to approximately 3%
 Add us as a preferred source on Google
Minerals drives ALS earnings higher
ALS Limited (ASX:ALQ) has posted a strong first-half earnings result, but the headline numbers conceal a widening divide between its two main businesses. Underlying net profit after tax rose 23.6% to A$214.6 million for the six months ended 30 September 2026, while underlying EBIT climbed 18.6% to A$332.7 million and the group margin expanded 250 basis points to 19.4%.
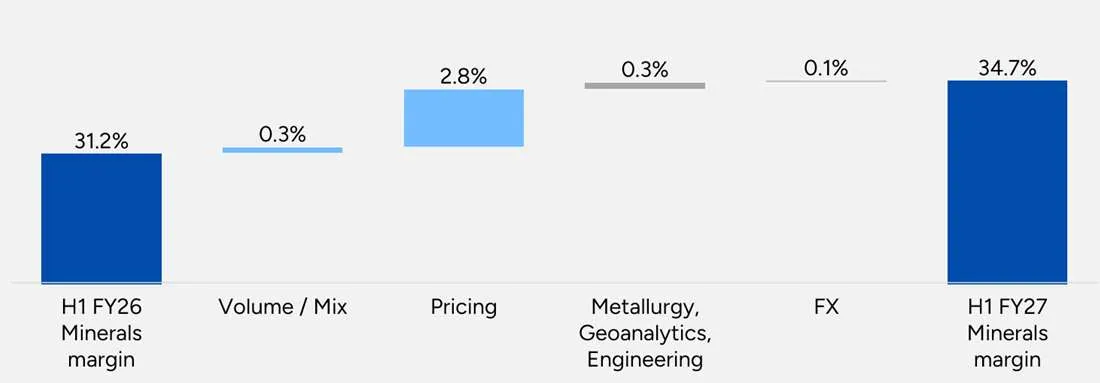
The engine was Commodities, where organic revenue increased 24.5% and underlying EBIT rose 36.4% to A$233.1 million. Minerals was particularly strong, delivering 30.4% organic revenue growth and lifting its EBIT margin by 350 basis points to 34.7% as higher sample volumes, pricing discipline, favourable mix and operating leverage combined. Geochemistry revenue grew 31.8%, while Metallurgy rose 20.7%.
That performance builds on the Saudi stake increase, which was flagged in earlier coverage as a planned move to 60%. ALS completed the additional 18% acquisition in July for A$64.0 million, taking control of Australian Laboratory Services Arabia Co. Ltd. and contributing two months of results to the half-year accounts.
Life Sciences misses expectations
Life Sciences was the counterweight. Reported revenue fell 6.6% to A$978.0 million and underlying EBIT declined 12.6% to A$134.0 million, pulling the division's margin down 95 basis points to 13.7%. On a constant-currency basis, revenue was broadly flat, with organic growth of just 1.8%.
Food remained a bright spot with 6.8% organic growth, while Environmental grew 2.1% despite difficult conditions in the Americas. Pharmaceutical revenue declined 4.1%, reflecting delayed conversion of its order book and lower activity in some key accounts, including Nuvisan. ALS said quality and compliance issues in the Americas had been addressed and that cost and commercial initiatives were under way at Nuvisan, but the recovery is not yet reflected in the first-half result.
The company now expects Life Sciences organic revenue growth of about 3% for FY27, below the mid-single-digit target previously outlined. Management expects a return to mid-single-digit growth in the second half, alongside a 40 to 60 basis-point improvement in the division's margin compared with the first half. That makes the second-half recovery a central test of whether the weakness is temporary or more persistent.
Dividend rises as balance sheet retains capacity
ALS declared an interim dividend of 23.3 cents per share, up 20.1% from the prior corresponding period and equivalent to a 55% payout of underlying NPAT. The dividend is 35% franked. Statutory NPAT more than doubled to A$297.5 million, although that figure includes a non-cash A$97.2 million fair-value gain generated by the Saudi Arabia transaction and is therefore not a clean measure of recurring operating performance.
Cash flow before capital expenditure increased 7.6% to A$327.1 million, while leverage remained at 1.5 times, below ALS's target range of 1.7 to 2.3 times. Available liquidity exceeded A$430 million. The company invested A$34.1 million in its hub-laboratory program during the half, taking cumulative spending to A$127.8 million; the Sydney facility was commissioned in July and Lima in October.
ALS is targeting high-single-digit organic revenue growth and margin expansion for FY27. Minerals growth is expected to moderate from the first-half surge as it cycles a stronger comparative period, although the company still targets about 20% organic growth for the division across the year. Foreign exchange and Middle East disruption costs remain headwinds, while the more immediate question is whether Environmental Americas and Nuvisan can convert management's planned fixes into revenue and margin in the second half.
Get ASX:ALQ news the moment it breaks
 iPhone & iPad
 Android
Bottom Line?
ALS has plenty of balance-sheet room to keep investing, but the next earnings test is less about Minerals momentum than whether Life Sciences can deliver the promised second-half repair.
Questions in the middle?
- Can Minerals sustain attractive margins as sample growth moderates against a stronger second-half comparison?
- Will the operational changes in Environmental Americas resolve the quality and compliance-related volume weakness?
- How quickly can Nuvisan convert its healthy order book into revenue and restore Pharmaceutical margins?
Sources
3-
Half Year Results (opens in a new tab)Official market announcement. Als Limited · 23 Nov 2026 · alsglobal.com
-
Half Yearly Report and Accounts (opens in a new tab)Official market announcement. Als Limited · 23 Nov 2026 · alsglobal.com
-
Half Year Results Investor Presentation (opens in a new tab)Official market announcement. Als Limited · 23 Nov 2026 · alsglobal.com